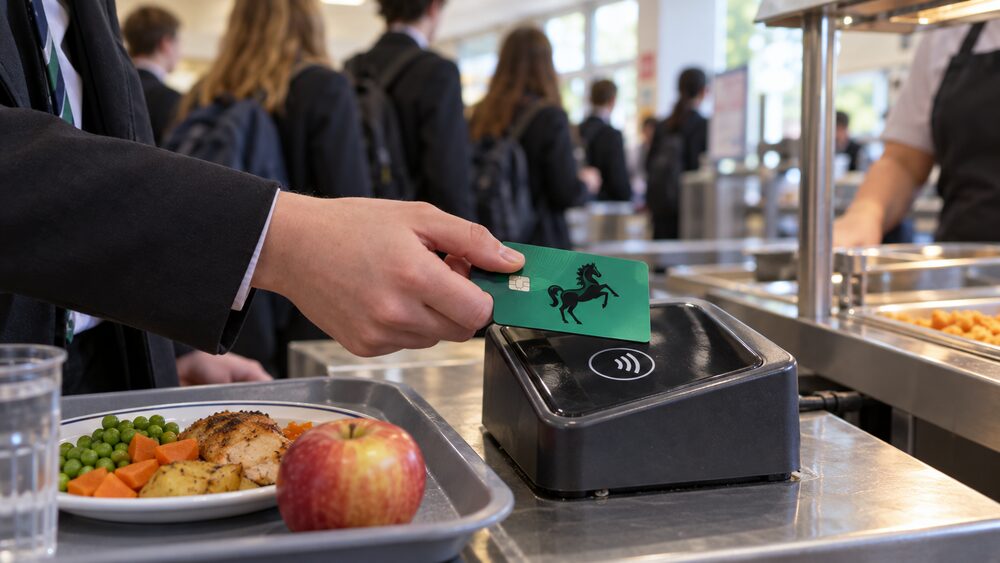
Lloyds Smart Start is a current account and savings account for children aged 11 to 15, opened and overseen by a parent or guardian. It is designed to give a young person a debit card and an account of their own while an adult keeps sight of what goes in and out. There are no monthly fees or charges, and no overdraft: if there is not enough money in the account for a purchase, the payment will not go through1.
The accounts stay open until the child turns 18. At that point the savings account changes to an adult Easy Saver and the spending account changes to an adult Classic Account, and the parental oversight that came with Smart Start is removed1. The child can hold only one spending account and one savings account1.
Interest applies to the savings account only, is variable and is paid monthly. The provider's own site carries today's figures, including the current interest rate and a worked example of what a balance could look like after 12 months1.
What Smart Start is and who it is for
Smart Start is a banking and savings account for 11 to 15 year olds with no monthly fees or charges2. It is one of a small group of accounts Lloyds offers for children and teenagers, sitting between the accounts aimed at younger children and the student accounts aimed at people leaving school4.
The account is opened by an adult, not by the child. The parent or guardian must be 18 or over, hold a Lloyds current account, be registered for online banking, be a UK resident and live at the same address as the child1. The child must be between 11 and 15 years old at the point of opening1.
The account is designed to be used by the young person day to day, with a debit card for spending, while the adult retains the ability to see and step in. That balance shifts as the child gets older: from age 13 the young person can remove the parental support in branch, or under 13 with parental consent1.
It is not a student account and it is not a full adult current account. It carries no overdraft, so it cannot put the child into debt, and it does not come with the switching incentives or packaged insurance that adult Lloyds accounts carry1.
How it works
Smart Start is two accounts in one arrangement: a spending account with a debit card, and a savings account. Interest applies to the savings account only, is variable and is paid monthly1.
Money can be paid in and taken out freely. There is no limit on withdrawals, and the young person can withdraw whenever there is money in the account3. A parent or guardian can withdraw only on behalf of the young adult where they believe the circumstances are an emergency1.
The savings account can be opened with as little as £13.
Parental oversight works through online banking and the app: a parent or guardian can view and transact on the accounts there1. That access is not permanent. It can be removed in branch from age 13, or under 13 with parental consent, and it is removed automatically after the child's 18th birthday1.
How the fees and charges work
There are no monthly fees or charges on Smart Start2. That is the whole of the account's own charging structure: no account fee, no charge for holding the account, and no overdraft to generate interest or unpaid-item charges, because there is no overdraft at all1.
Because there is no overdraft, a payment that would take the account below zero simply will not go through1. That removes the usual source of current account charges, which are interest and fees on borrowing, and it means the account cannot build up a debt that the child or the parent has to clear.
The savings side pays interest, which is variable and paid monthly1. The rate is not fixed and can change, so the amount earned moves with it. The provider's site carries the current rate and the current worked example1.
Where charges can arise is outside the account itself. If a parent or guardian also holds an adult Lloyds account, that account has its own fees and charges, and those are separate from Smart Start. The provider's site sets out the current figures for those accounts6.
Who can apply and how to apply
The application is made by the adult, not the child, and it is made online in the mobile app1. The child must be present during the application1.
To apply, the parent or guardian must:
- be 18 or over1
- hold a Lloyds current account1
- be registered for online banking1
- be a UK resident1
- live at the same address as the child1
The child must be aged 11 to 15 at the point of opening1. You will need to upload the child's ID, either a passport or a full UK birth certificate. If the child already has a Lloyds Young Saver or Child Saver account, that ID is not needed1.
Once open, the young person can hold only one spending account and one savings account1. The accounts remain open until the child turns 18, when the savings account changes to an adult Easy Saver and the spending account changes to an adult Classic Account1.
How your money is protected
Money held with Lloyds Bank is covered by the Financial Services Compensation Scheme.
Which licence covers a particular account depends on the sort code. If a Lloyds or Lloyds Bank account has a sort code starting with 30 or 77, the money is protected with Lloyds Bank plc. If it starts with 11, it is protected with Bank of Scotland plc8. Both are part of Lloyds Banking Group, and money held across brands under the same licence counts together towards a single limit8.
In practice a child's balance is unlikely to approach that figure, but the protection is the same as for an adult account.
The savings account pays variable interest, which means the rate can go up or down and the amount earned changes with it1. The provider's site carries the current rate.
Problems, complaints and getting help
If something goes wrong with a Lloyds account, the first step is to complain to Lloyds. If you are unhappy with how the complaint is handled, you can take it to the Financial Ombudsman Service, which is free to use. The ombudsman helps resolve complaints about issues such as account closures, disputed transactions, IT failures, and problems with switching services9.
Complaints about banking and payments are common. In the first quarter of 2026/27 the ombudsman opened 2,103 complaints about personal loans, 552 about debt collection, 271 about short term lending (instalment loans), 129 about store card accounts, 50 about payment instruments, and 27 about Help to Buy and Shared Equity Loans10.
For free, impartial help with money problems, MoneyHelper and Citizens Advice both offer support. If a complaint is about a business's practices rather than the account itself, Trading Standards through Citizens Advice handles those11.
Sources12 cited
- Smart Start Lloyds Bank, 2026-09-27
- Under 19s account Lloyds Bank, 2026-09-27
- Children's savings Lloyds Bank, 2026-09-27
- Kids and teens accounts Lloyds Bank, 2026-09-27
- Student accounts Lloyds Bank, 2026-09-27
- Switch to Lloyds Lloyds Bank, 2026-09-17
- Club Lloyds Lloyds Bank, 2026-12-09
- Financial Services Compensation Scheme Lloyds Bank, 2026-09-27
- Banking and payments complaints Financial Ombudsman Service, 2026-09-25
- Quarterly complaints data Q1 2026/27 Financial Ombudsman Service, 2026
- Nuisance calls Information Commissioner's Office, 2026-09-26
- Bank branch closures: is your local bank closing Which?, 2026





 MoneyHelperFree, impartial money and pensions guidance, set up by government
 FSCSProtects your money if a bank, insurer or investment firm fails
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales