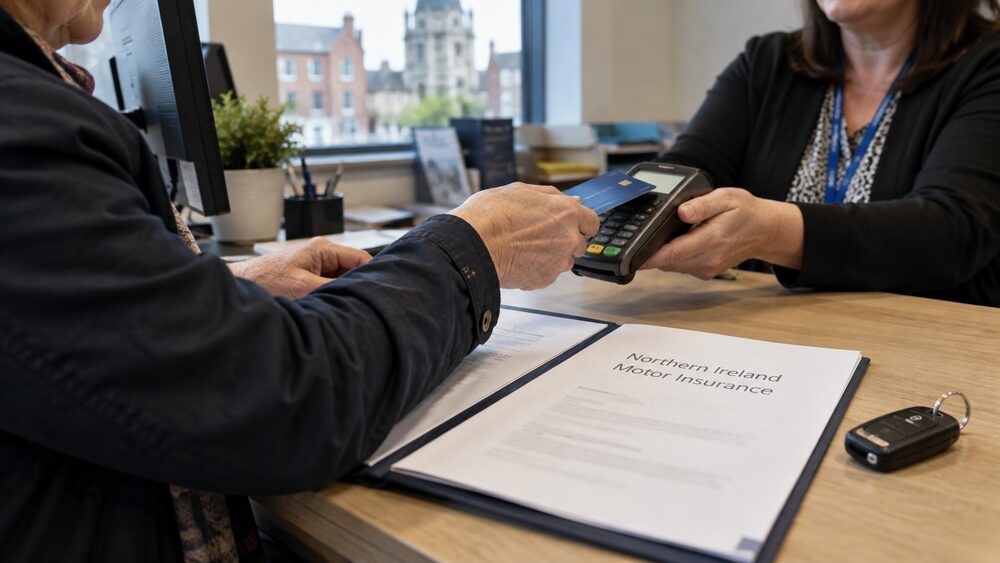
Car insurance works in much the same way in Northern Ireland as it does in England, Scotland and Wales: it is compulsory, it is sold by insurers and brokers, and it is regulated by the same UK authorities. Around nine in ten (89%) Northern Ireland consumers hold an insurance product of some kind, and motor cover is the most common type, held by 69% of those surveyed by the Consumer Council in June 20261.
What differs is the market around the policy. Some insurers treat Northern Ireland postcodes differently from the rest of the UK, and the region's own consumer body, the Consumer Council for Northern Ireland, has no statutory remit for insurance at all, so complaints go to the Financial Ombudsman Service rather than to a local body. In the first quarter of 2026/27 the ombudsman opened 4,096 complaints about car or motorcycle insurance2.
The legal basics are the same, with Northern Ireland's own regulations
The foundations of motor insurance law apply across the UK. The Consumer Insurance (Disclosure and Representations) Act 2012, which sets the rules on what a customer must tell an insurer and what happens if they get it wrong, extends to England and Wales, Scotland and Northern Ireland3. Northern Ireland also has its own statutory instruments covering motor insurance: the Motor Vehicles (Compulsory Insurance) Regulations (Northern Ireland) 2017 were made under section 2(2) of the European Communities Act 19724, sitting alongside the GB equivalents rather than being replaced by them.
The practical paperwork differs too. To tax a vehicle at a Post Office in Northern Ireland, you need more than in Great Britain: official guidance states you must also take a paper copy of an insurance certificate or cover note and an original MOT test certificate, or evidence of a Temporary Exemption Certificate5. Many people in Great Britain renew vehicle tax online without ever handling a paper insurance certificate; in Northern Ireland the paper versions still matter for Post Office transactions.
For the insurance itself, the same UK-wide rules on how premiums are calculated, the ban on price walking, renewals and paying monthly apply to Northern Ireland customers in the same way as to anyone else. The cancelling rights, excess rules and the duty to give accurate information, covered in misrepresentation, are also UK-wide. Where something is genuinely different, this page flags it.
Why some insurers do not cover Northern Ireland
Insurers choose which risks and postcodes they will quote, and Northern Ireland is not always included. The Consumer Council's June 2026 research found that one in twenty (5%) respondents had been refused an insurance product in the last year, and among those refused cover, 17% pointed to a change in the provider's policy regarding insuring homes in Northern Ireland1. That figure relates to home insurance, but it illustrates a pattern that affects other markets too: firms sometimes withdraw from the region as a whole rather than from individual risks.
Cost pressure is also visible in the same research. About one in seven (14%) respondents had stopped or cancelled an insurance product in the last year on account of the cost1. Motor cover, as the most widely held product, is often where households feel this most.
The legal backdrop is slightly different from Great Britain as well. Under the law that applies in Northern Ireland, providers of goods, facilities and services are not generally prohibited from discriminating on the grounds of age, although the law there has a similar effect overall6. This means an insurer's decisions about who it will cover, and on what terms, are governed by a framework that does not exactly mirror the one south of the border or in Great Britain.
Individual firms' positions vary and change. esure, for example, sells two levels of comprehensive car insurance, with features including windscreen cover, an uninsured driver promise, a legal advice helpline and a new car replacement benefit7. Its published product information does not state whether it quotes for Northern Ireland addresses, so the position should be checked with the insurer directly rather than assumed. Where a direct insurer will not quote, a broker can search firms that do cover the region: the trade-offs are set out in using a broker or buying direct and insurance broker or comparison website?.
Driving to the Republic of Ireland and breakdown cover
Northern Ireland's motor insurance rules were made in Northern Ireland-specific regulations under powers from the European Communities Act 19724, and the land border with the Republic of Ireland means cross-border driving is an everyday matter for many drivers rather than a foreign trip. Whether your policy covers driving in the Republic, and at what level of cover, depends on the policy itself: the detail is explained in does my car insurance cover me abroad? and do I need a Green Card to drive in Europe?.
Two things are worth checking before any cross-border journey. First, the level of cover abroad: policies commonly treat driving in the Republic differently from driving at home, and the difference matters if you have an accident south of the border. Second, breakdown cover: recovery policies have geographic limits, and a policy that covers the whole island is not the same as one that stops at the border. If a claim or injury does follow an accident, the time limits are covered in how long do I have to claim after a road accident?, and the whiplash reforms in Official Injury Claim apply to the GB system, so a Northern Ireland driver injured in England, Scotland or Wales is in a different position from one injured at home.
Credit unions in Northern Ireland cannot sell insurance
A common question from drivers looking for cover is whether their credit union can help. In Northern Ireland, it cannot. Credit unions there are prohibited from providing insurance, along with hire purchase agreements, conditional sale agreements and loans to other credit unions8. This is a legal prohibition, not a choice by individual credit unions: the services they may offer are set out in legislation, and insurance is not among them.
The reason lies in how the law has developed separately in the two parts of the UK. Credit union law is largely devolved in Northern Ireland, and many of the legal restrictions that have been relaxed for credit unions in Great Britain over the past twenty years have not been relaxed in Northern Ireland9. The contrast is stark: credit unions in Great Britain may offer insurance services, and credit unions in the Republic of Ireland may too, but in Northern Ireland they may not8. Northern Ireland credit unions also cannot offer mortgages or current accounts, and their loans to corporate members are limited to 10% of the outstanding balances on all loans made by the credit union to members8.
What credit unions in Northern Ireland do offer is basic financial services: share accounts, loans and life assurance10. There are around 170 credit unions in the region, and membership has historically been very high, with over 26% of the population being members at the time of an Assembly inquiry10. The Irish League of Credit Unions acts as a trade and representative body for 92 credit unions in Northern Ireland11. Unlike credit unions elsewhere, they have received no financial support from central or local government12. They are regulated, like their Great Britain counterparts, by the Financial Conduct Authority and the Prudential Regulation Authority8. For savings and borrowing, the credit unions guide covers how they work; for insurance, a Northern Ireland customer must go to an insurer or broker.
The Consumer Council: Northern Ireland's statutory consumer body
The Consumer Council is the statutory consumer representative body for Northern Ireland13. It is a non-departmental public body with a statutory duty to promote and safeguard the interests of consumers in Northern Ireland, operating under its sponsor department, the Department for the Economy, on behalf of the Northern Ireland Executive, and serving Northern Ireland's 1.9 million citizens14. Its website is www.consumercouncil.org.uk15.
Its statutory powers cover consumer affairs, energy, transport, water and sewerage, postal services and food affordability and accessibility1. These legal responsibilities are drawn from legislation, from licences given to companies working in Northern Ireland, and from cooperation agreements set in memorandums of understanding1. In practice, the Consumer Council has statutory powers to investigate complaints about energy, water, transport and postal services in Northern Ireland, and its complaint handling has returned money to consumers in cases ranging from airline refunds to fixing electricity billing issues16. Its powers over postal complaints are set out in legislation, which allows it to investigate a complaint that raises issues of general relevance concerning consumer matters relating to postal services in Northern Ireland17.
The Consumer Council also publishes research that is directly relevant to insurance buyers. Its June 2026 study of consumer experiences of motor and home insurance in Northern Ireland is the source of the figures on this page about how many people hold cover, are refused it, or cancel it because of cost1. Reading its research is free and does not require making a complaint.
Where the Consumer Council cannot help with insurance
The limit to know about is this: the Consumer Council does not have any statutory remit for insurance, and it does not take or investigate consumer complaints regarding insurance1. A driver in Belfast whose claim has been rejected cannot bring the matter to the Consumer Council in the way they could bring a water or sewerage complaint, which can be sent officially to the Consumer Council in Northern Ireland18.
That does not leave the consumer without local help, but the help available covers different ground. Consumerline provides free, independent support and advice for all consumers and businesses in Northern Ireland on behalf of the Trading Standards Service, helping people avoid scams, make a complaint and stay informed about consumer law19. Consumerline is for Northern Ireland consumers only20. It can help with general consumer law questions around a purchase, but an insurance dispute between a customer and an insurer is a financial services matter, which takes it outside both bodies' complaint-handling roles.
For the insurance-specific questions that arise most often, the site's dedicated pages cover the ground: why claims are rejected, what happens if your insurer goes bust, insurance fraud and ghost broking, and complaining about an insurer.
Complaints about car insurance: where to go instead
Because the Consumer Council has no insurance remit, the complaint route is the same as anywhere else in the UK. The first step is always to complain to the firm that sold or runs the policy, giving it the chance to respond; the deadlines it must meet are covered in how long does my insurer have to respond to a complaint?. If the firm's final response is unsatisfactory, or its deadline passes, the complaint goes to the Financial Ombudsman Service.
The volume of these complaints is substantial. In the first quarter of 2026/27 the ombudsman opened 4,096 complaints about car or motorcycle insurance, alongside 48 about caravan insurance and 38 about personal accident insurance2. Across 2025/26 it opened 4,451 complaints about travel insurance21, a reminder that the ombudsman handles the full range of insurance disputes, not just motor.
One extra wrinkle applies if a claims management company is involved, for example a firm offering to handle an injury claim after an accident. The risks of third-party capture after an accident are covered in what is third party capture?, and uninsured loss recovery explains motor legal protection.
Free help with money problems, debt and borrowing
Insurance costs are often the symptom of a wider money problem, and Northern Ireland has free sources of help that do not sell anything. Advice NI members provide free, confidential help and advice for anyone struggling to deal with money and debt, covering debt solutions including debt management plans, plus advice on benefits, housing, employment, tax and consumer rights11. Advice NI has offices throughout Northern Ireland, which you can visit or telephone22. Its Debt Service is free, offers confidential tailored debt advice, budgeting advice, solutions to deal with debt and negotiation with creditors on your behalf, and is available in each council area throughout Northern Ireland23.
Christians Against Poverty NI provides free debt help, Job Clubs, Life Skills groups and CAP Money courses, and can set up a debt management plan and walk people through insolvency options11. For general consumer questions and scams, Consumerline offers free, independent advice for Northern Ireland consumers19.
Support also exists at government level. Finance Support is a service for Northern Ireland24. For those whose debts have become unmanageable, the Northern Ireland Debt Relief schemes have eligibility limits: individuals can only access the schemes if their total debt, total assets, the value of any vehicle they have for domestic use, and their surplus monthly income are below prescribed amounts25. The full range of options is set out in the debt guide, and the scams and fraud guide covers the fraud side of insurance, including ghost brokers who sell worthless policies.
Protection that applies in Northern Ireland
The key consumer protections in insurance are UK-wide and do apply in Northern Ireland. The Consumer Insurance (Disclosure and Representations) Act 2012 extends to England and Wales, Scotland and Northern Ireland, apart from section 11(3), which covers England and Wales and Scotland only, and section 11(4), which extends to Northern Ireland only3. The Act's rules cannot be waived by an insurer: the draft legislation made clear that no contracting out is permitted26. What this means in practice is that the duty to answer an insurer's questions honestly, and the remedies an insurer has if you do not, work the same way in Belfast as in Birmingham, and the detail is in giving wrong information to an insurer.
The wider consumer protection framework is devolved. Consumer protection and its enforcement is a transferred matter in Northern Ireland, meaning provisions in the relevant Act's Parts 3, 4 and 5 are within the legislative competence of the Northern Ireland Assembly27. Enforcement roles are filled locally: under the Consumer Rights Act 2015, the regulator for these purposes includes the Department of Enterprise, Trade and Investment in Northern Ireland28, and enforcement of the Consumer Protection Act 1987 in Northern Ireland is likewise the responsibility of the Department of Enterprise, Trade and Investment29. The Financial Conduct Authority regulates insurers and credit unions across the UK, including in Northern Ireland8.
The principle that consumers in Northern Ireland should receive the same level of protection as consumers in Great Britain was raised by a consumer body during the Confirmation of Payee policy process, reflecting a recurring theme in Northern Ireland consumer policy: the market is sometimes smaller and less competitive, but the protections should not be thinner30. If an insurer fails, the position is the same as elsewhere in the UK and is covered in what happens if your insurer goes bust. For an overview of all the bodies that protect UK financial consumers, see consumer protection in UK financial services, and for how the rules differ across the nations, money in Scotland, Wales and Northern Ireland.
Sources30 cited
- Consumer experiences of motor and home insurance in Northern Ireland Consumer Council for Northern Ireland, June 2026
- Quarterly complaints data Q1 2026/27 Financial Ombudsman Service, 2026
- Consumer Insurance (Disclosure and Representations) Act 2012, extent provisions legislation.gov.uk, 2012
- The Motor Vehicles (Compulsory Insurance) Regulations (Northern Ireland) 2017 legislation.gov.uk, 2017
- Vehicle tax GOV.UK, 2026
- Age discrimination law and Northern Ireland House of Commons Library, 2026
- esure car insurance esure, 2026
- Credit union regulation and services in Northern Ireland Northern Ireland Assembly, 2025
- Credit unions: devolved law and territorial differences House of Commons Library, 2026
- Inquiry into credit union regulation, services, funding and recommendations Northern Ireland Assembly, 2007
- Help and advice on illegal lending and personal finances Consumer Council for Northern Ireland, 2026
- Credit union research Welsh Government, 2009
- Banking to Borrowing Consumer Council for Northern Ireland, 2026
- Impact of bank branch closure research report Consumer Council for Northern Ireland, 2026
- Consumer Council Cost of the Basics report Consumer Council for Northern Ireland, 2024
- The Consumer Council's complaint handling process Consumer Council for Northern Ireland, 2026
- Postal Services Act, General Consumer Council for Northern Ireland provisions legislation.gov.uk, 2007
- Make a complaint to the NI Consumer Council nidirect, 2025
- Consumer Council help and advice on illegal lending Consumer Council for Northern Ireland, 2026
- Contact Consumerline to make a complaint or ask advice nidirect, 2026
- Annual complaints data and insight 2025/26 Financial Ombudsman Service, 2025
- Getting information and help about pensions nidirect, 2026
- Advice NI money and debt service Advice NI, 2026
- Finance Support introduction Department for Communities, 2016
- Proposed increases to monetary eligibility limits for Debt Relief Orders in Northern Ireland Department for the Economy, 2024
- Draft Consumer Insurance Bill, report on no contracting out Scottish Law Commission, 2009
- Digital Markets, Competition and Consumers Act 2024 legislation.gov.uk, 2024
- Consumer Rights Act 2015, Schedule 3 legislation.gov.uk, 2015
- Enforcement of the Consumer Protection Act 1987 in Northern Ireland legislation.gov.uk, 2005
- Extending Confirmation of Payee coverage Payment Systems Regulator, 2022






 MoneyHelperFree, impartial money and pensions guidance, set up by government
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 FSCSProtects your money if a bank, insurer or investment firm fails
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales
 GOV.UKOfficial information on tax, benefits and government services