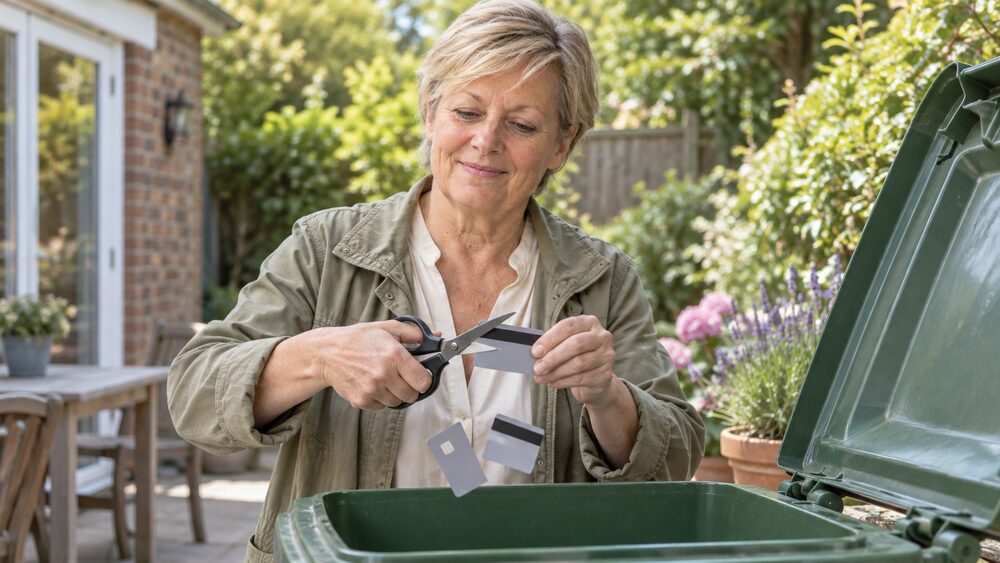
Closing a credit card stops you spending on it. It does not stop the debt. If you owe money on the card when you close it, the balance remains payable, you must keep up at least the minimum payments, and interest continues at the same standard rate or rates you pay now1. What closure removes is the ability to borrow more, for you and for anyone else named on the account.
The law is on your side when it comes to timing. Under the rules governing open-ended credit agreements such as credit cards, store cards and payday loans, a consumer can terminate the agreement at any time, with a maximum of one month's notice2. A card provider cannot trap you into keeping a card you no longer want, although it can require you to clear what you owe under the terms you signed up to.
Closing a card is usually straightforward: most providers let you do it in an app, online, by phone or by post. The parts people most often get wrong are the ones around the edges: regular payments attached to the card, a Direct Debit that collects the bill, interest that lands after the final payment, and what the closure does to a credit file. This page walks through each of those in order.
Closing a card ends spending, not the debt
The first thing to understand about closure is what it does and does not achieve. StepChange's guidance on paying off credit card debt makes the point plainly: the first step is to stop using the card you want to pay off, because then the amount you owe stops growing and becomes quicker to repay7. Closing the account is the strongest version of that step: the card stops working, so no new spending can be added.
But the balance is a separate matter. A card can be cancelled with an outstanding balance, and the cardholder will still need to pay it off, making at least the minimum payments, at the same standard interest rate or rates as before1. Closing does not trigger a demand for the full balance immediately, and it does not change the interest rate. It simply freezes the account for spending while the debt runs down under its existing terms.
That is why closure and repayment are often done together. Paying a credit card off in full can save money in interest and charges7, and debt charities advise destroying the card so it cannot be used again once you have cleared it or moved the debt elsewhere8. If you have moved a balance to another card, the guide to closing old accounts after a balance transfer covers whether shutting the old account is the right move for your credit file.
If the debt is the reason you are closing, free help exists before you act. StepChange, National Debtline and Citizens Advice all publish guidance on the options, from balance transfer and consolidation loans to informal arrangements, and the page on help with credit card debt sets them out.
How to close a credit card: app, online, phone or post
Providers offer several routes, and the mechanics are similar across the market. TSB, for example, lets a customer close a credit card in its mobile banking app: select the credit card, tap "Manage" and choose "Close credit card"1. Other issuers take closure requests online, by phone or by post, and some ask for the request in writing. Whichever channel you use, ask for written confirmation that the account has been closed and note the date you asked.
Your right to close is set in law rather than in the provider's goodwill. The rules on open-ended credit agreements, which cover credit cards, store cards and payday loans, let a consumer terminate at any time with a maximum of one month's notice2. In practice most providers close accounts faster than that, but a month is the longest a provider can insist you wait.
There are two situations where closure comes with extra rights:
- After a change to your terms. If the provider changes the terms and conditions, the account can be closed at any time up to 60 days from the day you were told about the changes, without giving notice or paying extra charges9.
- After a rate rise. The rules give 60 days to reject an interest rate increase, cancel the card and pay back what is owed at the old rate4. The Financial Conduct Authority's rulebook requires a firm proposing a rate increase on a credit or store card to permit the customer sixty days, from the date of the firm's notice, to give notice requiring it to close the account10. The page on rejecting an interest rate rise covers this in detail.
Before you make the request, it is worth working through the steps below, because several of them are easier to do while the account is still open.
Before you close: regular payments, digital wallets and Direct Debits
This is the step that causes the most trouble after closure. Subscriptions, gym memberships, streaming services and similar regular payments are usually taken as recurring card payments, sometimes called continuous payment authorities. These are tied to the card, not to a bank account, and they do not move automatically when a card closes.
To cancel a recurring card payment, you can contact either the business taking the payment or your card provider11. The Financial Conduct Authority is clear about where the duty sits: once you have asked your card issuer to cancel, the issuer must stop the payments, even if you have not contacted the business11. There is also a deadline to know: you must ask your card issuer or the business to cancel by the end of the business day before your next payment is due to be taken11.
You do not have to wait on the phone either. Citizens Advice advises that to withdraw consent for a future payment, you simply tell whoever issued your card, the bank, building society or credit card company, that you do not want the payment made, by phone, email or letter12. Business Debtline adds that you may need to write to your card issuer asking for the payment to be stopped, and provides a sample letter13. The Financial Ombudsman Service, which handles complaints about regular payments, says the same: contact either the business or your card provider14.
Direct Debits work differently, and the distinction matters. A Direct Debit is an instruction on a bank account, and one can be cancelled at any time by contacting your bank or building society, which may ask for written confirmation; the organisation concerned can also be notified15. Once a Direct Debit is cancelled, your bank should ensure that no further payments are taken, whether or not you owe the company money15.
Two practical points before closure:
- Direct Debits paying your bills. If any household bills were being paid from the credit card, move them to another payment method before closing. Debt charities advise continuing to pay what you can afford and only cancelling a payment if taking it would cause more difficulty, such as pushing you into unarranged overdraft13.
- The Direct Debit paying your card bill. If a Direct Debit collects your credit card repayments and the card still has a balance, leave it in place until the debt is cleared. Cancelling it does not cancel the debt, and missing a credit card payment can cost you in charges and credit file marks.
Digital wallets need a mention too. If the card is saved in a phone wallet or another device, the closure will stop it working there as well: a suspended or closed card will no longer work and no further borrowing is possible on the account16. Remove the card from your wallets so you are not left with a declined payment at a till.
Paying off the balance, including residual interest
If you close with a zero balance, this section is simple. If you do not, the balance continues under the account's existing terms. TSB's terms are typical of the market: you can cancel your credit card with an outstanding balance, but you will still need to pay it off, making at least the minimum payments, at the same standard interest rate or rates you have now1.
The cheapest way to finish a card is to clear the whole balance by the due date. If you pay off the whole amount owed on the card by the due date, you will not be charged interest on your purchases17. Pay less than the full balance and interest continues to run on what remains, which is why the final months of a card can still cost money even though no new spending is possible. The guide to how credit card interest is charged explains how this works.
If the balance is large relative to your payments, be aware of the persistent debt rules. Where a card has been in persistent debt, the options include increasing monthly repayments, repaying the balance using credit at a lower interest rate, cancelling the card and moving the balance to a different one with lower interest, or getting a loan you can afford to repay18. The pages on persistent debt rules and paying off debt faster set these out.
One trap worth naming: closing the card does not switch off a rate rise already in the pipeline. If the provider has raised, or proposed raising, your interest rate, the rules give 60 days to reject the hike, cancel the card and pay back what is owed at the old rate4. The FCA's rulebook requires firms to give customers this sixty-day window from the date of the notice of a proposed increase to require the account to be closed10. Rules introduced in 2011 gave customers the same choice: a customer who does not accept a rate hike can close the credit account and pay off what is left in instalments at the current interest rate19. Where a rate rise is the reason for closing, the old rate is preserved for the remaining balance when the account is closed under these rules.
Refunds and disputes after closing
Closing a card does not end your rights over payments you made with it. If something goes wrong with a purchase, or money is owed back to you, there are routes to recover it even after the account has shut.
The first is chargeback. Some banks and credit card companies offer a chargeback service, which means they will reverse a transaction and return your money unless the seller can successfully dispute it20. More generally, if you pay by credit or debit card, you might be able to get your money back through your card provider if something goes wrong21. The guide to chargeback explains how to make a claim.
The second is Section 75 of the Consumer Credit Act, the statutory protection that makes the card provider jointly liable with the seller for purchases between certain amounts. This applies to credit card payments, including in cases of fraud: if you fall for a scam and pay by credit card, you can usually reverse the payment and recover your funds under Section 7522. The pages on Section 75 protection and how to make a Section 75 claim cover the thresholds and the process.
If the card itself is in credit, in other words the provider owes you money, perhaps from a refund arriving after a final payment, ask the provider how it will return it. A closed account cannot receive spending, but the provider still holds your money and can transfer it to you. Keep your closure confirmation until every refund and dispute is settled.
What happens after closure: statements, confirmation and card disposal
Once the provider processes the closure, expect three things: confirmation, access to history, and a card that needs destroying.
On statements, you have a right to your transaction history for up to five years after you have closed your account, under rules that apply to payment accounts3. That means closure does not wipe the record of what you spent, which matters for tax records, warranty claims and disputes. Even so, it is simpler to download the statements you might need before you close, while access is still one tap away. The guide to reading your credit card statement shows what to look for.
On confirmation, providers can be asked for written notice that the account is closed and, if there is a remaining balance, a statement of what is left and the repayment schedule. If a debt has been settled with the provider, National Debtline's guidance on settlement offers describes what appears on your credit reference file: the account showing as closed, and the balance changed to zero23.
On the card itself, destroy it properly. Take Five's anti-fraud advice is to cut through the chip and dispose of the sections in separate bin bags5. Citizens Advice similarly advises returning unused cards cut into pieces when changing accounts9. A whole card in a bin is a fraud risk; a shredded one is not.
How closing affects your credit file
Closure is reported to the credit reference agencies, and it stays on your record. A settled or closed account shows on your file as closed, with the balance at zero23. How long the information takes to appear or be corrected varies: a correction to a credit file can take up to 30 days, and timings differ depending on which credit reference agency you use to view your file6.
Does closing a card help or harm your credit file? The honest answer is that it depends on your circumstances, and the effect is usually modest. What closure does is remove the card's available credit from the total credit you have access to, and it ends the account's history at the date of closure. Which? 's guidance following a credit limit reduction makes a related point worth remembering: before acting on a card, check your credit history for errors, contact the issuer if something looks wrong, and do not immediately cancel the card, because closure is not always the answer to a change the provider has made24. The guide to how credit cards affect your credit file covers the mechanics.
One situation needs a separate step. Closing a joint account will not remove the link to the other person from your credit file; if there is no other financial connection, a "notice of disassociation" can be requested from the credit reference agencies25. That rule is about joint accounts, but the principle is worth knowing: closure ends the account, not every trace of it.
When a closed or suspended card cannot be used again
A closed account is closed for everyone on it. If your account is suspended, you will not be able to borrow any more money, and if you have a credit or store card, the card will no longer work16. The same applies once an account is closed at your request: no spending, no cash withdrawals, no additional borrowing for any cardholder.
Additional cardholders have a specific position worth knowing. Card companies can only enforce payment against the original account holder, and not a named secondary cardholder, and the account cannot be closed by the secondary cardholder26. In other words, the person who took out the card is the person who owes the money and the only person who can close the account. The guide to additional cardholders and third party access covers this in full.
There is no right to reopen a closed account. Once the provider has closed it, the account shows as closed on your credit file23 and any future credit from that provider is a fresh application, assessed on its own terms. If you closed the card in error, or your circumstances change, the route back is applying for a new credit card, not resurrecting the old one.
When the card provider closes or suspends your card
Providers can close or suspend cards too, and the rules constrain how they do it. The FCA's expectations for firms state that a firm should only suspend or cancel a customer's credit card where this is objectively justified27. A provider cannot simply shut a card on a whim.
The main trigger is persistent debt. A lender could suspend your card if you are in persistent debt for 36 months or more, and lenders only suspend cards as a last resort; they are more likely to do it if you ignore them or do not attempt to increase your payments28. The FCA's rules go further: where a customer does not respond to a firm's request about persistent debt, the firm must, at the end of the period specified in the request, suspend or cancel the customer's use of the credit card, and the same applies where the customer confirms the options are sustainable but states they will not make the increased payments29. In November 2024 the FCA updated its guidance in this area, reminding firms of their obligations when suspending or cancelling credit card use10.
If the provider closes the account rather than suspending the card, notice rules apply to bank accounts: banks must provide at least 90 days' notice before terminating an account and give a clear reason for the action, for accounts opened on or after 28 April 202630. Credit card closures by the provider are handled under the card agreement's own terms, but the direction of travel is the same: providers are expected to explain themselves.
If your card is suspended or closed by the provider and you cannot afford the higher payments being asked for, you have options. The page on forbearance rights when you cannot pay more explains what firms must consider, and free debt advice is available from StepChange, National Debtline and Citizens Advice.
Complaints if closing goes wrong
If the provider will not close the account, keeps taking payments you cancelled, or mishandles the closure, you can complain. Start with the provider itself: set out what happened, what you asked for and when, and what you want done. Give it a chance to put things right.
If the provider does not resolve the matter, or eight weeks pass without a satisfactory answer, the Financial Ombudsman Service can look at it. The ombudsman deals with complaints about regular payments, including cases where a payment was taken after a cancellation request14, and it can order a firm to refund money and put things right. The service is free to use. The guide to complaining about a credit card provider walks through the process step by step.
For problems with debt rather than with the provider's conduct, free and impartial help is available from StepChange and National Debtline, and the debt section of this site explains the full range of options, including where the rules differ in Scotland and Northern Ireland.
Sources30 cited
- TSB: closing your account TSB, 2026
- The Consumer Credit (EU Directive) Regulations 2010 legislation.gov.uk, 2010
- How to open a bank account online Which?, 2026
- Credit card interest explained Which?, 2026
- Protecting yourself from card fraud Take Five, 2026
- How does debt affect a credit file? StepChange, 2026
- Paying off credit card debt StepChange, 2026
- Consolidating credit card debt StepChange, 2026
- Getting a bank account Citizens Advice Scotland, 2026
- CONC 6.7: credit card and store card firms Financial Conduct Authority, 2024
- Recurring card payments Financial Conduct Authority, 2025
- Stopping a future payment on your debit or credit card Citizens Advice, 2023
- Making the most of your money Business Debtline, 2026
- Regular payments: complaints we can help with Financial Ombudsman Service, 2026
- Direct debits and standing orders explained Which?, 2026
- Persistent debt Business Debtline, 2026
- The costs and charges of credit cards Citizens Advice, 2026
- Dealing with persistent debt StepChange, 2026
- New rules to speed up payment of credit card debts Which?, 2011
- Section 75 and chargeback Which? Legal, 2026
- Before you get work done on your home Citizens Advice Scotland, 2026
- Victims tricked into transferring scammers' money granted better protection Which?, 2018
- Full and final settlement offers National Debtline, 2026
- Ask an expert: can the bank just reduce my credit limit? Which?, 2017
- Joint accounts MoneyHelper, 2026
- Six steps to financially separate from your ex Which?, 2023
- Persistent credit card debt: our expectations of firms Financial Conduct Authority, 2020
- Persistent credit card debt StepChange, 2026
- PS18/04: persistent credit card debt Financial Conduct Authority, 2018
- Bank account closures: research briefing CBP-8574 House of Commons Library, 2026



 MoneyHelperFree, impartial money and pensions guidance, set up by government
 StepChangeFree debt advice and solutions from a charity
 National DebtlineFree debt advice by phone, webchat and online
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales