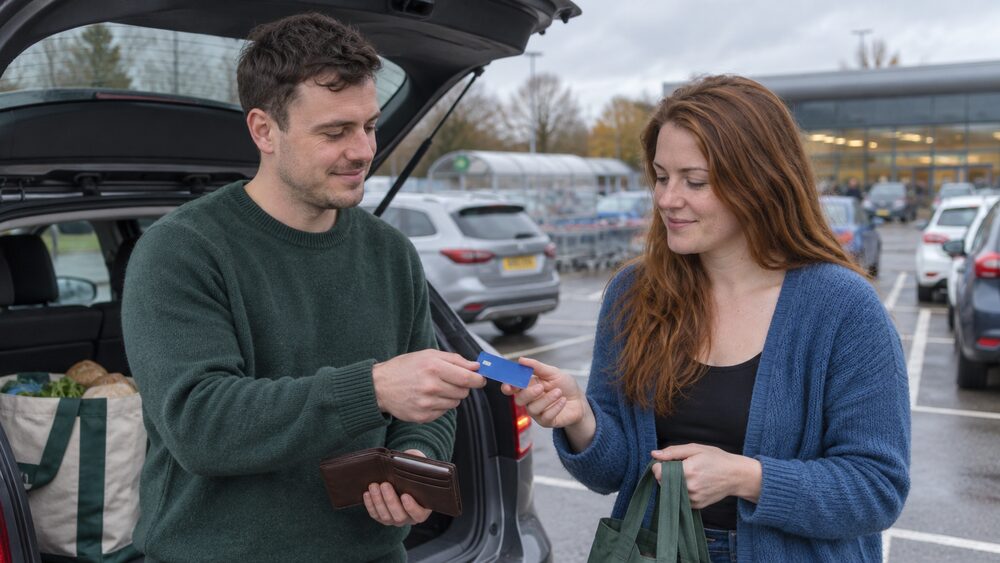
A credit card can only ever be in one person's name, but most providers will let the account holder add other people to it. An additional cardholder gets their own card with their name on it, linked to the main account, and can spend on it in the same way as the main cardholder. They share the account's credit limit, but they have no legal responsibility to pay the debt: the main cardholder is responsible for paying off the credit card debt in full, including everything an additional cardholder spends1. There are no joint credit cards in the UK, so this arrangement, not a joint account, is the only way two people can spend on one credit card account2.
Adding someone is usually quick. Tesco Bank, for example, lets customers add an additional cardholder over the phone by calling its credit cards team3. Providers differ in the details, including minimum ages and what the additional cardholder is allowed to do on the account, so the account holder should check with their own provider first.
What an additional cardholder is and what they can do
An additional cardholder is someone the main cardholder has asked the provider to add to their credit card account. The additional cardholder receives a physical card in their own name and can spend on it up to the account's shared credit limit. They do not have their own account, their own limit or their own agreement with the lender. Citizens Advice puts the position plainly: if you add someone as an additional cardholder, "you are responsible for paying off whatever they spend on your card"8.
What an additional cardholder can actually do on the account varies by provider, and the permissions can be surprisingly broad. Tesco Bank describes an "Additional Card Holder with Authority to Divulge" who can make a payment, check the statement balance, check the due date for payment, check the minimum payment amount, get the current balance and discuss transactions, as well as change account details, request a card for themselves and report both cards as lost or stolen3. Not every provider gives additional cardholders that much access to account information, and some restrict them to spending only. The account holder sets the arrangement up, so it is worth asking the provider exactly what the additional cardholder will be able to see and do.
Age matters too. Credit cards are products for people aged 18 or older, and that applies to additional cardholders as well as main cardholders5. Providers run identity checks on additional cardholders before issuing their card.
There can be practical upsides for the household. On Halifax's cashback offers scheme, for example, spending by additional cardholders helps generate offers and earn cashback, although only the main cardholder activates offers and receives the cashback9. Rewards, points and cashback on a card almost always belong to the main cardholder, because the account and the agreement with the lender are theirs.
Credit cards cannot be joint: only the main cardholder is liable
This is the single most important thing to understand about additional cardholders. Credit cards cannot be taken out in joint names2. A credit card account is always in one person's name, and that person, sometimes called the primary or main cardholder, is responsible for repaying all debts on the account, even debt run up by an additional authorised cardholder2.
The consequences run in one direction only. National Debtline confirms that a credit card "won't be in joint names. Only one person will be liable for the credit card debt"4. StepChange states the same in blunt terms: "There is no such thing as joint credit card debt here. Credit card accounts can only be in one name"10. Shelter Cymru adds that if only one of you signed a credit card agreement, the debt does not belong to the other person, even if they are an additional cardholder11. Independent Age summarises the position after a separation: for loans or credit card bills, "you will only be liable for joint debts or those that are in your name"12.
This contrasts sharply with joint bank accounts, where two or more people can receive payments, pay by debit card, transfer money and manage the account, and where each account holder is normally liable for the whole of any overdraft13. A couple moving their money to a joint current account gets shared responsibility; a couple sharing a credit card does not.
The enforcement point follows from all this: card companies can only enforce payment against the original account holder, not a named secondary cardholder, and the secondary cardholder cannot close the account either14. The additional cardholder cannot pay the debt off and close the account, cannot ask for a credit limit change to be enforced, and cannot be pursued for the balance.
One related trap concerns payment protection insurance. The Financial Ombudsman Service's approach to PPI complaints notes that credit card PPI policies "only provide cover for the credit card account holder(s). They do not provide any cover for an additional card holder"15. If the main cardholder has PPI on the card, it protects their ability to pay, not the additional cardholder's.
The rule also matters after death. NI direct guidance on debts when someone dies explains that repayment of card debts must wait until other debts have been settled, and that if cards are held jointly, any debts will be the joint holder's responsibility14. Since credit cards cannot be held jointly, a card balance after death is a debt of the person who held the account, dealt with by their estate, not by the additional cardholder.
No financial link on your credit file
Many people assume that adding a partner as an additional cardholder ties your credit files together. It does not. National Debtline is explicit: "Credit cards do not form a financial link with someone, even if they are an additional cardholder"4. The account appears on the main cardholder's credit file; the additional cardholder's file shows nothing about it.
This is very different from a joint bank account or joint loan, which does create a financial association that lenders can see. MoneyHelper guidance on joint accounts warns of the reverse problem: closing a joint account will not remove the link to the other person from your credit file, and a "notice of disassociation" can be requested from credit reference agencies if there is no other financial connection13. Business Debtline adds that credit reference agencies should not include information about other people who happen to live with you, even if you share a surname, unless a financial connection has been created16.
The practical points cut both ways:
- For the additional cardholder: the account does not help you build a credit history. Your spending on someone else's card is invisible to lenders assessing you, because there is no agreement between you and the card company.
- For the main cardholder: the additional cardholder's own credit problems do not appear on your file either. What does appear is how the account as a whole is managed, including their spending.
- For finding out who you owe: not every firm you owe money to appears on your credit file at all. StepChange notes that some creditors, such as utility providers and insurance companies, do not have to add information to your credit file17.
If a couple wants each person to build their own credit history, each person needs their own credit agreement. A credit-builder card in one person's own name does that; an additional card does not. The wider picture is on how credit cards affect your credit file.
Fees and charges on additional cards
Most providers do not charge a fee simply for adding an additional cardholder, but the spending that follows is charged exactly like the main cardholder's spending, and it all lands on one bill. Citizens Advice advises checking the credit agreement for what other charges apply to the card, noting you will usually be charged for going over your credit limit, for using the card abroad and for late payments8. Some cards also charge an annual fee for use of the card, which is added to the amount due8.
Because both cardholders share one credit limit, additional cardholders make it easier to go over it. If you go over your credit limit, the provider may charge a fee18, and on cards aimed at people rebuilding their credit, charges and interest can be added if you go over the limit, which makes it harder to get further credit in future19.
The charges that follow are the standard card charges, and they apply to the whole account:
| Charge | What happens |
|---|---|
| Late payment | A charge for missing a repayment; charges of more than £12 may be seen as unfair20 |
| Over the limit | The provider may charge a fee for exceeding the credit limit18 |
| Cash withdrawals | Interest from the day you took the money out, plus a cash handling fee of around 2% of the amount you withdraw21 |
| Using the card abroad | Most credit card companies charge a commission charge when you use the card abroad20 |
| Balance transfers | A handling fee of around 2% of the balance if you move a balance to another card21 |
Interest works the same way regardless of who spent the money. If you pay off the whole balance owed by the due date, you will not be charged interest on your purchases20. If you do not pay back all that you owe when payment is due, you may be charged interest22, and cash transactions will always charge interest, from the day the money was taken out23. The interest rate for cash advances is usually higher than the rate for purchases21.
The main cardholder should also watch minimum payments. If you do not pay off the balance each month, you will be asked to repay a minimum amount, typically around 3% of the balance due or £5, whichever is higher8, and the most expensive debt on the card is always paid off first20. With two people spending on one shared limit, the balance can grow quickly, and the minimum payments page explains how long paying only the minimum can take to clear a debt.
Third party authority: letting someone manage the account for you
An additional cardholder is not the only way someone else can be involved with a credit card account. A person can also be given authority to manage the account without getting a card of their own. This matters most for people who cannot manage their own money, temporarily or permanently, because of illness, disability, hospitalisation or something similar.
There are two main routes. The first is a third party mandate. NI direct's guidance on dementia and managing money describes it as something you can "set up a third-party mandate, this gives someone else access to your bank account, you can specify how much access to give"24. Scope describes the same document as "a document telling your bank that someone you trust is allowed to run your personal accounts"25. GOV.UK notes that most banks, building societies or other account providers allow a third party access to your account, for example with a second card26. A mandate is usually used where the account holder still has mental capacity and can sign the authority themselves.
The second route is a power of attorney, used when the account holder cannot manage the account or has lost capacity. A power of attorney is a bigger legal step than a mandate, and the card provider will need to see it and register it before the attorney can act. Providers handle this differently, so the person acting for the account holder should contact the card company with the document and ask what the provider needs.
Card providers also offer their own in-house versions of third party access. Tesco Bank lets a customer add a third party with what it calls "Authority to Divulge", which allows that person to discuss the account with the provider on the main cardholder's behalf3. This is lighter than a mandate or a power of attorney: it lets someone make enquiries and help manage the account, but it does not give them a card or make them responsible for anything.
Do not confuse any of these with two other things that carry similar names. A "third party debt order" is something a creditor uses against you: it lets a creditor take money that you are owed by someone else from your bank account27. And a recurring card payment, also known as a continuous payment authority, is set up by a company using your debit or credit card details rather than your current account details28. Neither has anything to do with giving a trusted person access.
Three different levels of access, from a card of your own to running the whole account.
What a third party can and cannot do on your card
A third party's powers are narrower than an additional cardholder's in one way and broader in another. They can discuss the account and help manage it, but they do not get a card and cannot spend on the account.
Tesco Bank's support pages set out the limits of its third party arrangement. A third party with Authority to Divulge cannot change account details, cannot request a card for themselves, and cannot report both cards as lost or stolen3. Those actions stay with the main cardholder, or with someone holding a formal power of attorney where the provider has accepted it.
The liability position for third parties mirrors the additional cardholder position. Citizens Advice confirms that if you were an authorised additional cardholder on someone else's credit card account, for example a spouse or partner, the credit card company cannot ask you to repay any debts on the card30. The same logic applies to someone with third party authority: they act on the account holder's behalf, but the debt never becomes theirs.
In practice, the dividing line looks like this:
| Additional cardholder | Third party with authority | |
|---|---|---|
| Gets a card in their own name | Yes | No |
| Can spend on the account | Yes, within the shared limit | No |
| Can discuss the account with the provider | Yes, if given authority | Yes |
| Can change account details | Depends on provider | No |
| Liable for the debt | No | No |
How to add or remove an additional cardholder or third party
Adding an additional cardholder is done by the main cardholder, not by the person being added. At Tesco Bank, you can add an additional cardholder over the phone when you call the credit cards team3. Other providers offer the same through their apps or online banking. The main cardholder will need the additional cardholder's personal details, and the provider will run its own checks before issuing the card.
Removing people is also the main cardholder's action, and it is an important one. Surviving Economic Abuse's guidance for financial services firms notes that where an abuser is named as a secondary cardholder on the victim-survivor's account, the victim-survivor can ask for the abuser to be removed as a secondary cardholder, and can also remove their own name as a secondary cardholder on the abuser's credit card31. Its guidance for individuals separating their finances from an abuser makes the same point: a credit card is never jointly held with someone, it is always in one person's name, so the person whose name it is in controls who is on it32.
The steps, in order:
- The main cardholder contacts the card provider, by phone, app or online banking.
- They ask for the additional cardholder or third party to be removed.
- The provider cancels the additional card and confirms the removal.
- The main cardholder destroys the cancelled card, and checks that no recurring card payments set up on it need moving28.
If the relationship has ended, the same rule works from the other direction: because the card company can only enforce payment against the original account holder, removing a secondary cardholder does not shift any liability, it simply stops further spending14. The main cardholder may also want to check for continuous payment authorities still running on the card.
Where things can go wrong: overspending, missed payments and fraud
The biggest risk of an additional cardholder is the simplest one: two people spending on one limit, with one person liable for all of it. The main cardholder is responsible for paying off the credit card debt in full1, including spending they did not make and may not have known about. If the balance is not cleared each month, interest is charged, and if you do not pay off the full amount every month on a credit card, you will be charged interest on the whole lot, not just the unpaid amount5.
Missed payments damage the main cardholder's credit file, not the additional cardholder's. Charges of more than £12 for missing a credit card repayment may be seen as unfair20, but a charge within that level is standard, and the missed payment itself is recorded. The missed payments page covers the consequences in detail.
Fraud is a live risk on any card, and the National Crime Agency reports that some fraud types, such as card-not-present fraud, are increasing33. With two cards in circulation, the main cardholder should watch for the signs of identity theft NI direct lists: unusual payments or direct debits appearing on your bank statements, important mail going missing, bills arriving for things you have not bought, and new credit cards appearing on your credit record34. A card being used by someone else in the household can also mask unauthorised use, because it is hard to tell authorised additional cardholder spending from fraud.
Cash withdrawals deserve a special warning. Cash transactions will always charge interest, from the day the money was taken out23, and the interest rate for cash advances is usually higher than the rate for purchases21. An additional cardholder withdrawing cash can therefore start a clock the main cardholder does not know about.
Death and default end the arrangement. TSB's bereavement guidance states that if the deceased was an additional cardholder on somebody else's credit card, the bank will cancel that card, and it gives guidance on clearing any balance on accounts the deceased held35. An additional cardholder whose main cardholder has died should expect the card to stop working, and should not expect to be pursued for the balance, because the debt was never theirs30.
Section 75 and other protections on purchases
Purchases made on a credit card benefit from Section 75 of the Consumer Credit Act. Which? explains that this additional protection applies to credit card purchases, not debit card purchases, and covers purchases costing more than £100 and up to £30,0006. If the seller goes bust, delivers faulty goods or does not deliver at all, the card company can be liable alongside the seller.
Purchases made by an additional cardholder are covered too. The protection attaches to the credit card agreement, and the agreement belongs to the main cardholder, so a claim under Section 75 for something an additional cardholder bought is made by the main cardholder against the card company. The same protection applies to newer forms of deferred payment credit: the Financial Conduct Authority notes that Section 75 of the Consumer Credit Act is available on regulated buy now pay later agreements, the same protection you would have if you used a credit card36.
Debit cards work differently. MoneyHelper notes that debit cards also offer chargeback protection on all purchases, but not Section 7537. Chargeback is a scheme rule rather than a legal right, and it has no minimum or maximum amount, but it is weaker protection than Section 75. The comparison is set out in full on Section 75 or chargeback, and the claiming process on how to make a Section 75 claim.
Complaints and where to get help
If something goes wrong with an additional cardholder arrangement, a third party authority or the way the provider has handled the account, the first step is to complain to the provider itself. If it does not resolve the matter, the Financial Ombudsman Service can look at it for free.
Credit card complaints are one of the ombudsman's biggest workloads. In 2025/26, credit cards were the third most complained about product, with around 22,800 complaints7. In the first quarter of 2025/26 alone, the ombudsman recorded 6,600 new credit card complaints and upheld 25% of those it decided38. In the first quarter of 2026/27, 5,783 credit card complaints were opened, alongside 757 about debit cards, 129 about store card accounts, 62 about business credit cards and 19 about pre-paid cards39. Even NS&I, better known for savings, recorded 13,609 complaints in its banking and credit cards grouping between 1 October 2025 and 31 March 202629.
| Complaint category | New complaints, Q1 2026/27 |
|---|---|
| Credit cards | 5,78339 |
| Debit cards | 75739 |
| Store card accounts | 12939 |
| Business credit cards | 6239 |
| Pre-paid cards | 1939 |
Typical disputes that reach the ombudsman in this area include charges applied to an account, the handling of a request to remove an additional cardholder, and liability arguments after a relationship ends. The ombudsman decides each case on its facts, and its decisions are binding on the provider if the consumer accepts them.
Free, impartial help is available at every stage. MoneyHelper explains the complaints process, and the ombudsman itself can be contacted directly once the provider has had eight weeks or has issued a final response. For problems with the debt itself, help with credit card debt sets out the free advice charities and the options, including for people in Scotland and Northern Ireland, where some debt rules differ from England and Wales.
Sources39 cited
- Joint debts: who is liable StepChange, 2026-09-25
- Add a third party to your account Tesco Bank, 2026-09-25
- Choosing and applying for a credit card Citizens Advice, 2026-09-25
- Credit card debt StepChange, 2026-09-25
- What happens to debts when you get divorced National Debtline, 2026-09-25
- Buy now pay later Financial Conduct Authority, 2026-02-11
- NS&I complaints performance NS&I, 2025
- Earn cashback FAQs Halifax, 2026-09-27
- Credit cards and debt nidirect, 2025-11-06
- Whose debt is it? Shelter Cymru, 2026-08-30
- Relationships and your money Independent Age, 2026-09-26
- Six steps to financially separate from your ex Which?, 2023-05-21
- Credit reference agencies Business Debtline, 2026-09-26
- Joint accounts MoneyHelper, 2026-09-25
- Debt when someone dies nidirect, 2026-06-26
- Finding out who I owe money to StepChange, 2026-09-25
- Plastic cards Citizens Advice, 2026-09-25
- The costs and charges of credit cards Citizens Advice, 2026-09-25
- Dementia and managing money nidirect, 2026-09-03
- The costs and charges of credit cards (Scotland) Citizens Advice Scotland, 2026-09-25
- Understanding interest charges StepChange, 2026-09-25
- Credit cards for a bad credit score StepChange, 2026-09-25
- Making the most of your bank account Independent Age, 2026-09-26
- Nominate someone to collect your State Pension GOV.UK, 2026-09-26
- How a creditor can get information about your finances Citizens Advice, 2026-09-25
- Accessible banking and financial services Scope, 2026-08-17
- Direct debits and standing orders explained Which?, 2026-03-05
- Check if you have to pay a debt Citizens Advice, 2019-02-22
- How joint debts affect me StepChange
- Supporting customers separating finances from an abuser Surviving Economic Abuse, 2022-04
- Separating your finances Surviving Economic Abuse, 2023-11
- Fraud and economic crime National Crime Agency, 2026-09-26
- Protect your identity nidirect, 2025-10-28
- Bereavement and coping with loss TSB, 2026
- Consumer Credit Act Which?, 2025-06-18
- Shop safely online MoneyHelper, 2026-09-25
- Quarterly complaints data Q1 2026/27 Financial Ombudsman Service, 2026
- Annual complaints data and insight 2025/26 Financial Ombudsman Service, 2025
- Quarterly complaints data Q1 2025/26 Financial Ombudsman Service, 2025-08-07

 MoneyHelperFree, impartial money and pensions guidance, set up by government
 StepChangeFree debt advice and solutions from a charity
 National DebtlineFree debt advice by phone, webchat and online
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales