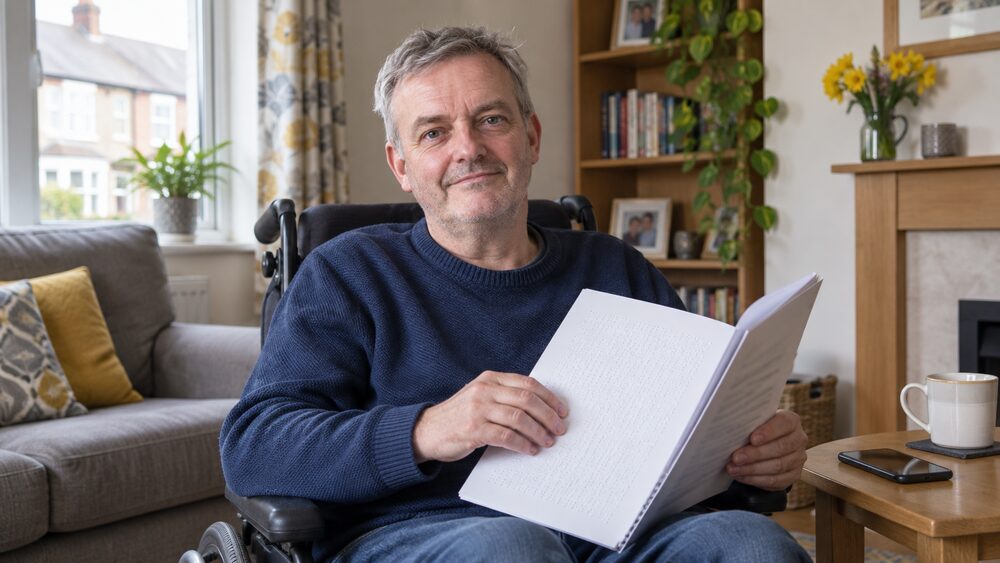
If a disability or a health condition makes it harder to deal with an insurer, you can ask the insurer to change how it serves you. These changes are called reasonable adjustments, and financial businesses must make them so that you can use their services1. They can cover the whole process, from the application form to the policy documents to how a claim is handled.
If a disability or a health condition makes it harder to deal with an insurer, you can ask the insurer to change how it serves you. These changes are called reasonable adjustments, and financial businesses must make them so that you can use their services1. They can cover the whole process, from the application form to the policy documents to how a claim is handled.
The most common request is for documents in a different format. Giving you application forms in braille, large print or audio is a standard example of a reasonable adjustment2. Some insurers already offer this as a matter of course: LV= says you can get its documents in braille, large print or audio format3. If yours does not, you can ask.
The duty comes from the Equality Act 2010, and not making reasonable adjustments is discrimination2. That does not mean every request has to be granted in exactly the form you ask for, but it does mean an insurer cannot simply ignore the issue. This page explains what you can ask for, how to ask, and where to take a complaint if an insurer will not help.
What reasonable adjustments are when you buy insurance
A reasonable adjustment is a change an organisation makes so that a disabled person can access and use its services in the same way, or as close as possible, as a non-disabled person6. In insurance, that can mean changing how information is given to you, how questions are asked, how long you have to respond, or how a claim is handled.
The duty sits alongside the ordinary rules on buying cover. When you buy or renew a policy, the Consumer Insurance (Disclosure and Representations) Act 2012 says you need to take reasonable care not to make a misrepresentation7. If an insurer asks you a clear question when your policy is sold or renewed, you have a duty to take reasonable care in answering it5. An adjustment can help here: if a question is hard to read or understand, asking for it in a different format or with more time is a way of making sure you can answer it properly.
Insurers also have their own duties. A firm should take reasonable steps to ensure that a customer only buys a policy under which they are eligible to claim benefits6. And where a customer is struggling, for example wanting to reduce cover or having difficulty paying the premium, the rules set out options the firm should consider, including adjusting cover and not requiring all contractual fees where that would be needed for fair treatment8.
Adjustments are not the same as policy changes. Telling your insurer about a change that affects your cover, such as adaptations to your car, is a separate matter, and adaptations can make it more expensive for the insurance company to repair your car, which may push premiums up3. A reasonable adjustment is about how you are served, not about what is covered.
The Equality Act: insurers must make reasonable adjustments
The Equality Act 2010 prevents discrimination and sets out the duty to make reasonable adjustments for disabled people6. For financial services, the practical effect is direct: if you have a disability, financial businesses must make reasonable adjustments so that you can use their services1.
The same duty runs through other organisations you may deal with. HMRC has responsibilities under the Equality Act to make sure no one is disadvantaged because of their health9, and its internal guidance says it should make reasonable adjustments for a person with mental health issues which have a substantial and long-term adverse effect on their ability to carry out normal day-to-day activities10. Creditors must make reasonable adjustments to help you if you have a mental health condition11. Employers must make reasonable adjustments for disabled people under the Equality Act 201012.
There is an important limit, and it is specific to insurance. The Equality Act permits insurers to charge customers more or refuse to offer insurance if age or disability means they are more likely to make a claim, where those judgements are "relevant" and "reasonable"7. So an insurer can, in principle, price or decline cover based on disability, provided it can justify that. What it cannot do is fail to make adjustments to how it serves you. The two things are separate: how you are treated as a customer, and how your risk is assessed.
"If you have a disability, financial businesses must make reasonable adjustments so that you can use their services"
Adjustments you can ask for when applying
The range of adjustments is wider than most people expect. For benefits applications, the examples given include braille, large print or audio formats, home visits, a British Sign Language (BSL) interpreter, extra time, venues with level access and wide doors, and being able to change appointment times if your condition means you cannot manage a fixed slot2. The same kinds of change translate directly to insurance.
When you are applying for cover, adjustments can include:
- Application forms and policy documents in braille, large print or audio2
- Extra time to read questions and give answers2
- A BSL interpreter if you need one2
- A home visit instead of an appointment elsewhere2
- Changing appointment times to suit your condition2
- Help understanding what you are being asked, so you can answer accurately5
There is a practical reason to get the questions right. If an insurer asks a clear question and you do not take reasonable care in answering, the consequences can be serious: if customers do not take reasonable care, insurers may be allowed to void policies and refuse false claims or alter the terms of a policy7. An adjustment that helps you understand and answer the questions protects you as well as making the process fairer.
If you use a broker, that can change what is available to you. A broker might speak to loss adjusters and claims departments and do as much as possible for you8, which can take some of the administrative burden off you.
How to ask an insurer for a reasonable adjustment
There is no single form for this. The important thing is that the insurer knows what you need and why, in practical terms. You do not have to give a full diagnosis; describing the effect is usually enough.
A straightforward approach:
- Contact the insurer, by phone, in writing or through its app, and say you need an adjustment.
- Explain what would help, for example documents in large print, more time, or a different way of communicating.
- Ask for the adjustment to be recorded on your file so it applies to future contact too.
- If you are applying, ask for the questions in a format you can use before you answer them2.
- Keep a note of who you spoke to and when.
If your circumstances change, adjustments can be revisited. In other areas of financial services, the same principle applies: an income payment arrangement can be changed if your circumstances change13, and a person who has made a claim for benefit may amend it at any time before a determination has been made14. The underlying idea, that arrangements should flex as things change, is a useful one to hold on to when dealing with an insurer.
If you want someone else to deal with the insurer for you, you can arrange that. A broker can act on your behalf8, and there are formal arrangements such as appointeeship for benefits if someone needs to manage affairs more broadly15.
If an insurer refuses or does not respond
An insurer can decline a specific request if it can show the change is not reasonable, but it cannot ignore the duty. Not making reasonable adjustments is discrimination2. If you are refused, ask for the reason in writing.
The complaint route is the same as for any insurance dispute. Complain to the insurer first. If the business does not reply within the time limits, or you disagree with its response, you can bring the complaint to the Financial Ombudsman Service7. The Ombudsman can tell the insurer to put things right and may pay compensation for distress or inconvenience5.
The Ombudsman looks at what is fair in the circumstances, not just what the rules literally say. In one case, where a policyholder had forged a receipt during an otherwise valid claim and tools were excluded from the home policy, the complaint was upheld and the fair and reasonable solution was for the insurer to reinstate the policy and pay the claim16. That shows the Ombudsman will look at the whole picture.
There are limits to what a complaint can achieve. If an insurer's questions or guidance were unclear, the Ombudsman is likely to say it is unfair for the insurer to reduce the claim payment, void the policy, or adjust the claim in other ways17. But where the insurer acted properly, the outcome will reflect that.
If your complaint is about how your data has been handled, there is a separate route. You have a right to have inaccurate data corrected, and an organisation can refuse a request that is manifestly unfounded or excessive, or ask a reasonable fee to deal with it18.
Where to get help
Several organisations offer free, impartial support:
- Financial Ombudsman Service: the free dispute resolution service for complaints about insurers5
- MoneyHelper: government-backed guidance on money and insurance, including using a broker8
- Scope: advice on disability rights, including appointeeship and benefits15
- Mencap: advice and support for people with a learning disability6
If your complaint involves discrimination, the Ombudsman can consider it. The service handles complaints that involve discrimination as part of its wider remit1.
Sources18 cited
- Complaints that involve discrimination Financial Ombudsman Service
- Discrimination when claiming benefits Scope, 2026-05-19
- Multi Cover insurance LV=, 2026-09-28
- Car insurance add-ons, fees and charges Which?, 2025-12
- Travel insurance policy complaints Financial Ombudsman Service, 2026-09-26
- Benefits for people with a learning disability Mencap
- Misrepresentation and non-disclosure Financial Ombudsman Service, 2026-09-26
- When to use an insurance broker MoneyHelper, 2026-09-25
- Stopping work due to ill health or retirement Scope, 2025-12-31
- Finding the right insurance cover Mental Health and Money Advice, 2023-09-05
- Access to Work GOV.UK, 2026-09-26
- The Disability Assistance for Working Age People (Scotland) Regulations 2022 legislation.gov.uk, 2026
- Debt and mental health National Debtline, 2026-09-25
- The Social Security (Claims and Payments) Regulations 2013 legislation.gov.uk, 2013-02-25
- Becoming an appointee Scope
- Case 42/3 Financial Ombudsman Service, 2004-12
- Underinsurance in home insurance Financial Ombudsman Service, 2026-09-26
- Your right to get your data corrected Information Commissioner's Office, 2026-09-26












 MoneyHelperFree, impartial money and pensions guidance, set up by government
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 FSCSProtects your money if a bank, insurer or investment firm fails
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales
 GOV.UKOfficial information on tax, benefits and government services