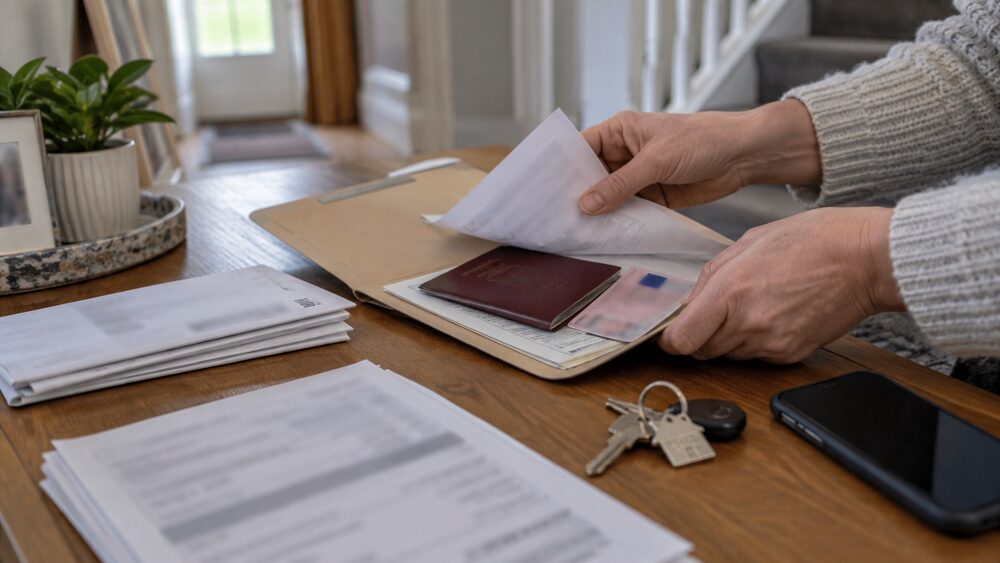
Co-Ownership is the shared ownership scheme in Northern Ireland, and applying for it means proving three things: who you are, where you live, and what you earn. Co-Ownership's own guidance says the application takes around 30 minutes to complete, that you can save your progress and come back to it, and that once all your documents are in, a decision takes up to 5 working days on average1.
Co-Ownership is the shared ownership scheme in Northern Ireland, and applying for it means proving three things: who you are, where you live, and what you earn. Co-Ownership's own guidance says the application takes around 30 minutes to complete, that you can save your progress and come back to it, and that once all your documents are in, a decision takes up to 5 working days on average1.
The core paperwork is short. You upload proof of identity, proof of current address, the last 3 months of payslips for all employment if you are employed, and the last 3 months of bank statements for all accounts1. Self-employed applicants and company directors send the last 2 years of tax calculation summaries (SA302s) and the matching tax year overviews instead of payslips1.
There is a fee, and it pays for a check of your income, outgoings and credit history3. If you apply with someone else, both of your Experian credit histories are reviewed during the application stage4. This page sets out what each document is for, what changes if you are self-employed or applying as a couple, and what happens after you submit.
Documents everyone needs: identity, address and income
Co-Ownership's acceptable documents list works on a two-list system for identity. You provide one item from List A and one from List B, or alternatively one item from List A and another item from List A that shows your current address on it1. The scheme's own summary of the process puts it more simply: proof of identity, proof of address, and evidence of your income2.
For identity, Co-Ownership states that it accepts a valid passport or UK driving licence4. That is a narrower list than some other financial products use. Credit unions, for example, usually ask for two recent documents to prove identity and address, which can include a student or work ID card, a bus pass or a birth certificate8. A basic bank account can be opened with a driving licence, a recent council tax bill, a recent letter about your benefits, a recent letter or statement from another bank, a recent utility bill or your TV licence9. Co-Ownership's list is tighter, so it is worth checking what you hold before you start.
For address, the wider market gives a sense of what counts as acceptable evidence: a recent gas or electricity bill or a TV licence10, or one or two of a recent utility bill, rental contract, or a benefits or state pension letter issued within the past 12 months11. Mortgage lenders commonly ask for two documents as proof of address, such as a bank statement, utility bill, council tax bill or credit card statement, dated within the last three months12.
Payslips or SA302s: income evidence for employed and self-employed applicants
What you send as income evidence depends entirely on how you earn, and Co-Ownership splits applicants into two groups.
If you are employed, you provide the last 3 months of payslips for all employment, plus the last 3 months of bank statements showing salary payments1. The phrase "for all employment" matters: if you hold more than one job, Co-Ownership says you need to provide payslips and evidence for all sources of employment13. A second job is not ignored because the first one covers the main income.
If you are self-employed or a company director, you provide the last 2 years of tax calculation summaries (SA302s) and the corresponding tax year overviews1. Company directors are asked for something extra on top: Co-Ownership also requires your last 3 months of payslips1. That combination, two years of tax documents plus three months of payslips, reflects the fact that a director's income can arrive in more than one form.
The wider mortgage market asks for broadly similar evidence. Lenders typically want statements from an accountant, a tax return form SA302, plus supporting information such as bank statements and receipts from self-employed applicants12. The two-year lookback is standard, because a single year's figures can be unrepresentative.
Evidence of savings and funds for your share
Beyond income, Co-Ownership may ask for proof of savings and other funds, and this sits in the "depending on your personal circumstances" part of its document list. The conditional items include residency documentation, proof of savings such as savings statements, proof of any other income such as benefit award letters, and, where relevant, a decree absolute, separation agreement or financial settlement documents1.
If you are providing evidence of savings, the kinds of documents that count in a means-tested context are bank, building society or Post Office books or statements, investment and share certificates, National Savings Certificates, Premium Bonds, and annuity or trust fund documents15. A professional property valuation, other than for the property you live in, can also serve as evidence15.
Where money has moved around before an application, the paper trail matters. In benefit assessments, documents may be requested to show that ownership of property has been transferred to another person, deeds showing money has been given to another person in trust, settlement or as a gift, and receipts showing what cash or savings has been spent on16. The same principle applies to a mortgage-style application: a large, unexplained movement in your accounts invites questions, and a document that explains it answers them.
If you are applying as a couple and one of you has come out of a previous relationship, the separation paperwork is part of the conditional list rather than an optional extra1.
Applying together: documents and credit checks for two applicants
Co-Ownership's rule on couples is not optional. If you are married, in a civil partnership, or planning to live with a partner, you need to apply together2. Both applicants must meet the eligibility criteria, and Co-Ownership assesses your combined household income and outgoings, with both of you equally responsible for the mortgage, if there is one, and the rent payments4.
Both applicants' Experian credit history is reviewed during the application stage4. That means a joint application is assessed on two credit files, not one, and a thin or damaged file on either side affects the outcome. It is worth both applicants checking their Experian report before applying, which is what Co-Ownership itself suggests4.
The documents are the same for each applicant: identity, address and income evidence for both people, plus the conditional items where they apply. The application fee covers a check of your income, outgoings and credit history3.
Submitting your application: the fee, the credit check and a decision
You can apply in one of three ways. Co-Ownership says you can apply online through your online account, through a mortgage adviser, or by booking a face-to-face appointment at its Belfast office, where a team member completes the application on your behalf4. The route you choose does not change the documents required.
The application fee covers a check of your income, outgoings and credit history3. Once Co-Ownership has all your documents, application review takes around five working days on average2, and the scheme says it takes up to 5 working days on average to reach a decision, varying with the complexity of the case and how quickly information comes back4. You can get updates on your application through your online account17.
If you are buying a property, a separate step follows: a Co-Ownership property assessment report is usually available in the Documents section of your online account within seven working days of uploading your property details6.
How long the whole process takes
Two timelines matter, and they are different lengths.
From application to completion, Co-Ownership says most applications take between three and six months, although this can vary depending on the case18. From accepted offer to completion, the typical figure is 8 to 12 weeks, which Co-Ownership describes as similar to any house purchase7.
The gap between the two figures is the property search. The approval window, 4 months for Co-Own, is the period in which you need to find a home and have an offer accepted6. Once you have an accepted offer, the 8 to 12 week completion period runs alongside the ordinary conveyancing work that any purchase involves.
For comparison, an equity release application to completion is typically within a week or two if everything is straightforward and the solicitor has sent the bundle of signed documents20. That is a different product with a different process, but it shows how much of the Co-Ownership timeline is the property purchase itself rather than the scheme's own administration.
If something goes wrong
The documents stage is where most applications stall, and the usual causes are predictable: an identity document that does not match Co-Ownership's accepted list, a missing bank statement for an account you had forgotten about, or income evidence that does not cover every job.
If you are struggling with debt or arrears while applying, free and impartial help exists. StepChange, Age UK and Business Debtline all provide debt advice, and debt advisers commonly ask for bank statements for the past 3 months as a starting point21. If you own your home with a mortgage and are having trouble paying, you may be able to apply for a Support for Mortgage Interest Loan for help with the mortgage interest22. The Home Owners' Support Fund schemes require you to complete an application form with the help of an approved money adviser and provide a letter confirming that you have taken independent money advice23.
If you are on Universal Credit or another benefit, note that savings and capital can affect what you receive, and there are rules on deprivation of capital if money has been given away or spent down before a claim15. A Discretionary Housing Payment claim usually requires your most recent payslip, bank statements covering the last two months, proof of any loan, credit card or hire purchase repayments, and letters from your landlord about rent arrears24.
For the application itself, Co-Ownership's help centre covers proof of income, supporting documents and bank statement requirements, and your online account is where updates appear17.
Sources24 cited
- Acceptable documents Co-Ownership, 2026-09-26
- Starting the process Co-Ownership, 2026-09-26
- Fees, costs and rent Co-Ownership, 2026-09-26
- Application process explained Co-Ownership, 2026-09-26
- What bank statements do I need to send? Co-Ownership, 2026-09-26
- Property assessment explained Co-Ownership, 2026-09-26
- Finding a property Co-Ownership, 2026-09-26
- Credit union current accounts MoneyHelper, 2026-09-25
- Basic bank accounts StepChange, 2026-09-25
- Evidence requirements Entitledto, 2026-09-26
- How to open a bank account online Which?, 2026-04-23
- Applying for a mortgage Which?, 2026-05-20
- I have more than one job: how is my income assessed? Co-Ownership, 2026-09-26
- Applying for a mortgage Which?, 2026-05-20
- Savings and other capital overview: Universal Credit Entitledto, 2026-09-26
- Deprivation of savings and other capital: Universal Credit Entitledto, 2026-09-26
- How do I get updates on my application? Co-Ownership, 2026-09-26
- Step by step process Co-Ownership, 2026-09-26
- What proof of income do I need to provide? Co-Ownership, 2026-09-26
- The application process Equity Release Council, 2026-09-26
- Debt advice Age UK, 2026-03-09
- Universal Credit housing costs element Turn2us, 2026-02-25
- Help with mortgage payments Business Debtline, 2026-09-26
- How do I claim a Discretionary Housing Payment? Turn2us, 2026-07-28











 MoneyHelperFree, impartial money and pensions guidance, set up by government
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales
 ShelterFree housing advice from a charity
 GOV.UKOfficial information on tax, benefits and government services
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right