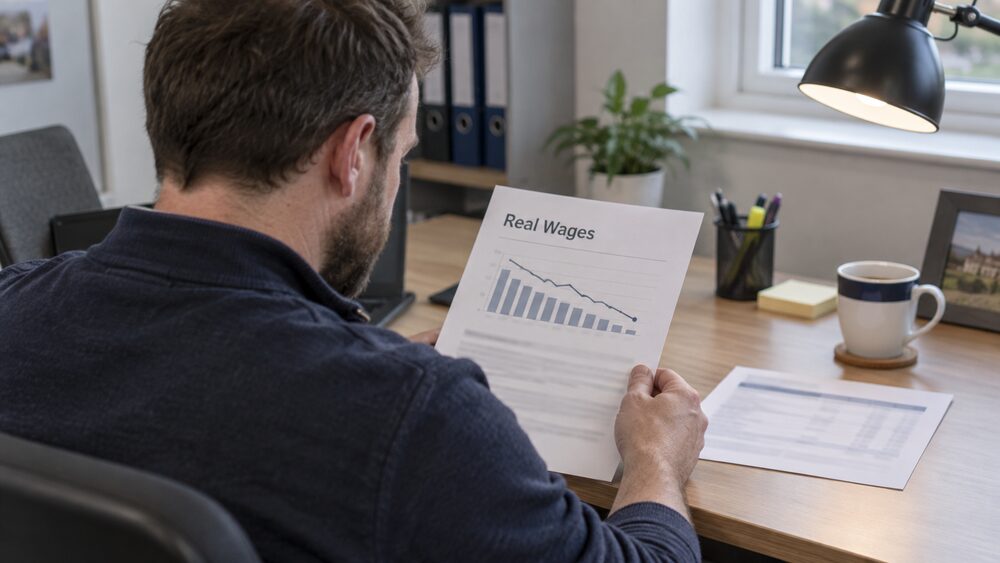
Real wages measure what your pay can actually buy once inflation is taken out. The picture since the cost of living crisis began is mixed. Real wages fell by 0.6 per cent in the fourth quarter of 2021, and the Resolution Foundation projected in January 2023 that they would not return to their Q1 2022 level until the end of 20271. More recently, real wages grew by 5% on one measure, and UK households saw a real-terms increase of £35.10 (5%) per week in the financial year ending 20253.
Real wages measure what your pay can actually buy once inflation is taken out. The picture since the cost of living crisis began is mixed. Real wages fell by 0.6 per cent in the fourth quarter of 2021, and the Resolution Foundation projected in January 2023 that they would not return to their Q1 2022 level until the end of 20271. More recently, real wages grew by 5% on one measure, and UK households saw a real-terms increase of £35.10 (5%) per week in the financial year ending 20253.
But the recovery is uneven. The poorest fifth of households saw a 10.1% real-terms decrease in wages and salaries in the financial year ending 2024, while the richest fifth saw a 3.6% real-terms decrease1. The Joseph Rowntree Foundation projects that real wages in 2029 will have risen by less than 6% since 2007, 22 years earlier5.
Inflation stood at 3.1% in the 12 months to August 2026, up from 2.9% the previous month6. That is well below the peaks of the cost of living crisis, but it still erodes pay. Whether real wages have "recovered" depends on which period you measure from and which households you look at.
Real wages: pay growth after inflation is taken out
Nominal wages are the figure on your payslip. Real wages are that figure adjusted for inflation, so they show what your pay can buy. The distinction matters because a pay rise can be a real-terms pay cut if prices rise faster.
The ONS publishes both. In the financial year ending 2024, mean equivalised original income for UK households fell by £1,400 (2.8%) in real terms, even though nominal incomes rose1. The previous year, average equivalised original income fell by £2,980 (5.9%) in real terms2. Those are large sums, and they explain why many households felt worse off even when their pay went up.
The pattern has not been uniform. Since June 2023, real wages have begun rising again, with 1.4% annual growth on one measure8. In the financial year ending 2025, UK households saw a real-terms increase of £35.10 (5%) per week in expenditure, and transport spending rose by £8.10 (9%) per week in real terms4. Package holidays abroad rose by £4.10 (14%) in real terms4.
"real wages are not expected to return to their Q1 2022 level until the end of 2027"
How inflation reduces what your pay buys
Inflation is the rate at which prices rise. When inflation is 3.1%, prices are rising at that annual rate, and pay that rises by less than the inflation rate falls in real terms. In the financial year 2022/23, compared with the Consumer Price Index, real earnings fell by 3%1. The real value of take-home pay has been falling since May 20222.
The effect compounds. The Bank of Scotland's guidance illustrates this: at 2.5% inflation, £1,000 would be worth £610 after 20 years9. That is not a prediction, but it shows how inflation erodes value over long periods.
For households, the squeeze shows up in different ways. In the financial year ending 2025, net rent increased by £7.00 (14%) per week in nominal terms4. Transport costs rose in real terms. The Household Costs Index, which tracks the actual costs different household groups face, rose by 2.8% for all households in the year to June 202610.
The ONS compiles its consumer price indices from a large and representative sample of over 760 goods and services, collected from approximately 20,000 outlets within the UK11. Rates of change for CPIH and CPI are calculated from unrounded index levels, while RPI rates are calculated from the rounded published indices11. That methodological difference is one reason the measures can diverge.
The cost of living squeeze: what inflation has done to household costs
The cost of living crisis saw inflation reach levels not seen for decades. In the US and Euro Area, inflation peaked at 9% and 10.6% respectively12. The UK saw similar pressures. By November 2024, 85% of UK adults felt the cost of living was one of the most important issues facing the country, second only to the NHS at 86%13.
The squeeze was not felt equally. The poorest fifth of households saw a 10.1% real-terms decrease in wages and salaries in the financial year ending 2024, compared with a 3.6% decrease for the richest fifth1. The OBR noted a 4.5 per cent year-on-year decline in the real value of unemployment-related benefits in 2022-23, the largest fall since annual uprating began half a century ago14.
Some support was provided. The National Living Wage rose 6.6 per cent to £9.50 in April 2022, which helped restore some of the lost value, though that was soon eroded15. The Fair Repayment Rate is estimated to save supported households on average £420 per year16.
Inflation now: back up to 3.1% after falling
CPI inflation rose to 3.1% in the 12 months to August 2026, up from 2.9% the previous month6. On a monthly basis, CPI rose by 0.5% in August 2026, compared with a rise of 0.3% in August 20256. Core CPI, which excludes energy, food, alcohol and tobacco, was unchanged at 2.6%6.
The UK's inflation rate was higher than the first estimates for France (2.7%) and Germany (2.9%) in August 20266. Transport, particularly motor fuels, made the largest upward contribution to the August rise17.
Earlier in 2026, inflation had been lower. CPI was 2.6% in the 12 months to March 20254. It was 3.3% in March 2026, then fell to 2.8% in April 202618. By June 2026, the CPI services annual rate had eased from 3.7% to 3.6%19. The CPI all-services index rose by 3.4% in the 12 months to July 2026, down from 3.6% the previous month20.
The Bank of England held the base rate at 3.75% for the sixth consecutive meeting in September 2026, despite CPI inflation rising to 3.1% in August21. The Bank's guidance states that a moderate level of inflation is healthy for the economy as it helps drive economic growth22.
Have real wages recovered to where they were?
The answer depends on the measure and the period. On one measure, real wages grew by 5%3. On another, UK households saw a real-terms increase of £35.10 (5%) per week in the financial year ending 20254. Since June 2023, real wages have begun rising again, with 1.4% annual growth8.
But the Resolution Foundation projected in January 2023 that real wages would not return to their Q1 2022 level until the end of 20272. The Joseph Rowntree Foundation projects that real wages in 2029 will have risen by less than 6% since 2007, 22 years earlier5. The OBR projects only 0.5% real wage growth per year in the medium term7.
The distribution matters. The poorest fifth of households saw a 10.1% real-terms decrease in wages and salaries in the financial year ending 2024, while the richest fifth saw a 3.6% decrease1. The financial year ending 2023 saw a real-terms decrease of £2,980 (5.9%) in average equivalised original income2.
"Real wages in 2029 will have risen by less than 6% since 2007, 22 years previously"
What rising prices mean for your savings and budget
Inflation affects savings as well as pay. If your savings account pays less than the inflation rate, your money is losing value in real terms. The Bank of Scotland's guidance illustrates the principle: at 2.5% inflation, £1,000 would be worth £610 after 20 years9.
Tax complicates the picture. Basic rate taxpayers get a Personal Savings Allowance, but those earning £50,271 to £125,140 get up to £500, and additional rate taxpayers get none23. If you already send a Self Assessment tax return, you report any interest earned on savings there24. From 6 April 2027, the savings higher rate will be increased by 2 percentage points to 42%25.
For households on low incomes, support is available. In Wales, local authorities can provide support to households struggling with the rising costs of living, including help with heating costs26. The Fair Repayment Rate is estimated to save supported households on average £420 per year16. National Debtline lists organisations that can help with cost of living pressures in England and Wales26.
The minimum wage rose 4.1% to £12.71 per hour for eligible workers aged 21 and over from 1 April 202627. The basic State Pension increases every year by the highest of earnings growth in Great Britain, CPI price growth in the UK, or 2.5 per cent28.
Where to get help
For free, impartial help with money problems, MoneyHelper is the government-backed service23. National Debtline provides guidance on cost of living support in England and Wales26. In Wales, local authorities can provide discretionary support26. The Financial Ombudsman Service can help if you have a complaint about a financial firm.
For help with court fees, you may be eligible if you have a low income and less than £4,250 in savings29. The UK House Price Index is calculated by the ONS and Land & Property Services/Northern Ireland Statistics and Research Agency30.
Sources30 cited
- The effects of taxes and benefits on household income: financial year ending 2024 Office for National Statistics, 2024
- The Living Standards Outlook 2023 Resolution Foundation, 2023-01-09
- Long-term measures to reduce energy bills and debt Fair by Design, 2025-10-17
- Family spending in the UK: April 2024 to March 2025 Office for National Statistics, 2025
- A decade of falling incomes: JRF's pre-budget assessment of living standards Joseph Rowntree Foundation, 2025
- Consumer price inflation, UK: August 2026 Office for National Statistics, 2026-09-16
- Weak income growth leaves people with little resilience to shocks Joseph Rowntree Foundation, 2026-04-15
- Financial Fairness Tracker W9 University of Bristol, 2023-12
- Investing for beginners Bank of Scotland, 2026-09-27
- Household Costs Indices for UK household groups: April to June 2026 Office for National Statistics, 2026
- Consumer price inflation: includes all 3 indices (CPIH, CPI and RPI) QMI Office for National Statistics, 2026-03-25
- Understanding the cost of living crisis in Scotland Scottish Government, 2025-02-12
- Understanding the cost of living crisis in Scotland Scottish Government, 2024
- Welfare trends report Office for Budget Responsibility, 2022-05
- Largest ever cash increase in the National Living Wage to boost pay for millions HM Government, 2022-04
- Child poverty in the UK and Scotland Scottish Government, 2026-08-06
- Consumer price inflation, UK: August 2026 Office for National Statistics, 2026-08-11
- Bank of England explainer: current interest rate Bank of England, 2026-04
- Consumer price inflation, UK: June 2026 Office for National Statistics, 2026-07-22
- Consumer price inflation, UK: July 2026 Office for National Statistics, 2026-08-19
- Seven-figure remortgage demand climbs as big loan borrowers refinance Mortgage Solutions, 2026-09-17
- What is inflation? Coutts, 2026-09-26
- Current account MoneyHelper, 2026-09-25
- How you pay tax on savings interest HM Revenue & Customs, 2026-09-28
- Budget 2025: overview of tax legislation and rates HM Treasury, 2027
- Cost of living: other organisations could help (England and Wales) National Debtline, 2026-09-25
- A National Plan to End Homelessness House of Commons Library, 2026-04-01
- Qualifying basic State Pension nidirect, 2026-09-09
- How to make a tenancy deposit compensation claim Shelter England, 2026-07-20
- UK House Price Index for July 2026 HM Land Registry, 2026-09-16



 MoneyHelperFree, impartial money and pensions guidance, set up by government
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales
 GOV.UKOfficial information on tax, benefits and government services
 StepChangeFree debt advice and solutions from a charity
 FSCSProtects your money if a bank, insurer or investment firm fails