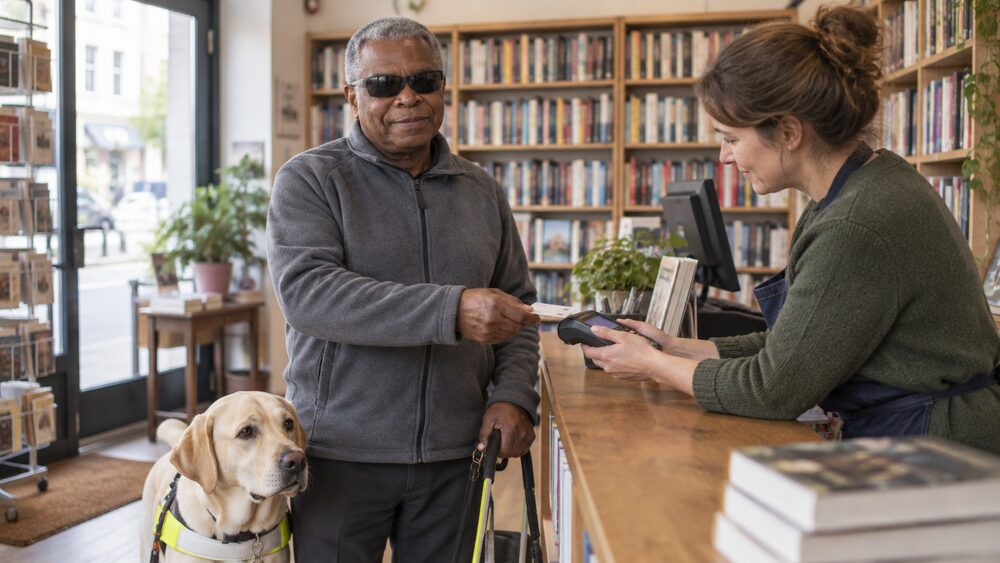
If entering a PIN or using a touchscreen is difficult, you can still pay by card. The main routes are a chip and signature card, which uses your signature instead of a keyed PIN, and contactless, which needs no PIN for payments up to £1001. Banks can also make adjustments to help, such as providing accounts without an overdraft or offering appointments to avoid queues1.
If entering a PIN or using a touchscreen is difficult, you can still pay by card. The main routes are a chip and signature card, which uses your signature instead of a keyed PIN, and contactless, which needs no PIN for payments up to £1001. Banks can also make adjustments to help, such as providing accounts without an overdraft or offering appointments to avoid queues1.
Chip and signature cards are offered by several banks for customers who have difficulty using a PIN, including Bank of Ireland UK, Danske Bank and first direct3. They work by signature rather than a keyed PIN, but they will not work in cash machines6. If you cannot use a PIN at all, that is the option to ask about first.
Where a card machine itself is the problem, UK Finance has said payment companies should let small and medium merchants swap touchscreens for physical PIN-pad devices without a material termination fee, and has recommended preserving consumer choice through continued access to physical PIN-pads7. That does not guarantee every shop will offer one, but it is the standard the industry has set.
Ways to pay without entering a PIN
The simplest route is contactless. There is no need to insert your card into the reader or enter your PIN for contactless payments12. The limit is £100 per transaction2. If the value is above the limit, the payment will default to a chip and PIN payment for card, or, if available, payment via mobile phone9.
Mobile and watch payments work differently. Apple Pay is accepted wherever contactless payments are, plus you can make payments over the contactless limit, though the merchant limit applies13. Barclays states you can make contactless payments up to £300 using a near-field communications (NFC)-enabled Android device14. Danske Bank notes that changing the contactless limit does not affect PIN payments at point of sale or spending using cards in a digital wallet15.
If you cannot use a PIN at all, a chip and signature card is the main alternative. Bank of Ireland UK offers chip and signature cards for anyone with difficulty using a PIN pad3. Danske Bank can provide Chip and Signature cards to assist customers who find it difficult to use Chip and PIN4. first direct lists its options as chip no PIN and chip and signature5. AIB (NI) offers Chip & Signature Cards to personal customers who have difficulty using a PIN16.
There are also ways to get cash without a PIN. Nationwide says you can visit a branch with ID such as a passport or driving licence, where a member of the team will help17. Leeds Credit Union's Cash Perks lets you withdraw via a one time use PIN and does not require a card18.
Chip and signature cards: who can get one and how they work
A chip and signature card does exactly what its name suggests: you provide your signature to make your payment instead of entering a PIN6. The card still has a chip, so it works in the same terminals as an ordinary card, but the terminal prompts for a signature rather than a PIN.
Eligibility is based on difficulty using a PIN, not on a specific diagnosis. Bank of Ireland UK offers them for anyone with difficulty using a PIN pad3. AIB (NI) restricts them to personal customers who have difficulty using a PIN16. Danske Bank provides them to assist customers who find it difficult to use Chip and PIN4. MoneyHelper lists chip and signature cards as a standard adjustment for customers who are unable to memorise a PIN1.
The main limitation is cash machines. Chip and signature cards will not work in cash machines6. That means you need another route for cash, such as a branch visit with ID, or a separate arrangement with your bank.
To ask for one, contact your bank and explain the difficulty. Bank of Ireland UK's own guidance is to request a Chip and Signature card, which works by using your signature rather than keying your PIN6. first direct lists chip no PIN as a separate option alongside chip and signature, so it is worth asking which of the two suits your situation5.
Contactless, phone and watch payments and their limits
Contactless payments allow you to make fast and secure payments up to £100 just by touching your card to the reader2. In the UK, there has been a £100 limit for tap and pay contactless credit and debit card purchases, meaning you would be asked for PIN authentication above this20. If your purchase exceeds this amount, you can still complete the payment using chip and PIN21.
Phone and watch payments sit outside that limit in one important way. Apple Pay is accepted wherever contactless payments are, plus you can make payments over the contactless limit, though the merchant limit applies13. Barclays states you can make contactless payments up to £300 using an NFC-enabled Android device14. Danske Bank notes that changing the contactless limit does not affect PIN payments at point of sale or spending using cards in a digital wallet15.
One practical point: contactless must usually be activated first. Lloyds Bank says that to activate contactless payments on your card, you will need to first use it with your PIN, which could be in a shop or at a cash machine22. If you cannot use a PIN, ask your bank how contactless will be activated on a chip and signature card.
You cannot withdraw money from a cash machine using contactless. You need to enter your PIN2. That is a hard limit, and it is why cash access needs a separate plan.
Security checks that can still ask for a PIN or code
Contactless is not a guarantee of no PIN. For extra security you may occasionally be asked to enter your PIN9. HSBC says there is usually no need to enter your PIN, but you will occasionally be asked to enter your PIN or sign for a transaction for extra security6. first direct says you will need your PIN for payments over £100 and from time to time you may be asked to enter it so the bank can make sure it is you23.
The pattern varies by provider. Tesco Bank states that as a security measure, if you make several contactless payments in a row, you may need to use Chip and PIN before you can carry on24. The Cumberland says occasionally, when making a contactless payment, you will be asked to enter your PIN as extra security25. RBS says additional security checks may occasionally be required, and when this happens you will be asked to enter your PIN to confirm your identity21.
Under Strong Customer Authentication, card present transactions such as Chip & PIN do not require dynamic linking26. That matters because it means the security framework treats a physical card transaction differently from an online one.
There is a scam angle here too. Banks will not ask you for your account number or PIN when making a fraud suspicion call27. If someone rings claiming to be your bank and asks for your PIN, that is not your bank.
Letting someone else pay or help you pay safely
There are formal routes for letting someone else handle payments, and informal ones that carry more risk.
A third party mandate lets someone call the bank, query statements and operate the account, but they cannot arrange a formal overdraft or open or close an account11. You cannot transfer a third party mandate to another account or bank28. HSBC lists decreasing the card limit among the things a third party mandate can do29. Most banks, building societies or other account providers allow a third party access to your account, for example with a second card30.
Some banks offer a separate card designed for this. Starling's Connected Card works by funding a Space and giving the card and PIN to the other person, which authorises anything they spend31. That is a clear boundary: the money available is limited to what you have put in the Space.
Sharing your PIN on your own card is a different matter. If the correct PIN is entered, the card issuer will usually bear liability for fraud committed by the person using the card, but if the cardholder discloses their PIN, responsibility may shift7. In practice, that means telling a carer your PIN can move the risk of misuse onto you.
For paying for work, paying by credit card rather than cash gives extra protection, and you may be able to get your money back if something goes wrong32. Open banking payment initiation services let you instruct payments directly out of your bank account, as an alternative to using a third party such as a Visa debit card or PayPal33.
Asking your bank for help and complaining if it falls short
Banks should make adjustments to help meet a disabled person's needs28. Scope lists examples including communicating in an accessible way, having a quiet meeting space, providing bank accounts without an overdraft, and offering appointments to avoid queues28.
If you cannot use a PIN, ask specifically. Danske Bank offers an alternative option for customers who are unable to use a PIN to complete card transactions, and directs customers to contact their local branch or Finance Centre34. Nationwide says you can visit a branch with ID such as a passport or driving licence and a member of the team will help17.
If something goes wrong, the first step is your bank. If you have revealed personal information or see unrecognised activity, contact your bank using the phone number on the back of your card or on a recent statement32. If you claim the use of the card was not authorised by you, it is for your bank to prove otherwise35. Note that purchases from vending machines or automated commercial premises are excluded from the distance selling rules that cover some card disputes35.
On charges, organisations are not allowed to add surcharges for paying by consumer debit or credit card, although accepted payment methods can vary by council10. You can still be charged extra if your bank or the seller's bank is outside the European Economic Area36.
If your bank does not resolve it, you can take the complaint to the Financial Ombudsman Service. Keep your card safe and shield your PIN whenever you enter it37, and always shield your PIN when entering it38.
Sources38 cited
- Make your money easier to manage by yourself MoneyHelper, 2025-11-27
- Safer ways to pay Consumer Council, 2026
- Supporting customer needs Bank of Ireland UK, 2026-09-25
- Supporting our customers Danske Bank, 2026-09-25
- Additional banking support first direct, 2026
- Living with dementia HSBC UK, 2026
- Enhancing Accessibility in Card Payments Report UK Finance, 2026-06
- Enhancing accessibility in card payments UK Finance, 2026
- Contactless limit change FAQs UK Finance, 2026
- Paying council tax Which?, 2026-04-17
- Setting up power of attorney Which?, 2026-02-26
- What is a contactless card Ulster Bank, 2026-09-25
- Set up Apple Pay RBS, 2026-09-25
- Mobile banking services terms and conditions Barclays, 2026
- Security Danske Bank, 2026-09-25
- Accessibility and disability AIB (NI), 2026
- PIN change Nationwide, 2026
- Cash Perks Leeds Credit Union, 2026-09-01
- Accessing your money Leeds Credit Union, 2026-08-24
- What is Apple Pay Which?, 2026-03-05
- Is there a limit for contactless card payments RBS, 2026-09-25
- Tips for managing your credit card Lloyds Bank, 2026-09-27
- Contactless first direct, 2026
- Contactless Tesco Bank, 2026-09-25
- Contactless The Cumberland, 2026
- Strong Customer Authentication FAQs UK Finance, 2026
- Scams quiz Independent Age, 2026
- Managing money for someone else Scope, 2025-11-27
- Third party mandate HSBC UK, 2026
- Nominate someone to collect State Pension GOV.UK, 2026-09-26
- Connected shopping card Starling Bank, 2026
- What to do if you've been victim of a scam Independent Age, 2026-09-26
- Open banking: sharing your financial data Which?, 2026-03-06
- Debit Mastercard Danske Bank, 2026-09-25
- Your payment card was used without your permission: distance sales Citizens Advice, 2026-09-25
- The costs and charges of credit cards Citizens Advice, 2026-09-25
- Card fraud Take Five, 2026-09-26
- Holiday fraud Take Five, 2026-09-26









 MoneyHelperFree, impartial money and pensions guidance, set up by government
 StepChangeFree debt advice and solutions from a charity
 National DebtlineFree debt advice by phone, webchat and online
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales