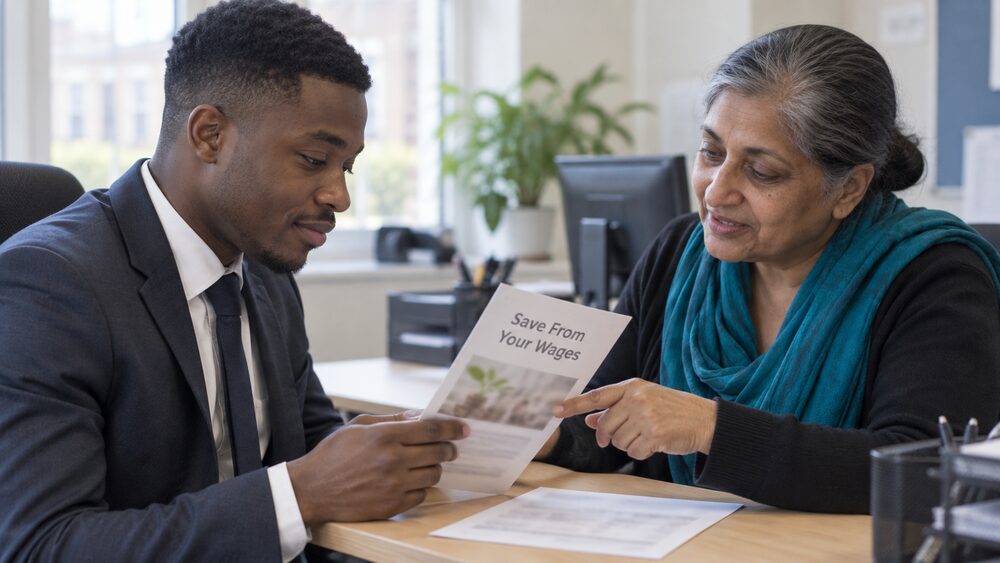
Payroll deduction takes a set amount out of your wages on payday and puts it into a savings account, before the money reaches your bank account. It is most common through a credit union that has a partnership with your employer, and it works because the deduction is agreed once and then repeats without you doing anything. One credit union describes it as saving "direct from your pay and before it reaches your bank account"1.
Payroll deduction takes a set amount out of your wages on payday and puts it into a savings account, before the money reaches your bank account. It is most common through a credit union that has a partnership with your employer, and it works because the deduction is agreed once and then repeats without you doing anything. One credit union describes it as saving "direct from your pay and before it reaches your bank account"1.
The catch is that it only exists where your employer has signed up. Credit unions that run these schemes say plainly that your employer must offer the scheme for you to use it2, and another says you can join and save this way if you are employed by a company that has signed up to its employee payroll scheme3. If your workplace has no scheme, you can still join a credit union directly and pay in another way.
The other thing to know is what you are joining. A credit union is a not-for-profit lender owned by its members, and membership is built around a "common bond", a shared link such as where you live, the industry you work in or the employer you work for4. Your savings are protected by the Financial Services Compensation Scheme, and the current limit for credit union deposits is £120,000 per person5.
How saving through payroll deduction works
The mechanics are simple. You join the credit union, complete a payroll deduction mandate, and the credit union tells your employer's payroll team how much to deduct. From then on the amount comes out of each pay packet automatically. One credit union puts it as joining and completing a mandate, after which "we will do the rest"1. Another describes the appeal in similar terms: "Save automatically with payroll deduction and watch your money grow without lifting a finger"8.
The money lands in your own savings account with the credit union, not in a separate pot held by your employer. That matters for two reasons. First, it is your account, so you can usually pay in more by other means as well: credit unions commonly accept deposits from salary, benefits or Direct Debit9. Second, it means you need to be a member before payroll saving can start, because the deduction is putting money into your own account7.
Changing the amount is usually a paperwork step rather than a phone call. One credit union asks members to complete a new payroll deduction mandate, and warns that the new figure "over-writes your existing amount so should be the total you wish to save, not the increase or decrease"1. Another says that if your employer is already a partner and you are already a member, you complete a payroll deduction amendment and select how much you want to save9.
Some employers run their own version. One credit union calls its arrangement an Employer Partnership Scheme, which "allows you to save through your payroll which means you won't even see it leave your pay"10. The principle is the same: the money moves before you have a chance to spend it.
Who can join: the common bond with your employer
Credit unions do not take all comers. Membership is open to people who share a "common bond" with other members, and that bond can be based on the area members live in, the occupation they work in, or the employer they work for11. Official guidance describes the same idea: members share a common bond such as living, working, studying or volunteering in a certain area, working in the same industry or for certain employers, or belonging to the same trade union4.
An employer-based common bond is the one that matters for payroll saving. One credit union's rules require you to work for one of the employers listed in its common bond, or to be a close relative of an existing member who works for one of those employers and lives at the same address12. Another opens membership to anyone living or working in its common bond, anyone employed by one of its employer partners, or a member of a named trade union13. A third uses an occupational bond: you can usually join if you work in an eligible UK occupation, have retired from one and receive a private pension, live in the same household as an existing member, or belong to a listed partner organisation14.
The household route is wider than it sounds. Guidance for credit unions says that as long as one family member meets the common bond requirements and has joined, other family members living at the same address can usually join15. Independent debt guidance makes the same point: anyone in the house of a person with a common bond can usually join16.
So the practical question is not only "does my employer have a scheme" but "which credit union can I join". If your employer has no partnership, a community credit union covering your area, or one covering your occupation, may still be open to you.
Borrowing from the credit union you save with
Saving with a credit union is often the route into borrowing from it, and the two are designed to run together. One credit union says that with its payroll deduction scheme loan you build savings at the same time as borrowing17, and another says that as part of the agreement, repayments will be split between your loan and savings18.
The amount you can borrow is usually linked to what you have saved. Independent guidance states that credit unions allow you to borrow two or three times as much as you have saved, at a low interest rate6, and the same two-or-three-times rule appears in debt guidance for England and Wales and for Scotland19. The exact multiple depends on the loan policy of your credit union19.
Credit unions also lend to people who struggle to borrow elsewhere. Welsh Government guidance says they provide access to fair and affordable credit for people with a poor credit history, help those who cannot access mainstream forms of credit, and provide loans starting from £5021. The same guidance says credit unions always consider affordability when assessing loan applications21.
Two conditions are worth knowing before you borrow. You need to be a member to get a loan, and some credit unions will ask you to build up savings first22. Others lend as soon as you become a member15. And there is a sting in the tail if things go wrong: if you miss payments on a loan, the credit union may be able to use your savings to repay the loan19. That is a real difference from a bank, where a savings account and a loan are normally kept apart.
Setting it up and getting your money out
Setting up payroll saving is a short sequence, and the order matters because the deduction has to have somewhere to go.
- Check that your employer is a partner of a credit union, or find a credit union you can join on a community or occupational bond.
- Join the credit union. You will usually need two recent documents to prove your identity and address, such as a passport, driving licence, student or work ID card, bus pass, birth certificate, bank statement or energy bill4.
- Open a savings account. Some credit unions require you to be a member to hold particular accounts, and membership eligibility criteria apply23.
- Complete a payroll deduction mandate and give the amount you want deducted1.
- Check your payslip the first month to confirm the deduction has started.
Getting money out works like any other savings account, with one qualification: credit unions are mutuals, so some ask you to keep a small share balance to remain a member. Beyond that, access depends on the account. One credit union states that you can increase, reduce, pause or stop your payroll saving at any time, with no minimum term and no penalty for changing your mind7.
If you leave your job, nothing is lost. One credit union states that your savings and your membership stay with you and are not tied to your job, and that if you leave, your payroll deduction simply stops7. You can then arrange a standing order or Direct Debit to keep saving, or leave the balance in place.
A payroll deduction runs from your pay packet into your own credit union savings account.
FSCS protection: up to £120,000 per person
Savings held with a credit union are covered by the Financial Services Compensation Scheme, the same scheme that covers bank deposits. The current limit is £120,000 per person5. MoneyHelper states it in the same terms: just like most banks, up to £120,000 per person is protected in a credit union account4. Independent guidance from Which? lists credit unions at £120,000 per person, per firm24.
The limit changed on 1 December 2025, when it rose from £85,000 to £120,000 per individual, per financial institution25. That is why some credit union pages still quote the older figure of £85,00026. The £85,000 figure also still appears in FSCS material for other products, such as debt management and funeral plans, which are covered at £85,000 per person per firm29. For credit union deposits, the figure to work from is £120,000.
Two details matter in practice. The limit applies across all accounts you hold with the same credit union, not per account: FSCS protects up to £120,000 in total across all accounts you hold with the credit union5. And if you hold savings with a credit union and also with a bank in the same group, the limits can interact, so it is worth checking which firms share a licence.
Who provides payroll saving in the UK
Payroll saving is offered by credit unions, which are not-for-profit community lenders providing affordable loans and savings21. They are independent organisations that exist for the benefit of their members rather than for stockmarket shareholders11, and each has a volunteer board of directors30. Members hold a £1 share and each gets one vote regardless of how much they have saved, and any surplus is paid back to members as a dividend30.
Credit unions differ in how you reach them. Some offer online and phone banking, some have a local branch or service point you can walk into, and some work mainly through a payroll partnership with your employer, or a combination of all three31. If your workplace has no scheme, the trade body's finder website can help you locate credit unions15.
On cost, credit unions generally do not charge fees or transaction charges33, though membership terms vary: some are free to open34, one states free membership with no annual fee35, and others ask for a small fee such as £2 or a first deposit such as £104.
If you are comparing this with an ordinary savings account, the trade-offs are access, protection and the link to borrowing. Our guide to credit unions vs bank savings accounts sets the two side by side, and how FSCS protection works for savings explains the limits in more detail.
Sources35 cited
- Payroll deduction SaveEasy Credit Union, 2026-09-26
- Payroll member savings Just Credit Union, 2025-10-23
- Save through your pay Leeds Credit Union, 2026-08-25
- Credit union current accounts MoneyHelper, 2026-09-25
- Deposit protection for credit unions Financial Services Compensation Scheme, 2026-09-25
- Budgeting, saving and borrowing Business Debtline, 2026-09-26
- Payroll deduction savings Capital Credit Union, 2026
- Save with payroll deduction SCVO Credit Union, 2026-09-26
- Payroll for employees Kernow Credit Union, 2026
- Payroll deduction Calderdale Credit Union, 2026-09-26
- Help and FAQs Lisburn Credit Union, 2026-09-26
- Terms and conditions Keep Credit Union, 2026-09-03
- Membership Capital Credit Union, 2026
- Personal loans Capital Credit Union, 2026
- Credit unions Building Societies Association, 2026-09-15
- Credit unions StepChange, 2026-09-25
- Loans Partners Credit Union, 2026-09-26
- Payroll deduction scheme loan Darlington Credit Union, 2026-09-26
- Debt consolidation (England and Wales) National Debtline, 2026-09-25
- Debt consolidation (Scotland) Business Debtline, 2026-09-26
- Save, bank or borrow with a credit union Welsh Government, 2026
- Emergency funding StepChange, 2026-09-25
- Premier savings account Capital Credit Union, 2026
- FSCS: are my savings safe? Which?, 2025-12-01
- What to do if your bank goes out of business Which?, 2025-12-01
- What is a credit union SCVO Credit Union, 2026-09-26
- Fixed term savings Enterprise Credit Union, 2026-09-26
- FAQs AlBirr Credit Union, 2026-08-29
- FSCS protected badge leaflet Financial Services Compensation Scheme, 2025-11-27
- What is a credit union Capital Credit Union, 2026
- About credit unions Association of British Credit Unions, 2026-04-01
- About credit unions All Together Money, 2026-04-01
- Loans Lisburn Credit Union, 2026-09-26
- Loyalty loans Capital Credit Union, 2026
- Loans Keep Credit Union, 2026-07-30



 MoneyHelperFree, impartial money and pensions guidance, set up by government
 FSCSProtects your money if a bank, insurer or investment firm fails
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales
 GOV.UKOfficial information on tax, benefits and government services