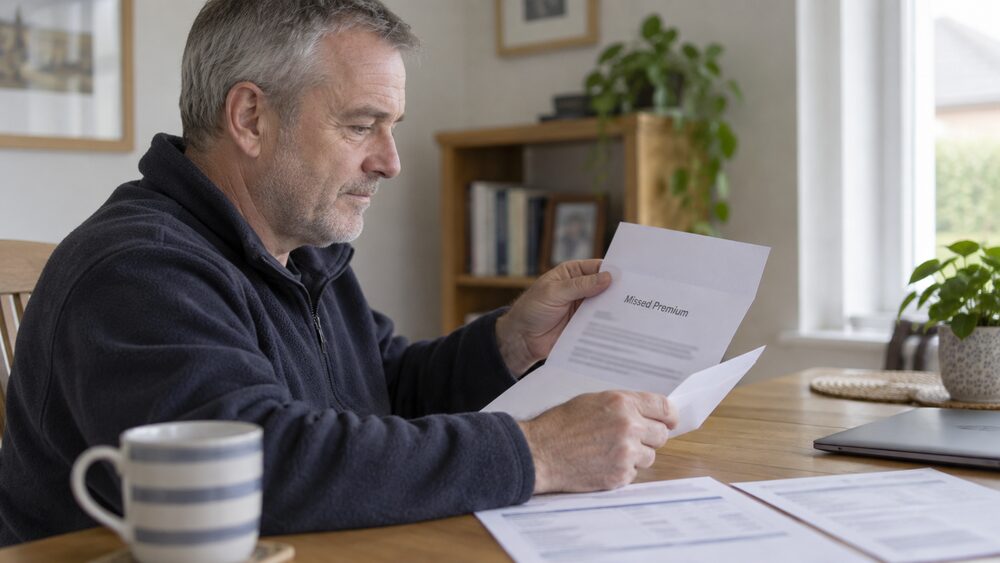
A missed life insurance payment does not usually end the policy straight away. Many life insurance policies come with a grace period, usually around 30 days, during which the premium can still be paid and the cover continues as before1. Some insurers allow longer: LV= gives 60 days from the premium due date on its budget income protection policy before the policy is stopped and cancelled2. If the premium is still unpaid once the grace period runs out, a term policy lapses and the cover ends3.
After that, the consequences are serious. Independent guidance is clear that if a policy lapses due to non-payment of premiums, coverage stops and no benefits will be paid upon the policyholder's death1. Some insurers allow a lapsed policy to be reinstated: Zurich permits payments on its life plans to restart within 13 months, but only if all the missed payments are repaid4, and LV= allows a policy cancelled for non-payment to restart within six months of the first missed payment2. Beyond those windows, a new policy with a fresh application and new health questions is usually the only option.
A missed life insurance payment usually ends the policy
Life insurance usually pays out only when you die7, and term insurance only pays if you die within the time covered by the policy8. That is what makes a missed premium so consequential: the cover exists to pay a lump sum to your family or your estate, and once the policy has lapsed, that promise is gone. Independent guidance states plainly that if the policy lapses due to non-payment of premiums, coverage stops, and no benefits will be paid upon the policyholder's death1.
What happens next depends on the type of policy. With term assurance, if the premium is not paid, the policy lapses and cover ends3. There is no cashback value to most life insurance policies, so if you have to stop paying later because you cannot afford it, that money is lost9. If you do not die during the term of a term life policy, the death benefit is not paid and the premiums you have paid are not returned1.
Whole-of-life policies behave differently. Some of the plan's value typically remains if you stop paying, but it is far lower than the original cover and can reduce over time3. Whole-of-life cover pays out an agreed amount whenever you die, provided you have continued paying the premium, and some policies stop taking money when you reach 9010. Over 50s life insurance plans are stricter still: premiums must be paid until you die, and if you stop paying, the entire policy is cancelled with nothing back11.
Joint policies add a further dimension. Joint life insurance pays out on the first partner's death, while dual life policies pay out on the second partner's death12. If a joint policy lapses, both partners lose cover at once, and the surviving partner would need to apply for new cover alone, at their current age and health.
The grace period: usually around 30 days
Many life insurance policies come with a grace period, usually around 30 days1. The same figure appears in Which?'s guidance on policy types: a grace period of around 30 days, during which a refund of premiums paid may also be possible if you cancel1. The grace period is the buffer between a failed direct debit and the policy actually ending, and it exists so that a temporary problem, a changed bank account, a payday that moved, does not destroy cover that may have taken years to build.
Insurers set their own lengths. LV=, in the policy conditions for its budget income protection policy with guaranteed premiums, states: "You have 60 days to pay your premium from its due date." If the premium is still unpaid after 60 days, the policy is stopped and cancelled2. That is an income protection policy rather than life cover, but it shows how much the grace period can vary between products and providers. The only reliable way to know your own window is your policy documents.
If you notice a missed payment, acting within the grace period usually restores the policy to exactly what it was, with no health questions asked. Once the grace period has passed and the policy has lapsed, the position changes: reinstatement becomes a matter for the insurer's rules rather than a simple catch-up payment.
Restarting lapsed cover: time limits of six to 13 months
Reinstatement windows vary between insurers. Zurich states that for life plans, "restarting payments would only be allowed within 13 months if you repaid all the payments missed"4. LV= is tighter: a policy cancelled for non-payment can be restarted "as long as you let us know within six months of your first missed payment"2. Both windows run from the missed payment, not from the date you notice the problem, so the clock may already be part way through.
Within the window, reinstatement usually means paying what is owed and confirming the policy can continue. Whether the insurer asks new health questions at that point depends on its terms, and the dedicated page on reinstating lapsed cover covers what may be asked. Outside the window, the only route is a new policy, which means a new application, underwriting at your current age and health, and premiums priced accordingly. Someone who took out cover years ago in good health may find new cover costs more or comes with exclusions, particularly after a diagnosis, and the page on cover with a pre-existing medical condition explains that process.
A missed payment can also leave a mark elsewhere. If you have missed only one payment, your credit score could start to recover after around six months and should be fully recovered after a year14. The same recovery pattern, around six months to start recovering and a year for full recovery after a single missed payment, appears in earlier guidance as well15. A lapsed insurance policy is not itself a credit agreement, but missed payments on the bank account or card behind it can be, and the credit scores guide explains how that works.
Paying back missed premiums to reinstate a policy
Reinstatement is not free cover: the common thread in the insurer examples is that the missed premiums must be repaid. Zurich's rule is conditional on repaying all the payments missed4. LV= allows the policy to restart within six months of the first missed payment2, and its terms likewise expect the arrears to be settled. In practice this means a reinstated policy costs more in the short term, because you are paying the current month plus the months you missed.
Refunds run the other way, and only in specific circumstances. Guidance on cancelling notes that typically you will not get your money back if you cancel your life insurance, though a refund of premiums paid is possible during the grace period12. Where a policy was mis-sold, the Financial Ombudsman Service can order the firm to return everything paid: in one case concerning a whole-of-life policy sold instead of a savings plan, the ombudsman stated, "We therefore upheld the complaint and required the firm to refund all the premiums the couple had paid, together with interest"16. Legislation on certain long-term contracts goes further on termination: "If either party terminates the contract under this paragraph, the insurer must refund any premiums paid for the terminated cover in respect of the balance of the contract term"17.
In another ombudsman case, a whole-of-life policyholder complained he had been sold the wrong product, and the ombudsman told the bank "to calculate how much Mr A would have paid in premiums if he had taken out a 10-year term-assurance policy" and pay the difference18. These are complaints about how the policy was sold, not about missed payments, but they show the redress route if you believe the policy itself was wrong for you. If you are struggling rather than dissatisfied, the options are different: talk to the insurer about the grace period and reinstatement first, and see the help section at the end of this page.
Waiver of premium: cover that pays your premiums if you are ill
Waiver of premium is an add-on designed for exactly the situation where paying becomes impossible because of health. Age UK's financial jargon checker defines it as "a feature on a personal pension plan or life insurance plan that guarantees your contributions will be paid for a period of time, usually by the insurer, if you are ill or lose your job"19. Macmillan's guidance describes the same benefit in the protection insurance context: waiver of premium benefit can carry on paying your life insurance or critical illness cover premiums if you cannot work because of illness or injury, though it usually does not start paying out for a while after you stop work20.
The point of the benefit is that it keeps the policy alive when you could least afford to keep it going yourself. Without it, a long illness can create a double loss: the income stops, and then the life cover lapses because the premiums cannot be paid, leaving the family without the payout precisely when the worst has happened. With it, the insurer steps in and pays the premiums on the policy for a period, so the cover survives the illness.
Waiver of premium is not the same as income protection, which replaces part of your earnings. The income protection guide explains that product separately, and the comparison of life insurance and income protection sets out what each one pays for. Waiver of premium pays only the premiums on the policy it is attached to, nothing more.
Waiver of premium waiting periods: 4 weeks to 26 weeks in the examples
Waiver of premium does not start the day you stop work. Which?'s guidance on income protection myths states: "Typically, the default deferral period is 13 or 26 weeks, but it can be as short as four weeks"5. Macmillan gives the same range for income protection more broadly: the deferred period can be anything from 4 weeks to 1 year, and the longer the wait, the cheaper the monthly premium20. Citizens Advice notes that with income protection you usually have to wait a minimum of four weeks, but payments can start up to two years after you stop work21.
Provider examples show how widely the waiting period varies even within one insurer's range:
| Product | Waiting period | Notes |
|---|---|---|
| Guardian1821 Life Protection | 4 weeks | Premium Waiver included as standard, waives premiums after 4 weeks if too ill to work6 |
| Guardian1821 Life Essentials | 26 weeks | Premium Waiver included as standard, waives premiums if too ill to work after 26 weeks6 |
| Typical income protection deferral | 13 or 26 weeks | Can be as short as four weeks5 |
| Income protection range | 4 weeks to 1 year | Longer waits mean cheaper premiums20 |
During the waiting period you keep paying your own premiums, or the policy falls into the same missed-premium process described earlier in this page. That is why the length of the waiting period matters when choosing cover: a short wait protects you sooner but costs more, and a long wait is only workable if you could fund the premiums from savings for that period. The page on deferred periods explains the trade-off in detail.
What waiver of premium costs and where it does not apply
Waiver of premium usually costs extra19. It is typically charged as an addition to the premium for the main policy, and because life insurance and most other long term insurance is exempt from Insurance Premium Tax22, the add-on is not pushed up by that tax. The waiting period is the main lever on price, as the range of 4 weeks to 1 year shows20, but the definition of incapacity matters just as much: the page on incapacity definitions explains the difference between "own occupation" and weaker tests.
Where the benefit does not apply is just as important. The standard trigger is being too ill to work, as in Guardian1821's products, which waive premiums after 4 weeks or 26 weeks of illness depending on the plan6. Unemployment is treated differently: Guardian1821's Life Protection also waives premiums for up to 6 months for maternity or paternity leave or involuntary job loss6, but that is a feature of that particular product, not a market-wide rule. Age UK's definition notes waiver can cover losing your job on some plans19, so the only way to know is your own policy wording.
Waiver of premium also does not turn a life policy into anything it was not. Life insurance only pays out when you die, as a lump sum23, so it is not an alternative to cover that pays your mortgage while you are alive. Terminal illness benefit is the one early route on many policies: the policy could pay out early if a doctor says you have less than 12 months to live7, and if you are expected to live for less than 12 months, the insurer will pay out the full amount of the cover straight away, and you keep the money even if you live longer8. Terminal illness insurance pays out if you are diagnosed with a condition that is expected to be fatal within 12 months24. If critical illness cover is bundled with life insurance, a critical illness payout reduces the amount that could be paid out on death later within the term24.
Payment waivers on loans and car finance are not the same thing
The phrase "payment waiver" turns up in credit markets too, and it means something quite different. Payment protection insurance, or PPI, was sold with loans, credit cards, mortgages and other types of credit, including car finance and catalogue accounts25. PPI was designed to cover credit repayments if you could not pay them, and its history of mis-selling is covered on the PPI page. Waiver of premium on a life policy pays the premiums on that policy alone; PPI and its successors cover, or claimed to cover, the repayments on a debt.
Car finance has its own temporary relief mechanisms. During the coronavirus outbreak, drivers could apply for a payment holiday on car finance, and during the break, "you won't be regarded as being in arrears, and you or your guarantors won't be pursued for money"26. Those measures were not intended for drivers already in financial difficulties before the outbreak26, and a firm was not expected to make enquiries about personal circumstances or whether a holiday was in the customer's interests26. Where repaying car finance meant priority living costs could not be paid, the customer was entitled to be treated with forbearance, meaning the interest accrued during the payment holiday would be waived26.
The ordinary consequences of missing car finance payments are different again. The lender will contact you after you miss one or two payments and should discuss ways to catch up and pay the arrears. If you keep missing payments, they may issue a default notice, and default notices give you at least two weeks to make up missed payments27. After that, the lender can take further action to collect the debt and recover the car, possibly using a debt collection agency or applying for a county court judgment28. Whether the car can be taken back depends on the agreement: the finance company can take the car back if you miss payments on a lease or hire agreement, but a personal loan provider cannot take the car back if you miss payments28.
In one Financial Ombudsman case study, a customer explained "that he'd missed two repayments and the finance company had said it was going to take back the car"29. Gap insurance is another distinct product: guaranteed asset protection covers the difference between a car insurer's payout and the price paid for the vehicle30, or the difference between the price paid for a new vehicle and the amount the insurer will pay if it is stolen or written off soon after buying it31. None of these products protects your family in the way life insurance does, and none of them keeps a life policy alive.
One further distinction matters for benefits. Mortgage Payment Protection Insurance policies, or any equivalent payments, are no longer taken into account as income for Universal Credit32. Life insurance payouts are separate: the payout goes to your estate, not direct to the mortgage company, though it can be left in trust33, and the pages on tax on payouts and writing life insurance in trust explain what happens to the money.
Where protection stops, and where to get help
The protections around a lapsed policy have hard edges. Once a term policy has lapsed and the reinstatement window has closed, there is no payout on death, and no refund of the premiums paid1. Over 50s plans are the starkest example: stop paying and the entire policy is cancelled with nothing back11. The Financial Services Compensation Scheme protects policyholders if the insurer itself fails, paying 100% of term life insurance and critical illness cover claims where the firm failed on or after 3 July 2015, and 90% where it failed before34, and the page on life insurance and FSCS protection explains that cover.
Even a valid claim can be slow. Reported average processing times are 20 days for guaranteed over 50s plans and 53 to 122 days for term insurance, and some families face waits of up to four months for payouts, potentially leaving them without funds to cover urgent expenses35. The pages on how long a claim takes and claiming after a death set out the process and the documents needed.
If you cannot pay the premium, the order of options is roughly this:
- Check your policy documents for the grace period, and pay within it if you can1.
- Ask the insurer about reinstatement terms and the deadline, which in the examples run from six months to 13 months2.
- Check whether your policy includes waiver of premium, and claim it if illness is the reason you cannot work19.
- If the problem is wider debt, get free help: StepChange explains the arrears and default process for credit debts28, and the debt guide sets out the free advice options.
- If you believe the policy was mis-sold or a claim is wrongly refused, complain to the insurer and then to the Financial Ombudsman Service, which can order refunds of premiums with interest16.
The extra support page explains what insurers must do for customers in vulnerable circumstances, and changing your cover covers reducing the sum assured or other ways to cut the premium rather than losing the policy altogether.
Sources35 cited
- Types of life insurance policy Which?, 2025-05-16
- Budget Income Protection Guaranteed Premiums policy conditions LV=, 2026-09-28
- Should you consider life insurance to manage your inheritance tax bill Which?, 2025-10-20
- 90:10 with-profits fund explained Zurich, 2026-09-26
- 9 myths about income protection busted Which?, 2025-05-27
- Life cover Guardian1821, 2026-06-12
- Life insurance for pre-existing conditions Which?, 2026-06-25
- Types of insurance Macmillan Cancer Support, 2023-09-01
- Multiple life insurance policies explained Which?, 2025-11-20
- Joint life insurance explained Which?, 2025-08-06
- Over 50s life insurance Which?, 2025-12-03
- Types of life insurance policy Which?, 2025-05-16
- Types of life insurance policy explained Which?, 2025-05-16
- How to improve your credit score Which?, 2025-10-24
- Eight ways to boost your credit score in 2021 Which?, 2021-01-03
- Financial Ombudsman decision, case 25/03 Financial Ombudsman Service, 2003-02
- Schedules to the Act legislation.gov.uk, 2012
- Financial Ombudsman decision, case 85/6 Financial Ombudsman Service, 2010-04
- Financial jargon checker Age UK, 2026-08-26
- Protection insurance and cancer Macmillan Cancer Support, 2023-09-01
- Income protection insurance Citizens Advice, 2026-09-26
- Insurance Premium Tax briefing House of Commons Library, 2026-09-26
- What is mortgage protection insurance Which?, 2026-05-11
- Critical illness insurance explained Which?, 2026-08-24
- Payment protection insurance Financial Ombudsman Service, 2026-09-26
- Coronavirus: how to apply for a car finance payment holiday Which?, 2020-08-14
- Default notices and missed payments StepChange, 2026-09-25
- Car finance debt StepChange, 2026-09-25
- Consumer told us they were struggling to repay a car finance agreement Financial Ombudsman Service, 2026-09-26
- Gap insurance explained Which?, 2026-01-22
- Gap insurance sales suspended: what it means for you Which?, 2024-02-16
- Mortgages guidance UK Parliament, 2025
- What is mortgage protection life insurance Which?, 2026-09-25
- FSCS insurance cover FSCS, 2026-09-25
- Regulator flags long delays in life insurance payouts Which?, 2024-11-28


 MoneyHelperFree, impartial money and pensions guidance, set up by government
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 FSCSProtects your money if a bank, insurer or investment firm fails
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales
 Turn2usFree benefits calculator and grants search from a charity