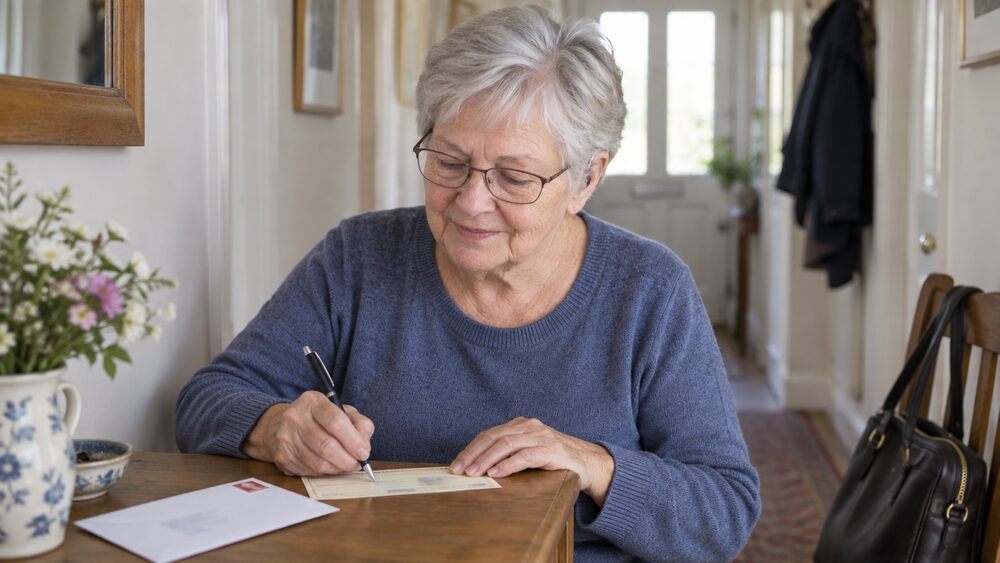
A postal order is a paper payment you buy at a Post Office counter and send to someone through the post, as a gift or as a payment. The Post Office describes them as "a way to send money to someone, as a gift or payment"1. You can send anything from 50p up to £250, and the fee is 50p on orders with a face value of 50p to £4.99, or 12.5% of the face value on orders of £10 to £99.991.
The attraction for many people is that neither side needs a bank account: the Post Office states there is "no need for a bank account or to share your financial details"1. The recipient of an uncrossed order can walk into a Post Office branch and cash it, while a crossed order is paid into a bank or savings account instead. Postal orders are issued under Section 112 of the Postal Services Act 2000, which gives them a formal legal basis1.
The trade-off is security. An uncrossed postal order is, in the Post Office's own words, "as good as cash. Like cash, they're also unsecure"1. The fee you pay is an admin charge, not insurance, so if the order goes missing there is a claims process but no guaranteed refund1.
What a postal order is and what people use it for
A postal order works like a pre-paid paper promise. You hand over cash at a Post Office counter, the order is made out to the person you name, and you post it to them. They then either cash it at a Post Office branch or pay it into their account, depending on whether the order is crossed. The Post Office's guidance describes postal orders as "a way to send money to someone, as a gift or payment"1.
Postal orders are a Post Office product, not a Royal Mail one, and the distinction matters when something goes wrong. The Post Office is the counter business where you buy and cash the order; Royal Mail is the delivery service that carries it to the recipient. As one consumer guide puts it, "The Post Office is a physical shop where you take your parcels to be sent off, but the parcels are delivered by Royal Mail"2. That is why a lost order is claimed from Royal Mail, while questions about buying or cashing one start at a Post Office branch.
The people who find postal orders most useful are often those who do not have a bank account, or who are dealing with someone who does not. Official guidance notes that people without a bank account can collect benefits or State Pension payments in cash at a Post Office or PayPoint outlet3, and can receive Universal Credit through vouchers swapped for cash at the same kinds of outlet4. For someone managing money that way, a postal order is one of the few ways to send a payment by post without either party needing an account. If you do have a bank account, a standing order is an instruction to your bank to pay a set amount to a person or organisation at regular intervals5, and is typically used for rent, charity donations and regular savings payments6. A postal order is the one-off, cash-based alternative.
Values from 50p to £250
Postal orders can be made out for any value from 50p up to £2501. That range covers small gifts, subscription payments and one-off bills, but it sets a hard ceiling: there is no postal order for £300 or £1,000, so larger sums need a different method.
The £250 limit shapes what postal orders are realistically used for. They suit small, occasional payments where the cost of the fee is proportionate and the convenience of not needing bank details matters more than the price. For anything larger, a bank transfer is usually the practical route if both sides have accounts, and for sending money to someone abroad there are international payment options that work at any amount. If the recipient is overseas, a postal order will not help at all, which is covered later in this page.
It is worth remembering that the fee is charged on top of the face value, so the total cost of sending £250 by postal order is the £250 plus the fee. The fee is not refunded if the order comes back unused, which is one reason the Post Office recommends crossing an order whenever possible1.
Postal order fees: 50p on small orders, 12.5% on larger ones
The Post Office's fee scale has two published bands1:
| Face value of the order | Fee |
|---|---|
| 50p to £4.99 | 50p |
| £10 to £99.99 | 12.5% of the face value |
The Post Office's page does not state the fee for orders between £5 and £9.99, so check at the counter before buying in that range. On the published bands, the fee is a flat 50p on the smallest orders and a percentage of the face value from £10 upwards, which means the charge grows with the amount you send.
The Post Office is explicit about what the fee is not: "It's an admin charge for the service, not a fee for insurance"1. In other words, the fee buys the printing and processing of the order, not protection against it going missing. Anyone choosing a postal order because they assume the fee includes some form of cover should set that assumption aside: the claims process for a lost order exists, but it is separate from the fee, and an uncrossed order that is stolen and cashed is treated like stolen cash.
For comparison, a bank transfer between UK accounts is typically free, and a standing order costs nothing beyond the money sent5. The postal order fee is the price of being able to send money through the post without either side having a bank account or sharing financial details1.
Buying a postal order at a Post Office
Postal orders are bought at a Post Office counter. You tell the branch the amount and the name of the person the order is for, pay the face value plus the fee, and the order is made out there and then.
The payee's name is not optional. The Post Office states that "The payee's name is always required on a postal order and can be printed if you wish"1. Getting the name right matters: a crossed order is paid through a bank account, so the name on the order and the name on the account need to match. If you are unsure of the exact name the recipient banks under, ask them before you buy.
The Post Office's guidance does not state which payment methods are accepted for buying postal orders, so check with your branch before relying on a particular card. The product is built around cash, and the branch counter is the only place to buy one: there is no online purchase route.
Keep whatever the branch gives you at the point of purchase, including any receipt or stub. If the order is lost in the post you will need the order details to make a claim, and if it is stolen you will need them to report it. Proof of posting matters for anything sent through the post: consumer guidance notes that without it, the operator may not pay compensation if your item is lost, damaged or delayed7.
Crossed or uncrossed: who can cash the order
Every postal order is either crossed or uncrossed, and the difference decides what the recipient can do with it. A crossed order has, in the Post Office's words, "two straight, vertical lines passing through it, just off centre. These are added electronically so it can't be cashed in branch"1. An uncrossed order has no such marks and can be handed over the counter for cash.
| Type of order | What the recipient can do with it |
|---|---|
| Uncrossed | Cashed at a Post Office branch, like cash1 |
| Crossed | Only paid into the recipient's bank account or savings account, or used to pay bills1 |
The Post Office's recommendation is unambiguous: "It is recommended that an Order is crossed whenever possible. A crossed Order will only be paid through a bank"1. The reason is security. An uncrossed order is "as good as cash. Like cash, they're also unsecure"1: whoever holds it can cash it. A crossed order, by contrast, can only reach the person named on it, because it has to go through their account.
The choice therefore depends on the recipient. If they have a bank or savings account, a crossed order is the safer option for anything sent through the post. If they do not have an account, an uncrossed order is the only kind they can use, and it needs to be treated as carefully as the same amount in banknotes.
Cashing or paying in a postal order
How the recipient converts the order into money depends on whether it is crossed. The Post Office states that "The Order may be cashed at a Post Office if it has not been crossed"1. A crossed order cannot be cashed in branch at all: "Crossed postal orders can only be paid into the recipient's bank account, savings account or used to pay bills"1.
For an uncrossed order, the recipient takes it to a Post Office counter and receives the face value in cash. Identity checks are not a formal requirement: "It's not a requirement to ask for proof of your identity if you're cashing a postal order. However, branch teams may ask you to show some ID as an extra precaution"1. Carrying something like a passport, driving licence or bank statement is sensible, since the branch can ask.
For a crossed order, the recipient pays it into their own bank or savings account, or uses it to pay a bill. This is where the payee's name matters: the order is made out to a named person, and it goes through an account in that name.
Postal orders are also accepted by official bodies, which is part of why they survive as a payment method:
| Who accepts them | How |
|---|---|
| HM Courts and Tribunals Service (bankruptcy petitions) | Cash, postal order or cheque; credit or debit card if you apply online8 |
| County courts (warrant of control fees) | Cheque or postal order payable to 'HM Courts and Tribunal Service'; card online for online claims9 |
| Student Loans Company (voluntary repayments) | Write your customer reference number on the back of the cheque or postal order and post it10 |
The common thread is that these are payments to named organisations, where the order is made out to the payee and sent by post. If you are paying a body like these, check its own guidance first: the payee name it requires, and in the Student Loans Company's case the reference number on the back, are part of making the payment work10.
When a Post Office will not cash a postal order
The clearest case is the crossed order. Because the crossing marks are added electronically at the point of issue, a crossed order cannot be cashed in branch no matter who presents it1. The recipient of a crossed order who wants cash has to pay it into a bank or savings account first, which means someone without an account cannot use a crossed order at all.
The other reason a branch may decline is identity. Although asking for ID is not a requirement, branch teams may ask for it as an extra precaution before handing over cash1. Someone arriving without any form of ID may find the branch refuses to pay out, even on a valid uncrossed order, because the discretion sits with the counter staff.
A recipient who is refused should first check whether the order is crossed: the two vertical lines just off centre are the tell-tale mark1. If it is uncrossed and the branch is still refusing, asking what the branch needs, whether ID or something else, is the practical first step. If the order is crossed and the recipient has no account, the sender may need to arrange a different payment method, since a crossed order cannot be converted to cash at a counter.
Where postal orders do not work
Postal orders are a UK domestic product. The Post Office's own guidance is blunt on the point: "You need to pay for goods and services outside the UK" and should consider something else1. A UK postal order cannot be used to pay a seller abroad, and it is not a substitute for an international payment.
For money leaving the UK, the options are different in kind: international payments through a bank or specialist provider, ways to send abroad including cash collection services, or cash pickup abroad where the recipient collects money in person without needing an account. Those routes exist precisely because a postal order stops at the border.
Postal orders are also not a bank account substitute for everything. The Post Office itself is not a current account provider: the Financial Conduct Authority has confirmed that "the Post Office has not designated (and cannot be, as it is not a relevant current account provider)" under the rules requiring wider banks to protect access to cash11. A postal order is a one-off payment instrument, not a place to receive wages or regular income. Someone who needs an account to receive money, but who has struggled to open one, can look at a basic bank account, where you will need to show proof of identity and address, and can ask the bank what alternatives it accepts if you lack the usual documents12. Credit union current accounts are another route, usually requiring two recent documents to prove identity and address, which can include a passport, driving licence, student or work ID card, bus pass, birth certificate, bank statement or energy bill13.
Lost or stolen postal orders: what to do
What you do depends on how the order went missing. If it was lost in the post, the process runs through Royal Mail: you make a P58 claim, but you must wait, because "You'll need to wait 15 days after posting before you can do that"1. The claim is for the order lost in the post, and the order details from your receipt are what you will need to make it.
If the order was stolen, the route is different and starts with the police. The Post Office's instruction is: "If your postal order is stolen, please report it to the police and get a Crime Reference Number, as the police will need to contact us with this"1. The Post Office acts on the stolen order once the police make contact with the reference number, which is why getting that number is the essential first step rather than a formality. Theft of delivered items is a crime in general terms, and consumer guidance directs people who think a delivery has been stolen to contact the police14.
Reports of lost or stolen post are handled by Royal Mail, which takes reports by telephone on 08457 740 74015. That line covers post that has gone missing or been stolen in transit, which is the relevant route when a posted order never arrives and the 15-day wait has passed.
Because an uncrossed order is as good as cash, prevention matters more than cure. Crossing the order before sending means it can only be paid into the named recipient's account1, which removes most of the value of stealing it. Keeping proof of posting also matters: without it, the operator may not pay compensation if your item is lost, damaged or delayed7.
If a postal order goes missing alongside other documents, the wider identity-theft precautions apply. Official guidance lists lost or stolen important documents, such as a passport or driving licence, among the signs of identity theft17, and recommends reporting lost or stolen documents to the issuer, checking bank statements and your credit report, watching for phishing, using strong passwords and multifactor authentication, and applying for Cifas protective registration18. A postal order carries a payee's name rather than a full set of financial details, so it is less of an identity risk than a bank card, but the same basic steps apply if a batch of post goes missing.
Protections and where they stop
Postal orders sit outside most of the protections that surround bank payments, and it is worth being clear about where the line falls.
The fee is not insurance. The Post Office states plainly: "It's an admin charge for the service, not a fee for insurance"1. There is no cover built into the purchase price against the order being lost or stolen, and an uncrossed order that is stolen and cashed behaves like stolen cash. The protections that do exist are procedural rather than financial: the P58 claim for post lost in transit, available after 15 days1, and the police route with a Crime Reference Number for stolen orders1.
Contrast that with bank payments. Under the Payment Services Regulations, when a payment from your account is unauthorised, the payment provider must "refund the amount of the unauthorised payment transaction to the payer and, where applicable, restore the debited payment account to the state it would have been in had the unauthorised payment transaction not taken place"19. That refund right belongs to payments made from a regulated account, not to cash handed over a counter for a paper instrument. Even within banking, protection has limits: a standing order paid to the wrong details is not protected, which is why guidance stresses checking the information before sending6.
The practical protections for a postal order are therefore the ones you create yourself:
- Cross the order whenever possible, so it can only be paid into the named recipient's account1.
- Write the payee's name correctly, since a crossed order is paid through a bank in that name1.
- Keep your receipt and proof of posting, which are what you need for a P58 claim and what parcel and post operators may require before paying compensation1.
- Treat an uncrossed order as cash, because that is exactly how the Post Office describes it: as good as cash, and as unsecure1.
If a dispute arises about a related bank payment rather than the postal order itself, complaints about banking and payments can be taken to the Financial Ombudsman Service once the provider has had the chance to resolve them5. For the postal order itself, the Post Office branch and Royal Mail's reporting line are the starting points, and the police for theft1.
Sources19 cited
- Postal orders Post Office, 2026
- How to spot a dodgy Post Office delivery text Which?, 2022-11-30
- What to do now your Post Office card account is closing MoneyHelper, 2026-09-25
- Choosing a bank account for your Universal Credit payment MoneyHelper, 2026-09-25
- Regular payments: banking and payments complaints Financial Ombudsman Service
- Direct debits and standing orders explained Which?, 2026-03-05
- Online shopping and parcel delivery rights Consumer Council
- Apply to bankrupt someone GOV.UK, 2026-09-27
- Apply for a warrant of control GOV.UK, 2026-05-28
- Repaying student loans more quickly and getting refunds nidirect, 2026-06-04
- PS24/8: Access to cash policy statement Financial Conduct Authority, 2024-07
- Make your money easier to manage by yourself MoneyHelper, 2026-09-25
- Credit union current accounts MoneyHelper, 2026-09-25
- My delivery or online order hasn't arrived: what can I do? Which?, 2026-04-14
- Protect your identity nidirect, 2025-10-28
- Identity theft Information Commissioner's Office, 2026-09-25
- Identity theft Information Commissioner's Office, 2026-09-25
- What steps can I take if I've been affected by a personal data breach? Information Commissioner's Office, 2026-09-25
- Payment Services Regulations 2017, Part 7 legislation.gov.uk, 2017



 MoneyHelperFree, impartial money and pensions guidance, set up by government
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 FCA Warning ListCheck whether a firm is authorised before you deal with it
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales