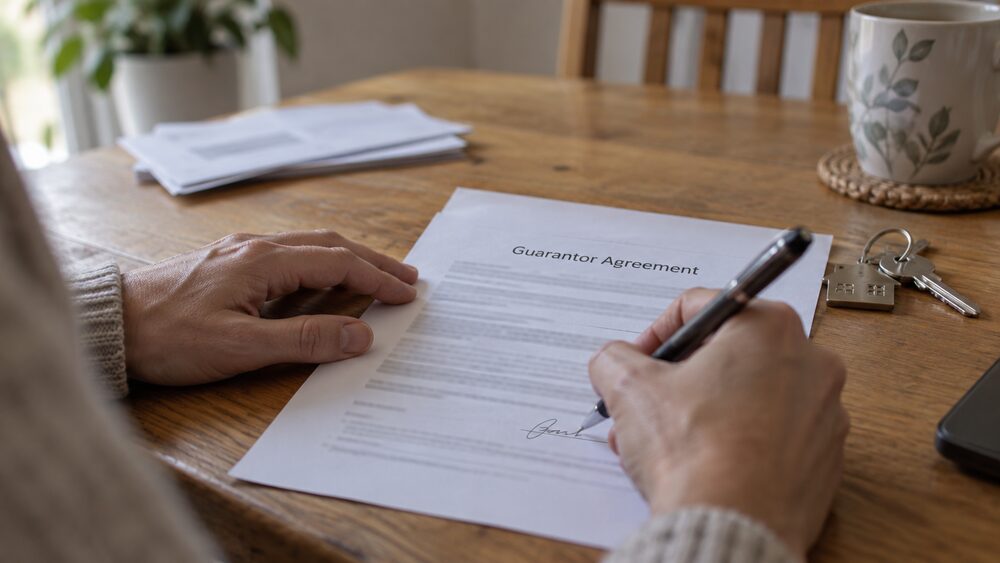
A guarantor loan is a loan that a lender will only give if another person, usually a friend or family member, guarantees to make the payments if the borrower does not1. The lender agrees to lend the money based on the guarantor being able to repay the loan in full, not just on the borrower's own finances2. That single feature is what makes these loans different from ordinary personal loans: the lender is really relying on the guarantor.
Guarantor loans are usually marketed at people who have bad credit or who were turned down by other lenders2. They can be an option for someone with a poor or thin credit history, but they often carry higher interest rates than other types of credit, and the interest can mean the borrower pays back more than they borrowed3. For the guarantor, the commitment is serious: if the borrower stops paying, the guarantor may become liable to pay back everything that is owed, not just the missed payments2.
How a guarantor loan works
The structure is simple. A borrower applies, but the lender's decision rests on the guarantor's ability to repay the loan in full2. In many cases the loan money is paid to the guarantor first, into the guarantor's bank account, and the guarantor then passes it on to the borrower4. This route exists partly to confirm that the guarantor knows the loan has gone ahead.
While the borrower keeps up the repayments, the guarantor does nothing and pays nothing. The guarantee only comes into play if the borrower fails to pay, at which point the guarantor is legally liable to pay back the loan for them3. Larger guarantor loans take several years to pay back, so the commitment is not a short one2.
Guarantor loans are a type of consumer credit, regulated by the Financial Conduct Authority (FCA)2. Under the FCA's consumer credit rules, a guarantor is an individual other than the borrower who has provided a guarantee or indemnity in relation to a regulated credit agreement, and the rules that protect borrowers generally extend to guarantors too7. That means guarantors are not left outside the regulatory perimeter: they have their own rights, including the right to complain, covered later on this page.
The same guarantee idea appears in other products. A guarantor mortgage is a home loan where a parent or close family member takes on some of the risk, usually by offering their home or savings as security and agreeing to cover the mortgage payments if the borrower defaults8. Rent guarantors work similarly for tenancies: the guarantor pays the rent if the tenant does not. This page focuses on guarantor loans, but the principle of the commitment is the same across all of them.
Who can borrow and who can be a guarantor
Borrowers must be at least 18 years old4. Guarantor loans tend to suit people with a bad credit score or no credit history at all, such as students just starting out or people new to the country, because the lender's assessment turns on the guarantor rather than the borrower's record3. They are usually marketed at people who either have bad credit or were turned down by other lenders2.
Guarantors face a longer list of conditions:
- They are usually a friend or family member of the borrower2
- They must not usually be financially connected to the borrower, such as a spouse or partner4
- They need a separate bank account to the borrower3
- In general they must have a good credit history, be at least 21 years old (18 in some cases), and live in the UK, in case the lender needs to take legal action3
- The guarantor must prove they can afford the repayments, based on their income, savings and any assets2
- The lender might also ask for proof that they are working, proof of income, or that the guarantor is a homeowner3
The rule on partners deserves attention. You can guarantee a loan for a spouse or partner, but only if you have separate bank accounts9. Because most couples share finances, lenders usually treat a spouse or partner as financially connected and rule them out, which is why the typical guarantor is a parent, another relative or a friend4. Creditors sometimes require the guarantor to be a homeowner to demonstrate that they have assets to potentially cover the debt4.
Before the agreement is made, the lender will run a credit check on the guarantor. This is usually a soft check, which is not visible to other companies and does not affect the guarantor's credit score3. The check is still added to the guarantor's credit file10. The FCA's rules extend borrower protections to guarantors: references to a borrower, customer or hirer include a guarantor who has provided a guarantee or indemnity in relation to a regulated credit agreement7, a rule most recently updated on 15 July 202611.
Costs: high interest, default fees and total repayable
Guarantor loans can be more expensive than some other types of credit because they often have higher interest rates3. The interest could mean the borrower pays back more than they borrowed2, and because larger loans take several years to pay back, the total interest has a long time to build2. Before taking out any loan, official guidance suggests checking the repayment length and total cost, whether the interest rate can change, the monthly repayments and any penalties for missing one, any early repayment costs, and what happens if the loan is secured on a home12.
Fees can add to the bill. Interest and charges are added to repayments, and there may be other charges like set-up fees or early repayment fees2. For payday loans, a form of high-cost short-term credit, default fees, the amount that can be charged if the loan is not paid back on time, are capped at £15.0013. Guarantor loans sit outside the payday price cap, but the payday cap shows how regulators treat default charges in the high-cost credit market more broadly.
The practical point for both people is to look at the total repayable, not the monthly payment. A monthly amount that looks manageable can add up to far more than the sum borrowed over a multi-year term. The guide to how loan interest is calculated explains how the figures build up, and loan fees and charges covers the other costs to check before signing.
Credit unions: loans funded by members' savings
A lower-cost alternative exists in the credit union sector. Credit unions are member-owned financial co-operatives: all of them offer savings and loans14, and members' savings are used to fund loans to other credit-worthy members of the credit union15. Some credit unions offer guarantor-style products where the loan is backed by savings rather than by a friend's promise, which changes the risk for everyone involved.
Deposits carry protection. Loans and savings at credit unions are protected by the Financial Services Compensation Scheme16, and all shares, meaning savings, in affiliated credit unions are eligible for FSCS protection15. That protection covers the savings side of the arrangement, not the loan itself, but it means a guarantor whose money sits in a credit union is not exposed to the institution failing.
For a borrower weighing a guarantor loan against other routes, credit union borrowing and the comparison of payday lenders and credit unions set out the differences in cost and structure. Free debt advice charities also point borrowers towards affordable credit before high-cost options: the choice between a consolidation loan or free debt advice is worth making before borrowing more.
What being a guarantor commits you to
Being a guarantor means agreeing to repay the amount owed if the borrower cannot, and being responsible for any debts in the agreement9. The person guaranteeing the loan is jointly responsible for dealing with the debt: one person has to pay if the other cannot2. This is not a character reference or a favour in name only. It is a binding legal obligation to pay back what they owe17.
The law recognises how significant this is. FCA rules require that, before making a deferred payment credit agreement with a guarantor, the firm must provide the guarantor with an adequate explanation of when the guarantee or indemnity might be called on and the implications, plus the necessary product information18. These explanation rules date from 2 November 2015, with additional explanation requirements for guarantor agreements introduced on 12 September 201918. In plain terms, the lender cannot simply collect a signature: it must spell out to the guarantor what they are signing up to.
Official guidance goes further for anyone considering guaranteeing a mortgage: get independent legal advice, and talk to a mortgage adviser, before agreeing to it19. That advice applies equally well to guarantor loans. A guarantor should read the agreement, understand the total amount they could be asked to pay, and check their own budget against that figure, not just against the borrower's monthly payment.
The commitment also lasts as long as the loan does. Larger loans take several years to pay back2, and there is no cooling-off period that releases a guarantor once the money has been paid out. The only guaranteed exit is the loan being repaid or settled; otherwise the guarantor depends on the lender agreeing to a release, or on a successful complaint.
Missed payments: when the guarantor has to pay
If the borrower misses payments, the guarantor will need to pay instead6. If the borrower fails to make payments, the guarantor is legally liable to pay back the loan for them3. Depending on the terms of the agreement, the guarantor may become liable to pay back everything that the borrower owes, not just the payments that have been missed20. That distinction matters enormously: a guarantee limited to arrears is a smaller exposure than one covering the whole outstanding balance.
A default is recorded on both people's credit files2. Payments the guarantor makes on the borrower's behalf are added to the guarantor's credit history and could reduce their credit score3. The narrow guide to what a guarantor pays when the borrower misses payments works through the mechanics, and how a guarantor loan default affects your credit file covers the record itself.
Guarantors have their own protections here. The FCA's rules on continuous payment authorities apply to a guarantor who has granted one, as if references to the customer were references to the guarantor23. So a guarantor who has set up a recurring card payment to the lender can use the same rights to cancel it as a borrower can, through the process in how to stop a continuous payment authority.
The Financial Ombudsman Service receives complaints about guarantor loans from borrowers and guarantors1. When a guarantor complains about being asked to make payments, the ombudsman looks at whether the lender completed reasonable and proportionate checks before it lent to the borrower and agreed to the guarantor, and whether it obtained the guarantor's agreement1. The checks lenders must make on both people are covered in loan affordability checks and credit checks on a guarantor.
Secured guarantor loans and the risk to a home
Some guarantor loans are secured against the guarantor's property2. If the loan is secured and the repayments are not kept up, the guarantor's house could be at risk of repossession2. A secured loan effectively becomes a second mortgage on the home, and the home can be repossessed if the payments cannot be kept up20. Even an unsecured arrangement carries the risk that a lender takes court action to recover the debt from a guarantor who owns property.
The same warning applies to guarantor mortgages. A guarantor mortgage usually involves the family member offering their home or savings as security and agreeing to cover the mortgage payments if the borrower defaults8. In the worst-case scenario, if the lender repossesses and sells the property for less than the amount remaining on the mortgage, the guarantor could be liable for any shortfall8. Which? gives a worked example: if the borrower owed £150,000 but the lender recovered only £125,000 by repossessing and selling, the £25,000 difference could be taken from the guarantor's savings or property8.
Guarantor mortgages can enable a buyer to take out a 100% loan, with no deposit, because the family member's security stands behind it24. That can help a borrower with a low income, a small or no deposit, a bad credit score or little credit history8, and retired parents can often act as guarantors because the security comes from their savings or property rather than their employment8. But the trade-off is the shortfall risk above. The comparison of secured and unsecured borrowing sets out the difference in what the lender can take if things go wrong, and missing secured loan repayments covers the arrears process.
If the borrower enters a debt solution
This is the point that surprises most guarantors. If the borrower enters into an arrangement with creditors, formal or informal, the loan company will default the loan and contact the guarantor to maintain the original repayments4. The borrower's debt may be reduced or written off under the arrangement, but the guarantor's obligation is untouched.
Guarantor loan debts can be included in most debt solutions, like debt management plans and bankruptcy10. But inclusion only affects the borrower's liability. In a formal solution such as bankruptcy, a debt relief order or an individual voluntary arrangement, the borrower's liability for the debt is included in the arrangement, however the guarantor is still fully liable and expected to maintain the original repayments4. If the arrangement is informal, such as a debt management plan, the borrower is still liable for the debt, and the loan company can continue to take action against the borrower if the guarantor does not maintain the original repayments4.
For the borrower, the right move is to tell the guarantor before entering any solution, not after. Free debt advice is available from charities such as StepChange and National Debtline, and the debt section explains the solutions and their effects. For the guarantor, the position is stark: the debt does not go away because the borrower entered a solution, and the guarantor may need their own debt advice if the repayments are unaffordable for them.
Complaints about unaffordable guarantor loans
Both people can complain. The Financial Ombudsman Service receives complaints about guarantor loans from borrowers and guarantors1. When agreeing to the loan, lenders need to make sure the borrower can afford the repayments without too much trouble, and if the loan is complained about as unaffordable, the lender must show what checks it did1. The ombudsman sees complaints about unaffordable lending across a range of credit products, from car finance to payday lending26, and consumers who feel they were given unaffordable credit, or that the lender acted irresponsibly, may be able to complain27.
The numbers show this is a live issue. In Q3 2025/26 the ombudsman recorded 21 new guarantor loan complaints28. In Q1 2025/26, guarantor loan complaints had a 52% uphold rate5, meaning the ombudsman found in the consumer's favour in more than half the cases it decided. For scale, personal loans drew 2,103 new complaints in Q1 2026/2729. A guarantor is an eligible complainant to the ombudsman, but only to the extent that the complaint arises from matters relevant to the guarantee or security relationship with the lender30.
What redress looks like depends on who should never have been involved:
- If the borrower should never have been given the loan: the ombudsman typically tells the lender to refund any interest and charges paid, with interest, and remove any adverse information recorded on the credit file. If a balance remains, all interest and charges are usually removed so the balance is only what was lent, minus payments already made, with any overpayment refunded with interest1. The ombudsman will usually say it is fair for the borrower to pay back the remaining balance, though in some rare instances it may not think this is fair1.
- If the guarantor should never have been accepted: the ombudsman will usually say the guarantor should be released from the guarantee, with any payments already made refunded with interest, and any information added to the guarantor's credit file removed1.
A published case study shows the approach in practice. Steve and Laura complained that a secured loan was unaffordable, and the ombudsman did not think the lender's checks were sufficient in verifying their expenditure31. Refunds in unaffordable lending cases can include interest added to the loan, charges added when the borrower could not repay on time, and an extra 8% interest if the complaint goes to the ombudsman32.
One boundary: the ombudsman's guarantor loan page does not cover complaints by guarantors of loans to businesses1. A business that is a micro-enterprise or small business and guaranteed a business loan can complain, but a personal guarantee for your own business is eligible only if it was given on or after 1 April 201933. The process for complaining is in complaining about a lender and complaining your guarantor loan was unaffordable.
Pressure to be a guarantor is financial abuse
If a partner or family member is pressuring someone to act as a guarantor for a loan, this is financial abuse3. It is a point official guidance makes plainly, and it matters because the guarantor's signature is what the lender needs: pressure applied behind closed doors can produce a legally binding guarantee that the person never freely chose.
The ombudsman has published a case study of exactly this. Nadia had been forced to take out several guarantor loans by a family member who was verbally and physically abusing her. Cases like hers are why the ombudsman examines whether the lender obtained the guarantor's agreement and made proportionate checks before accepting them1.
Anyone in this position can also read debts not in my name for related situations, and owing on a guarantor loan you never signed where the signature itself is in question. Free debt advice from StepChange, National Debtline or Business Debtline, and the guidance on what to do if you can't repay a loan, are open to guarantors as well as borrowers.
Sources33 cited
- Guarantor loans Financial Ombudsman Service, 2026
- Guarantor loan debts StepChange Debt Charity, 2026
- Guarantor loans explained MoneyHelper, 2026
- Payday, guarantor and doorstep loans Advice NI, 2026
- Quarterly complaints data Q1 2025/26 Financial Ombudsman Service, 2025
- Budgeting, saving and borrowing Business Debtline, 2026
- CONC 7.1 FCA Handbook, 2026
- Guarantor mortgages Which?, 2026
- Debt solutions and your home StepChange Debt Charity, 2026
- Being a guarantor StepChange Debt Charity, 2026
- CONC 7 (archived) FCA Handbook, 2026
- Consolidating debts nidirect, 2025
- Payday loans nidirect, 2026
- Credit unions Building Societies Association, 2026
- About credit unions Ulster Federation of Credit Unions, 2026
- Save, bank or borrow with a credit union Welsh Government, 2026
- Debts not in my name StepChange Debt Charity, 2026
- CONC 4 FCA Handbook, 2026
- Dividing the family home and mortgage during divorce or dissolution MoneyHelper, 2026
- Debt consolidation guide (Scotland) National Debtline, 2026
- Debt consolidation guide (England and Wales) National Debtline, 2026
- Debt consolidation Business Debtline, 2026
- CONC 6.7 FCA Handbook, 2015
- Negative equity Which?, 2026
- What is a mental health breathing space Mental Health and Money Advice, 2023-07-09
- Unaffordable lending Financial Ombudsman Service, 2026
- Research briefing CBP-8810 House of Commons Library, 2026
- Quarterly complaints data Q3 2025/26 Financial Ombudsman Service, 2025
- Quarterly complaints data Q1 2026/27 Financial Ombudsman Service, 2026
- DISP 2.7 FCA Handbook, 2019
- Steve and Laura complain a secured loan was unaffordable Financial Ombudsman Service, 2026
- Payday loans guide Business Debtline, 2026
- Who we can help Financial Ombudsman Service, 2026



 MoneyHelperFree, impartial money and pensions guidance, set up by government
 StepChangeFree debt advice and solutions from a charity
 National DebtlineFree debt advice by phone, webchat and online
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales