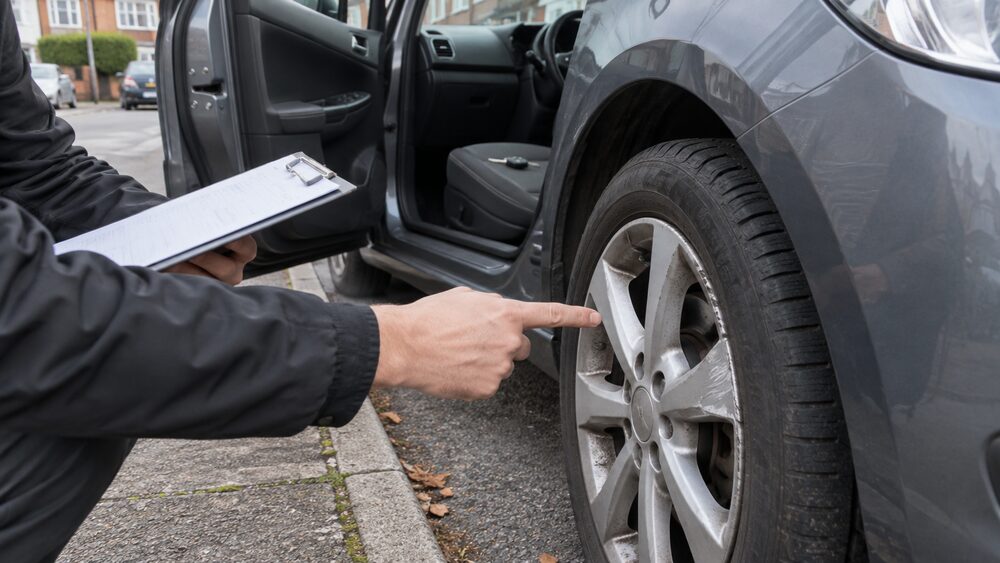
Handing a PCP car back at the end of the agreement costs nothing if the car is in good condition and within its mileage limit. If either of those is not true, the finance company can charge you: an excess mileage charge for every mile over the agreed limit, and a wear and tear charge for damage beyond what the industry regards as fair. Both are payable when you return the car, not when you buy it.
Handing a PCP car back at the end of the agreement costs nothing if the car is in good condition and within its mileage limit. If either of those is not true, the finance company can charge you: an excess mileage charge for every mile over the agreed limit, and a wear and tear charge for damage beyond what the industry regards as fair. Both are payable when you return the car, not when you buy it.
The mileage rate is set out in your finance agreement, and independent guidance puts the typical figure at around 10p per extra mile. That is a market figure, not a rule, and the rate in your own contract is the one that applies. The condition standard is usually the BVRLA wear and tear guidelines, which several manufacturers name directly in their PCP terms.
The reason the finance company can charge at all is that the car is not yours until the agreement is settled. With PCP the loan is secured against the car, and you cannot sell it privately while the finance is outstanding. That single fact explains the mileage cap, the condition rules and the charges that follow from breaking either.
Excess mileage charges when you go over the agreed limit
You agree an annual mileage limit at the start of the contract, and the lower that limit is, the lower your monthly payment. That trade-off is the whole point of the arrangement: the finance company is estimating what the car will be worth when you hand it back, and a car with more miles on it is worth less. If you exceed the agreed limit, you pay the difference through an excess mileage charge.
Lloyds Bank and Bank of Scotland both state plainly that if you have exceeded the agreed mileage allowance on return of the car, you will need to pay an excess mileage charge. Halifax says charges may apply if you go over the agreed mileage limit and want to return the car. Toyota's wording adds the condition that matters most: the charge is payable at the end of the finance agreement if you exceed the agreed mileage and choose to return the car7.
That last point is the one people miss. The excess mileage charge is payable only if the vehicle is returned, not if you buy it. A driver who blows through the limit and then pays the optional final payment to keep the car does not pay it, because the car is not going back6.
On the rate itself, independent guidance from Which? puts the typical cost at around 10p per extra mile, and gives the arithmetic: underestimating your mileage by 3,000 miles a year on a four-year contract is 12,000 extra miles2. The rate in your own contract governs, and it can be higher or lower than the typical figure.
Damage and wear: when you pay extra on return
Condition charges work on the same principle as mileage: the finance company expected the car back in a certain state, and it is worth less if it is not. The standard is not "spotless". It is fair wear and tear, and the usual reference point is the BVRLA wear and tear guidelines, which set out what counts as acceptable for a car of a given age and mileage.
Manufacturer PCP terms name that standard directly. Volkswagen Financial Services states that returning the car is subject to being within BVRLA wear and tear guidelines, and that if there is any excess mileage, charges will apply. SEAT's PCP terms use the same wording, and Porsche's product information guide repeats it3. Close Motor Finance puts it in consumer terms: you may need to pay additional charges if you drive more miles than the agreed annual mileage or the vehicle is damaged beyond fair wear and tear standards11.
What falls on the wrong side of the line is the familiar list: excessive wear and tear, scratches and worn tyres. Those are the items the Post Office names as triggering extra fees on return12. Experian's guidance on leasing describes the same idea, noting that a car that is scuffed up at the end of the agreement may attract an excessive wear and tear fee13. The same logic applies to motorbike finance, where returning a bike with excess wear and tear can incur fees14.
The practical distinction is between damage and deterioration. A stone chip, a kerbed alloy or a worn tyre at the end of a three-year contract is normally expected. A cracked bumper, a torn seat or a tyre below the legal tread limit is not. Photographs taken before the car is collected, and a copy of the condition report, are the evidence that matters if a charge is disputed.
Return, pay the final payment or trade in: how each option affects charges
At the end of a PCP there are three routes, and they do not carry the same charges. Experian sets them out as paying the balloon payment and buying the car, giving the car back, or part exchanging for a new car15. Zopa describes the same three: return the car, part exchange it for a new one, or pay an optional final payment to own the car outright16. HSBC's electric vehicle guidance frames it as returning the car, paying a lump sum to purchase it outright, or using the equity towards another car on PCP17.
| End of agreement option | Excess mileage charge | Wear and tear charge | What happens |
|---|---|---|---|
| Return the car | Yes, if over the limit | Yes, if beyond fair wear and tear | Nothing further to pay if within both1 |
| Pay the optional final payment | No | No | You own the car outright16 |
| Part exchange for a new car | Depends on the deal | Depends on the deal | Equity, if any, goes towards the next car15 |
The pattern is straightforward. Charges exist to protect the finance company's estimate of the car's value at the end of the contract. If the car comes back worth less than expected, the difference is recovered from you. If you buy the car, there is no resale to protect, so the mileage charge falls away. Part exchange sits in between and depends on what the dealer offers against the outstanding finance.
One small cost sits on the buying route rather than the returning route. Porsche's PCP terms state that you can simply return the car and pay a £10 option to purchase fee, which is the charge for exercising the right to buy rather than a penalty for anything10.
Why the lender can charge you: the car is theirs until the end
The charges are not arbitrary. They follow from who owns the car while the agreement runs, and the answer is the finance company. Vehicles bought on hire purchase, PCP or conditional sale are not fully owned by you until you have made the last payment to the finance agreement5. Zable's consumer guidance puts it the same way: with most types of car finance, the finance is secured against the car, which means the lender owns it until you have paid off the agreement18.
That is why a private sale is not possible. For finance options like PCP or HP, you will not have complete ownership of the car until all payments are finalised, and for that reason a private sale is not legally permissible14. StepChange states it flatly: you cannot sell a car on PCP as it does not belong to you4. First Direct's comparison of car loans and finance makes the same point from the other direction, noting that you cannot sell the car without settling the finance before the term is up19.
Because the car is security, the finance company also has remedies if payments stop. Under a PCP agreement the creditor may be able to repossess the vehicle without getting a court order first, because less than a third of the total amount payable may have been paid before the end of the agreement20. That is a serious consequence and it is worth knowing before arrears build up. If payments have become unaffordable, free and impartial help is available from StepChange and National Debtline, and returning the car early is one option, though it can leave you with more to pay than seeing the agreement out4.
What protects you, and where it stops
The main protection is the condition standard itself. A finance company cannot charge for ordinary use, only for damage beyond fair wear and tear, and the BVRLA guidelines give a benchmark for what that means at a given age and mileage3. If a charge looks wrong, the first step is the condition report and the finance agreement's own mileage rate.
There is also a route to complain. The Motor Finance Redress Scheme covers hire purchase agreements such as Personal Contract Purchases, which is the scheme consumers can use where commission arrangements on car finance are in question22. Separately, a car bought on finance and rejected within the cooling-off period is handled by the finance company rather than the dealer: the finance company has to terminate the agreement and pay back your deposit plus any payments you have already made, minus deductions for fair usage23.
Where the protection stops is at the mileage limit and the condition standard. Those are contractual terms you agreed to, and going over either is not a mis-selling issue. The mileage rate is in the agreement, the condition standard is published, and the charge follows. The one firm rule worth holding on to is that the excess mileage charge is payable only if the vehicle is returned, not if you buy it, so a driver facing a large mileage bill has a genuine choice about which route to take6.
Sources23 cited
- Personal Contract Purchase Halifax, 2026-09-27
- Car finance explained Which?, 2026-07-21
- PCP Product Information Guide Volkswagen Financial Services, 2026-02
- Car finance debt StepChange, 2026-09-25
- What can bailiffs take StepChange, 2026-09-25
- Personal finance glossary Toyota, 2026-09-26
- Car finance refinance Lloyds Bank, 2026-09-27
- Car finance refinance Bank of Scotland, 2026-09-27
- Personal finance Toyota, 2026-09-26
- PCP Product Information Guide Porsche Financial Services, 2025-08
- Personal contract purchase Close Motor Finance, 2026
- Guide to car finance Post Office, 2026-08-12
- Types of car finance Experian, 2026
- Car finance Advice NI, 2026-09-26
- Personal contract purchase Experian, 2026
- Difference between an unsecured car loan, hire purchase, personal contract purchase and car finance Zopa, 2025-12-16
- Financing electric cars HSBC, 2026
- Car finance Zable, 2026-09-25
- Car loan vs finance first direct, 2026
- Car repossession: what happens and what you can do about it National Debtline, 2026-09-25
- Hire purchase debt Business Debtline, 2026-09-26
- Motor finance redress scheme Consumer Council for Northern Ireland, 2026
- Is there a 14 day cooling off period when buying a car Which?, 2026-09-27










 MoneyHelperFree, impartial money and pensions guidance, set up by government
 StepChangeFree debt advice and solutions from a charity
 National DebtlineFree debt advice by phone, webchat and online
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales