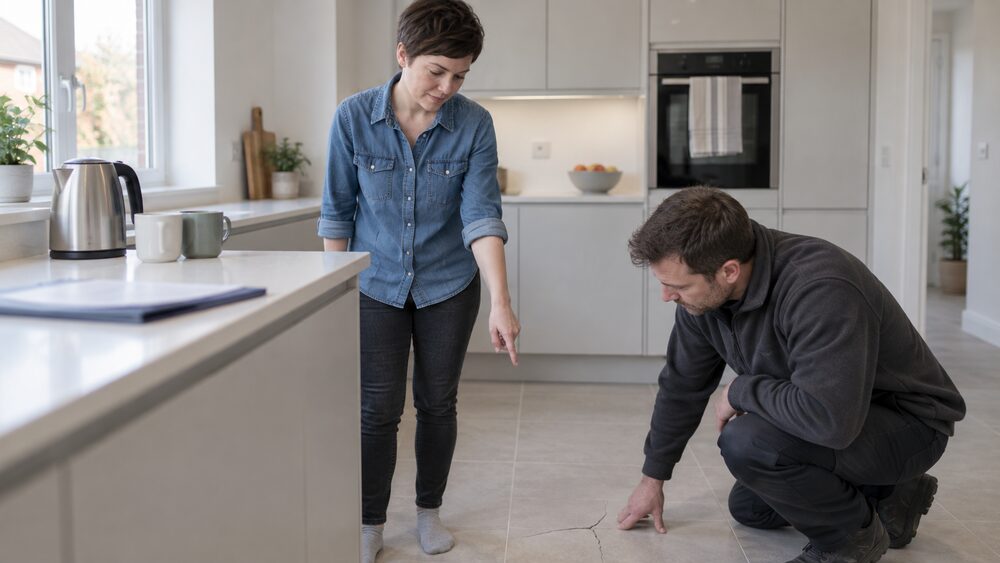
A new build home can come with problems the developer needs to put right, from snagging items left unfinished to more serious defects. The good news is that you do not have to rely on the developer's goodwill alone. Every route to redress starts in the same place: a formal complaint to the developer itself, made in writing and kept on file. Only once that process has run its course, or stalled, do the free independent schemes become available to you.
Two kinds of protection sit alongside each other. Consumer codes, including the New Homes Quality Code, cover the sale and the developer's service, and the New Homes Ombudsman was established to support people who have purchased a new build home and are in dispute with the developer they bought from, at no cost to the consumer1. Separately, a structural warranty covers the building itself, and complaints about a warranty provider can go to the Financial Ombudsman Service, which is also free3.
This page explains each step in order: how to complain to the developer, who can use the ombudsman schemes, how long each stage takes, what the deadlines are, what compensation is possible, and what to do if you disagree with the final decision.
Start with the developer's own complaints process
Whatever has gone wrong, the first step is always the same: complain to the developer directly and use its own internal complaints procedure. This is not a formality. The general principle across UK consumer redress is that anyone with a complaint who wants redress must, as a first step, use the trader's own internal complaints procedure4. The independent schemes exist to review complaints the trader has failed to resolve, not to replace the trader's process, and they will normally want to see that you gave the developer a fair chance to respond.
Put the complaint in writing, even if you have already raised the problem by phone or on site. Set out what is wrong, when you noticed it, what you have already asked for, and what you want the developer to do. Keep copies of everything you send and every reply you receive, with dates. If your complaint is about several different problems, list them all in one place: a single written record of the defects and the developer's responses is what any later scheme will read.
Developers registered with the New Homes Quality Board must, once they activate their registration, follow the Code's rules and standards, which include handling complaints properly2. If your complaint is about the process of the sale itself and the builder or developer has not addressed it, you contact the relevant consumer code. The code that applies to your home is available through the builder or developer, or in the welcome pack supplied when you bought the home2. A new home built by a developer registered with LABC Warranty and covered by a New Homes Warranty, for example, is covered by one of two consumer protection codes2.
The same complain-first principle runs through every redress scheme in the UK. The Information Commissioner's Office tells people unhappy with how an organisation handled their request that they should first complain to that organisation8. The Financial Ombudsman Service says the same about equity release: first explain to the company what you are unhappy about and why, and only if you are not happy with the response do you bring the complaint to the ombudsman9. The Pensions Ombudsman likewise requires a formal complaint first to the party concerned, such as the trustees or administrator10. The pattern is consistent, and it applies to new build disputes too.
Who can use the New Homes Ombudsman Service
The New Homes Ombudsman was set up to support people who have been able to purchase a new build home and are having disputes with the developer they purchased from1. In practice that means the buyer of the home: the person or people named on the purchase who are dealing directly with the developer. The service is free to consumers1, so there is no charge for bringing a dispute to it.
A few practical points about who can complain, drawn from how comparable schemes work. Where a complaint involves someone who lacks capacity, or who has appointed someone else to act for them, ombudsman schemes generally allow the complaint to be brought by that person or by their attorney acting on their behalf11. So if a family member bought the home but is unable to manage the complaint themselves, another person with the legal authority to act for them can normally bring it.
In Wales, the arrangements have a specific feature worth knowing. The legislation allows for the functions of the New Homes Ombudsman to be removed or modified by the Senedd without the need for consent from a UK Government Minister1. In plain terms, the scheme's future shape in Wales rests with the Welsh Parliament, so the details of how the service operates there can change by devolved decision rather than only by UK Government action.
If your developer is not registered with the New Homes Quality Board, or has not activated its registration, the Code's complaint route may not be available for your home, because the obligation to follow the Code's rules and standards applies once a registered developer activates its registration2. That does not leave you without options. Your structural warranty still covers the building, and a complaint against the warranty provider can be taken to the Financial Ombudsman Service3. The wider guide to complaining when buying a home goes wrong covers the other routes, including complaints about estate agents and conveyancers.
Waiting for the developer's reply before escalating
Once you have complained in writing, the developer needs time to investigate and respond. The standard used across financial services complaint handling gives a firm 8 weeks from receipt of a complaint to send a written response5. That is the benchmark the ombudsman schemes work to when they decide whether a complaint is ready to be escalated. If you receive a final response sooner and you are unhappy with it, you do not have to wait the full period.
Some schemes set tighter deadlines for the firms they cover. For certain categories of complaint, the rules require a final response within 15 business days of receipt, and in exceptional circumstances a holding response within 15 business days and a final response within 35 business days5. The deadlines that apply to your developer depend on which code and scheme covers your home, so check the code documents in your welcome pack.
The waiting period before a consumer can refer a complaint on has itself been criticised where it is long. A Scottish consumer body reviewing the Energy Ombudsman noted that the existing waiting time of 8 weeks is too long12. That criticism is about a different sector, but it shows the 8-week window is a recognised standard, not a rule unique to new build disputes, and that it is the outer limit rather than a target.
While you wait, keep building the record. Photograph defects, date everything, and note every phone call. If the developer asks for access to inspect or repair, keep a note of what was agreed and what was done. If the 8 weeks pass with no adequate written response, or you get a final response that does not resolve the problem, the next stage opens.
Time limits: the two-year builder period and the ombudsman deadlines
New build complaints run on two separate clocks, and it pays to know both. The first clock is set by your structural warranty. Building warranties cover major problems with newly built or converted homes3. Under the first part of the warranty, the builder must sort out problems in the first two years after the building is complete, and the insurer usually acts as a mediator through a resolution or conciliation service during that period3. After those first two years, the warranty's later cover takes over and the insurer handles claims for major problems directly.
The warranty splits responsibility over time: the builder in the first two years, the insurer after that.
The second clock belongs to the ombudsman schemes, and it is longer, but it is not unlimited. The Financial Ombudsman Service cannot consider a complaint referred more than six years after the event complained of, or, if later, more than three years from the date on which the complainant became aware, or ought reasonably to have become aware, that they had cause for complaint7. The Claims Management Ombudsman applies the same three-year awareness test: you cannot complain more than three years from when you became aware, or should have become aware, that you had a reason to complain13.
What this means in practice is that the date you first noticed a defect can matter as much as the date you bought the home. If a problem emerged during the first two years and the developer has been stringing out repairs, the awareness clock may already be running. Complaining formally in writing, early, protects your position on both clocks: it starts the developer's response deadline and it fixes the date from which any later escalation is measured.
There are also shorter referral windows once a firm has responded. In the car finance complaint rules, for example, a consumer has six months from the date of the business's response to refer the complaint to the ombudsman if they are not satisfied with it14. Check the rules of the specific code or scheme covering your home for the equivalent window, because missing it can close the route even when the underlying complaint is still within the longer time limits.
Ombudsman or warranty route: which one applies
Which scheme you escalate to depends on what your complaint is about. A complaint about the developer's conduct, the sale process, or its failure to finish or repair the home goes down the consumer code and New Homes Ombudsman route. A complaint about the warranty itself, for example a rejected claim or a warranty provider's handling, goes to the Financial Ombudsman Service, because consumers may complain to a firm and seek redress from it, and refer the complaint to the Financial Ombudsman Service if the firm does not satisfy the complaint and it is appropriate to do so15.
Each kind of problem has its own escalation path, but all of them start with the developer.
The two routes are not in competition, and a single problem can touch both. A defect in the first two years is the builder's to fix, with the warranty insurer usually mediating3. If the builder refuses or goes out of business, the warranty insurer can step in: the Financial Ombudsman Service can ask an insurer to deal with a claim it has rejected, take over from the builder if the builder is insolvent, add interest, pay for more work, or pay compensation for loss or inconvenience3. So a stalled repair by the developer can become a warranty claim, and a rejected warranty claim can become an ombudsman complaint.
The New Homes Quality Code is managed by the New Homes Quality Board, an organisation that operates independently from warranty providers2. That separation matters: the body that sets the standards for how developers treat you is not the same body that insures the building, so a poor experience with one does not close the door on the other.
What the Financial Ombudsman Service can order on a warranty complaint
When a warranty complaint reaches the Financial Ombudsman Service, the service can put things right in several ways. It may ask the insurer to deal with a claim it has rejected, take over from the builder if the builder is insolvent, add interest, pay for further work, or pay compensation for loss or inconvenience3. That range of remedies means the outcome is not limited to a simple yes or no on the original claim: the ombudsman can reshape the settlement so the defect actually gets fixed.
The service is free to consumers. Bringing a complaint to the Financial Ombudsman Service is straightforward and will not cost you anything6. You do not need a paid representative, and claims management companies that offer to complain on your behalf add nothing you cannot do yourself, since the same service is free either way.
The scale of the service gives a sense of how it works. The Financial Ombudsman Service received 305,726 new complaints in 2024/25 across all products, the highest level of complaints for six years17. Within that, complaints about building guarantees are a small but steady category: 100 new complaints about building guarantees were opened in the first quarter of 2026/2718. Most cases do not need a formal decision: the Claims Management Ombudsman, which shares its operating model with the Financial Ombudsman Service, resolves nine in ten complaints at the investigator stage, and most cases are resolved within 90 days13. A warranty complaint is therefore likely to be settled by an informal review rather than a full ombudsman decision, and often within a few months.
Payments for upset and inconvenience
Compensation for distress and inconvenience is a recognised part of ombudsman redress, and the amounts are modest. The Financial Ombudsman Service's published guidance on subsidence complaints shows it may award up to £1,500 for distress and inconvenience in the most serious cases19. In its standard guidance across several insurance complaint types, the figure given for distress and inconvenience is up to £30020.
Real cases show the range in practice. In one case the ombudsman suggested a payment of £150 to compensate a consumer for the inconvenience he had suffered21. The Pensions Ombudsman ordered a respondent to pay £500 for significant distress and inconvenience caused22. In another Financial Ombudsman Service case, a bank was told to pay £500 compensation for the distress and inconvenience the customer had experienced23.
| Type of award | Amount | Source of the figure |
|---|---|---|
| Distress and inconvenience, standard insurance complaints | Up to £30020 | Financial Ombudsman Service guidance |
| Distress and inconvenience, subsidence cases | Up to £1,50019 | Financial Ombudsman Service guidance |
| Example awards in decided cases | £15021, £50022 | Ombudsman case decisions |
These payments sit alongside, not instead of, the practical remedies. The main award in a successful warranty complaint is usually the work itself: getting the defect fixed, the claim dealt with, or the builder replaced by the insurer3. The inconvenience payment recognises the time, stress and effort the failure caused you. It is not a fine on the firm and it is not calculated on the value of the house, so it is best seen as a modest addition to a practical remedy rather than the point of complaining.
What the schemes will not cover
Every scheme draws a boundary around what it will look at, and it is worth knowing where the edges are before you invest time in a complaint. Schemes state their exclusions openly. The Financial Ombudsman Service, for example, states plainly that its page on guarantor loans does not cover complaints by guarantors of loans to businesses24. The New Homes Ombudsman and the consumer codes similarly cover disputes between the home buyer and the developer about the home and the sale, not every dispute a buyer might have.
Some government schemes have their own strict limits. The DIY housebuilders VAT refund scheme allows only a single claim, and requires additional information for paid claims no later than 4 years after the building has been completed25. That is a different scheme from the warranty and ombudsman routes, but it illustrates how new build-related schemes often combine a single opportunity with a hard deadline.
In practical terms, the new build complaint routes are aimed at defects in the home, the developer's service, and the sale process. Matters outside that relationship, such as a dispute with your mortgage lender, follow different routes: complaints about mortgages and related products go to the Financial Ombudsman Service under its own rules15. If your complaint straddles two firms, each firm should still handle the part that concerns it, and the scheme rules on forwarding complaints between firms exist to make sure a complaint does not fall between two stools26.
Final decisions and what happens next
When an ombudsman scheme issues a final decision, that is the end of the road within the scheme. There is no appeal against a final decision. The Insolvency Service's complaints gateway, for example, states that there is no appeal against a Gateway decision, though it will consider new evidence or new matters of concern27. The same principle applies across the ombudsman landscape: a final decision is final within the scheme, and the only route beyond it is outside the scheme.
Complaints bodies are equally firm about not reopening cases simply because the complainant dislikes the outcome. The Financial Services Compensation Scheme states that if a complaint just relates to the decision outcome, it may refuse a request to escalate it28. Its appeals process also does not apply to interim decisions, because those are not final decisions on the compensation claim29. The lesson for a complainant is to put all your evidence and arguments into the complaint while it is live, rather than holding anything back for an appeal that does not exist.
Not every complaint succeeds, and the published case decisions show this plainly. The Financial Ombudsman Service publishes cases where it did not uphold the complaint, including a complaint about misleading information provided at policy renewal30, a complaint about a used car of unsatisfactory quality21, and a complaint from a borrower who could not get the mortgage he needed after a low valuation31. A final decision against you does not mean your problem was imagined; it means the scheme did not find the firm liable under its rules.
If you reject a final decision, you keep your ordinary legal rights. The courts remain an option, and independent legal advice is recommended before going down that path32. Taking legal advice costs money, unlike the ombudsman routes, so weigh the value of what is in dispute against the cost before starting court action.
Where to get help
The first port of call for any new build problem is your own paperwork: the welcome pack supplied when you bought the home, which names the consumer code and the warranty covering your property2. The code's own guidance tells you how to complain, and the developer is required to cooperate with registered codes' processes once its registration is activated2.
For the building itself, your structural warranty provider is the key contact after the developer. Report defects to the builder in the first two years, but keep the warranty insurer informed, because it usually acts as mediator during that period and takes over responsibility for major problems afterwards3. The guide to new home warranties explains what the warranty covers and how to claim on it.
For the sale and the developer's conduct, the consumer code named in your welcome pack is the route, and beyond it the New Homes Ombudsman, which is free to consumers1. For complaints about a warranty provider, the Financial Ombudsman Service is free and straightforward to use6. If your dispute involves how a company handled your personal data, the Information Commissioner's Office takes complaints after you have complained to the company itself8. And if all scheme routes are exhausted, the courts remain open, with independent legal advice recommended first32.
Related guides that may help: buying a new build home, snagging a new build home, and complaining when buying a home goes wrong.
Sources32 cited
- New Homes Ombudsman summary integrated impact assessment Welsh Government, 19 January 2022
- Consumer code protection for homebuyers LABC Warranty, 2026
- Building warranties Financial Ombudsman Service, 26 September 2026
- Alternative Dispute Resolution research briefing CBP-7336 House of Commons Library, 26 September 2026
- DISP 1.6 Complaints time limit rules Financial Conduct Authority, 1 June 2026
- Unaffordable lending complaints Financial Ombudsman Service, 26 September 2026
- Review of the Financial Ombudsman Service consultation HM Treasury, 20 May 2026
- Your right to get your data corrected Information Commissioner's Office, 26 September 2026
- Equity release complaints Financial Ombudsman Service, 26 September 2026
- How we handle complaints The Pensions Ombudsman, 2026
- Complaints involving power of attorney Financial Ombudsman Service, 26 September 2026
- UK Government consultation on the role and powers of the Energy Ombudsman Consumer Scotland, 9 December 2025
- Claims Management Ombudsman leaflet Claims Management Ombudsman, 27 September 2026
- Complaints about commission Financial Ombudsman Service, 5 December 2025
- UNFCOG 1.6 consumers' right to refer complaints Financial Conduct Authority, 31 July 2026
- How to complain: savings endowments Financial Ombudsman Service, 2026-09-27
- Annual complaints data insight 2024/25 Financial Ombudsman Service, 2024
- Quarterly complaints data Q1 2026/27 Financial Ombudsman Service, 2026
- Subsidence and types of ground movement Financial Ombudsman Service, 26 September 2026
- Complaints that involve gambling related harm Financial Ombudsman Service, 26 September 2026
- Case study: consumer complains used car failed after eight months Financial Ombudsman Service, 26 September 2026
- Case study: failure to pay compensation The Pensions Ombudsman, 2026
- Case study: Felix loses thousands in international money transfer confusion Financial Ombudsman Service, 26 September 2026
- Guarantor loans Financial Ombudsman Service, 26 September 2026
- VAT refunds for new builds if you're a DIY housebuilder HM Revenue and Customs, 5 December 2023
- CONRED 6.1.9 credit broker complaints Financial Conduct Authority, 31 March 2026
- Insolvency practitioners guidance on how to complain Insolvency Service, 23 December 2025
- FSCS complaints process Financial Services Compensation Scheme, 25 September 2026
- FSCS appeals FAQ Financial Services Compensation Scheme, 25 September 2026
- Case study: consumer complains about misleading information provided at policy renewal Financial Ombudsman Service, 26 September 2026
- Case study: valuation low, now can't get mortgage need Financial Ombudsman Service, 26 September 2026
- Your rights relating to decisions made about you without human involvement Information Commissioner's Office, 25 September 2026


 MoneyHelperFree, impartial money and pensions guidance, set up by government
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales
 ShelterFree housing advice from a charity
 GOV.UKOfficial information on tax, benefits and government services
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right