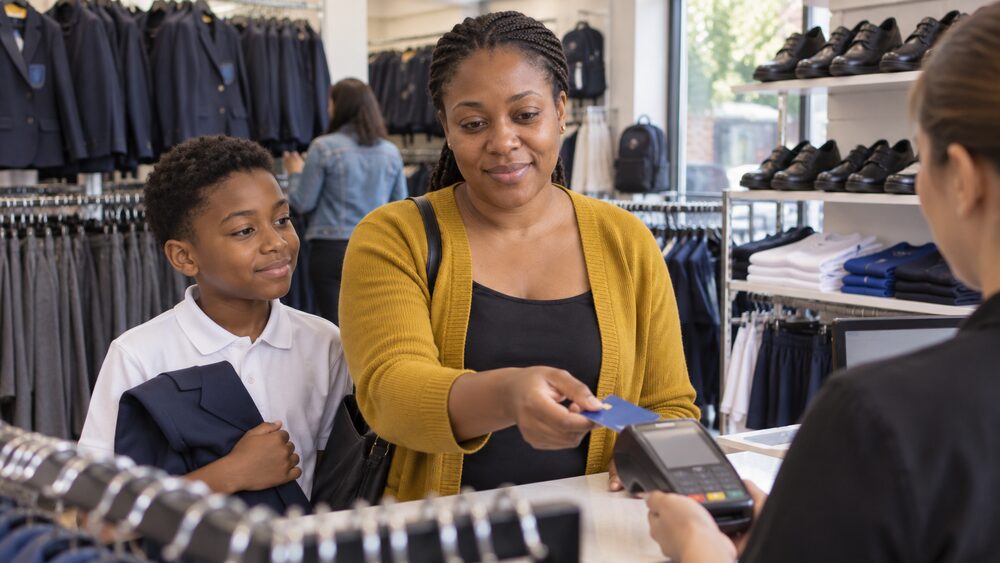
A school uniform loan is a small loan from a credit union, aimed at the cost of getting a child ready for school. Amounts typically run from £100 to £500, though some credit unions lend up to £750, and the money is meant for uniforms, shoes, PE kit, bags and essential school equipment1.
A school uniform loan is a small loan from a credit union, aimed at the cost of getting a child ready for school. Amounts typically run from £100 to £500, though some credit unions lend up to £750, and the money is meant for uniforms, shoes, PE kit, bags and essential school equipment1.
The appeal is the price. Some uniform loans charge no interest at all, and the rest sit well below the rates on high street borrowing. Credit unions lend small loans of around £50 to £3,000, and they are happy to offer much smaller sums than banks will consider3.
The catch is membership. Credit unions lend to their own members, so you generally need to join one first, and many expect a short record of saving before they will lend. Some uniform loans are seasonal, opening in the summer term and closing in the autumn.
What a school uniform loan is
Credit unions are member-owned lenders, and their small loans are the closest thing in the mainstream market to the old-fashioned provident loan. A uniform loan is one of those, sized to a single seasonal bill rather than to a car or a kitchen.
The amounts are deliberately modest. One credit union lends between £150 and £500 depending on how many school-age children you are supporting, with £350 for three children and £500 for four or more1. Another lends £100 to £500 with a maximum term of 26 weeks5. A third caps its uniform loan at £7502. Where a credit union already has a household goods loan running, it may lend up to £100 for each child's uniform instead of adding to the existing loan7.
That is a different shape of borrowing from a payday loan or a catalogue. Credit unions lend small loans of around £50 to £3,000, and the Welsh Government notes that they provide loans starting from £509. The point of a uniform loan is to spread one term's costs over a few months, not to fund a shortfall in the household budget.
It is worth knowing what else is available before borrowing. The School Essentials Grant in Wales offers up to £200 towards school uniform including coats and footwear, school activities and classroom essentials, and school uniform grants more generally run at around £100 a year10. Those are grants, not loans, and they do not have to be repaid.
What school uniform loans cost, from free to a variable rate
The headline is that some uniform loans are free to borrow. One credit union runs a School Uniform Loan with a maximum value of £750 and flexibility to increase payments2.
Others charge interest, and the cost is set out in a representative example rather than a rate you can compare at a glance. One school uniform loan quotes a total interest figure of £92 and a total cost of credit of £392 on its representative example, with a monthly repayment of £22 over an 18-month term6. Read the example as a whole: the total cost of credit is what the loan costs you over its life, and it is the number to compare between lenders.
Credit unions are not permitted to charge open-ended interest, and the wider market they sit in is cheap by design. Credit unions offer very competitive rates of interest on personal loans of up to about £3,000 and are happy to offer much smaller amounts4. For a loan of a few hundred pounds over a few months, the difference between a free loan and a low variable rate is a matter of pounds rather than tens of pounds, but it is still worth asking which applies.
Who can get one: membership, Child Benefit and one loan per household
Three conditions come up again and again.
The first is membership. Credit unions only lend to members, and you join through a common bond, which might be where you live, where you work, or a trade or profession. Some credit unions also require a period of saving before they will lend: you usually need a history of saving with a credit union before you can borrow long-term loans and mortgages13. Once you are a member, you can usually borrow at least two or three times the amount you have in savings, depending on the credit union's loan policy14.
The second is Child Benefit. One uniform loan requires that you must receive Child Benefit in the applicant's name1. A family loan from the same credit union is available to families or individuals in receipt of Child Benefit16. Child Benefit itself is payable for any of your children who are under 16 and live in the UK, and until they are 20 if they stay in most types of school, college or training after that age17.
The third is a household limit. One uniform loan allows one loan per household2. That matters if two adults in the same home each think they can apply.
Repaying weekly, monthly or from Child Benefit
Repayment is where these loans are most flexible, and where the choice matters most to a tight budget.
One uniform loan offers weekly repayments over 50 weeks, or 13 four-weekly instalments1. Another sets a minimum monthly repayment based on a six-month repayment period, quoting £17 a month for £100 borrowed and £25 a month for £15019. A third quotes a monthly repayment of £22 over an 18-month term6.
There is a separate product for households that would rather the money came straight out of a benefit. A Child Benefit Loan is repaid weekly or four-weekly from Child Benefit, and one credit union describes affordable monthly repayments with Child Benefit20. That structure suits people whose income arrives in benefit cycles rather than on a payday.
If your circumstances change, the repayment schedule is not fixed in stone. Credit unions are member-owned and generally willing to discuss a revised schedule before arrears build, which is a different starting point from a commercial lender's collections department.
How to apply and when the money arrives
Applications are usually online. One credit union simply says apply online22. Another asks you to apply once the child's account is active, after which the loan can be accessed immediately from the online app once approved, or by email, phone or calling in19.
Where the money lands is set out in the application. If your application is approved, your loan will be paid into the bank account shown on the Review page when you submit your application1. Check those details before submitting: the account shown on the review page is where the money goes.
Timing is the part people get wrong. Some uniform loans are seasonal. One school uniform loan is available from 1 July until 30 September23. Another credit union has closed uniform loan applications, which will reopen in summer 202724. Others run year round, and a back-to-school loan can be used for any school-related expenses, including uniforms, books, supplies and other educational needs25.
If you are applying in the run-up to the school year, apply early enough that the money arrives before the uniform bill does. Membership itself can take time to arrange, particularly if the credit union wants to see a savings record first.
Where a school uniform loan can go wrong
The main risk is the one that applies to any borrowing: the repayment outlasts the need. A uniform bought in August may be worn out before a 50-week repayment schedule finishes, and the money is still going out.
The second is the savings offset. If you miss payments on a loan, the credit union may be able to use your savings to repay the loan14. That is a protection for the credit union and a real consequence for you: the savings you built up as a member can be applied to the debt. It is not a penalty or a default fee, but it does mean the money is no longer available to you.
The third is the effect on your wider finances. Borrowing more than you can afford, or giving a lender wrong information about your circumstances, can lead to your affordability complaint being refused if you later argue the loan should never have been made27. Answer the affordability questions honestly, even where no credit check is involved.
There is protection on the other side too. When you borrow from a credit union you normally get free life insurance to cover the value of the loan, so the loan is repaid if you die before paying it back in full2. One credit union describes loan protection as cover that helps towards settling the loan debt if the borrower dies before the loan is repaid28. If you are checking what would happen to your debts, it is worth knowing which of them are covered: death cover for a mortgage, payment protection cover for personal loans or credit cards, and death in service from a pension are the usual places to look27.
If money is tight beyond the uniform bill, free and impartial help is available. StepChange and National Debtline both advise on problem debt, and MoneyHelper explains how credit unions work. If you are already behind on a credit union loan, see falling behind on a credit union loan.
Sources28 cited
- School Uniform Loan Unify Credit Union, 2026-09-26
- Credit unions Building Societies Association, 2026-09-15
- Short-term loan debt StepChange, 2026
- 10 tips on paying off your debts Which?, 2026-04-06
- Loans Banbridge Credit Union, 2025-07-29
- School Uniform Loan Westcountry Credit Union, 2026-09-17
- Loans Plus Credit Union, 2026-09-26
- Household Goods Loan Plus Credit Union, 2026-09-26
- Save, bank or borrow with a credit union Welsh Government, 2026
- Get help with school costs Welsh Government, 2026
- Free school meals Entitledto, 2026-09-26
- School Essentials Grant: help with school costs Welsh Government, 2026
- Credit union loans Shelter Cymru, 2026-08-30
- Your business and household budget Business Debtline, 2026-09-26
- Debt consolidation (England and Wales) National Debtline, 2026-09-25
- Family Loan Unify Credit Union, 2026-09-26
- Get help with money for your child mygov.scot, 2026-08-10
- Children Entitledto, 2026-09-26
- School Uniform Loan Harp and Crown Credit Union, 2026-09-26
- Child Benefit Loan Enterprise Shared Services Credit Union, 2026-09-14
- Loans Plane Saver Credit Union, 2026-09-26
- Uniform Loan Enterprise Credit Union, 2027-07
- School Uniform Loan BCCU, 2026-07-02
- Back to School Loan Kilkeel Credit Union, 2026-07-10
- Credit union current accounts MoneyHelper, 2026-09-25
- Debt consolidation (Scotland) Business Debtline, 2026-09-26
- Irresponsible lending and affordability checks StepChange, 2026-09-25
- Loan protection EK Credit Union, 2026


 MoneyHelperFree, impartial money and pensions guidance, set up by government
 FSCSProtects your money if a bank, insurer or investment firm fails
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 StepChangeFree debt advice and solutions from a charity
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales