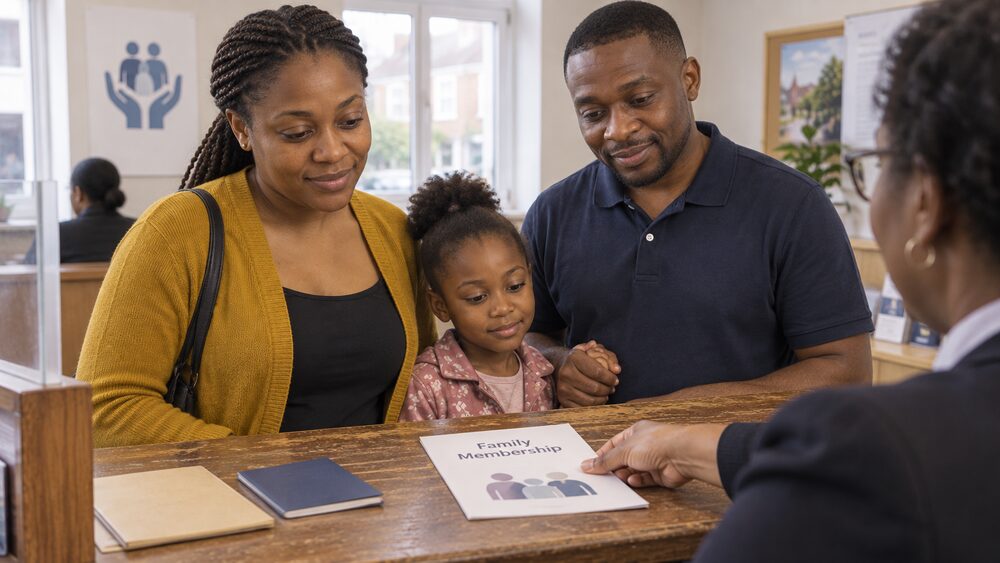
If you already belong to a credit union, the people you live with can usually join too. The standard rule is that once one family member meets the common bond and has joined, other family members living at the same address can usually join as well1. SCVO Credit Union puts it plainly: "Family members living at the same address as a member are also eligible"2. Teachers' Credit Union sets the same household rule at age 18 and over3.
If you already belong to a credit union, the people you live with can usually join too. The standard rule is that once one family member meets the common bond and has joined, other family members living at the same address can usually join as well1. SCVO Credit Union puts it plainly: "Family members living at the same address as a member are also eligible"2. Teachers' Credit Union sets the same household rule at age 18 and over3.
The route is called household or family membership, and it exists because a credit union's common bond is about a shared connection, not a single person. Anyone in the house of a person with a common bond with a credit union can usually join4. That means a partner, a parent, an adult child or another relative at the same address may qualify even if they have no link to the employer, trade or area the credit union was built around.
What it costs is small. MoneyHelper says joining normally means paying a small fee, for example £2, or saving a certain amount such as £105. Each member holds a £1 share and gets one vote, no matter how much they have in savings6. The rest of this page sets out who qualifies, how to add family members, and where the family route stops.
Family at the same address can usually join
The household rule is the most common way a credit union extends membership beyond its core common bond. Capital Credit Union tells applicants: "You live in the same household as an existing member, so you can join through their membership"10. Partners Credit Union includes a relative or family member living in the same household as one of its qualifying groups11. Drumchapel Credit Union admits relatives who live within the same household as a qualifying member12.
Some credit unions go further and name the relationship. Serve and Protect Credit Union lists a parent of an existing member living at the same address4. YourB Credit Union says other organisations, places of worship, family members and associated members can apply to join13. SCVO Credit Union says family or partners who reside in the household of a member are eligible2.
The pattern is consistent: the qualifying member is the anchor, and the household is the door. What varies is how tightly each credit union defines "household" and "relative", and whether it sets a minimum age for the family route. Teachers' Credit Union, for instance, requires family members to be 18 or over and residing in the same household as a directly qualifying member3.
The common bond: who qualifies in the first place
Before anyone can join as a family member, someone in the household has to qualify in their own right. Credit unions work by all members sharing a common bond5. That may be based on where they live or work, the type of occupation they have or their employer14. MoneyHelper describes it as living, working, studying or volunteering in a certain area, working in the same industry or for certain employers, or belonging to the same trade union5.
Some common bonds are wide. Capital Credit Union says its common bond means most people in the UK can become a member, and membership is open to anyone living or working in its common bond, employed by one of its employer partners, or a member of Community Trade Union10. Others are narrow. Keep Credit Union requires applicants to work for one of the employers listed in its common bond, or be a close relative of an existing member employed by one of those employers and live at the same address as that relative16.
Lodge Lane and District Credit Union sets out the standard area test: you qualify if you live in the community, work in the community, belong to an organisation or place of worship based there, or attend a school, college, university or training centre there17. If nobody in the house meets a test like that, the family route has no anchor to attach to.
Joining as a family member: the £1 share, fees and ID
Joining is a membership, not just an account. Each £1 of savings in the credit union equals a share in the credit union, as Moyola & Toome Credit Union puts it18. The founding principle is that each member holds a £1 share and each gets one vote, no matter how much they have in savings6. Any surplus funds generated are paid back to the members as a dividend6.
On cost, the picture varies by credit union. MoneyHelper says you will normally be asked to pay a small fee, for example £2, or save a certain amount such as £105. Willowfield Credit Union charges a £2 one-off joining fee, payable on joining17. Muckamore Credit Union charges £1 for junior members19. Some credit unions advertise no monthly or annual fees and low everyday fees11, and Lisburn Credit Union states that credit unions do not charge fees or transaction charges20.
For identity, you will usually need to provide two recent documents to prove your identity and address, for example a passport, driving licence, student or work ID card, bus pass, birth certificate, bank statement or energy bill5. Independent guidance says you need to visit or call your chosen credit union to confirm what information you need to join7. A family member applying through the household route should expect to show both their own ID and proof of the shared address.
Can my children open a credit union savings account?
Children can usually save with a credit union, but not in their own name alone. Just Credit Union says accounts can also be opened by adults on behalf of their children, grandchildren, nephews, nieces or any other special young person they choose21. Pennyburn Credit Union requires a legal parent or guardian to open the account22. Gleniffer Credit Union says a relative opens the account as trustee until the child reaches 18 years old8.
That trustee arrangement matters. Until the child turns 18, the adult holds the account for them, and the child cannot usually take the money out on their own. The child still becomes a member in the credit union's terms, which is why junior members can have their own joining fee, as Muckamore Credit Union's £1 junior fee shows19.
Junior saving is a common entry point for families, and it links to the wider picture of junior savers accounts and how savings accounts work once a child is old enough to hold one directly. For the adult opening it, the practical questions are the same as any other account: what ID is needed, whether there is a minimum balance, and how withdrawals are handled.
Where family membership may not apply
The family route is not universal, and it is not a way around the common bond. A relative who lives at a different address will usually not qualify through the household rule, because the rule is built on sharing a home. They would need to meet the common bond themselves, for example by living or working in the area, or through their own employer or trade union link.
Some credit unions also restrict what family members can do once they join. Ormeau Credit Union states that as a non-member you cannot apply for a loan, but you can join12. Just Credit Union's family loan requires applicants to be eligible to join if they are not already a member15. In other words, membership comes first and borrowing follows, and a family member who has just joined may need to build up a savings record before a loan is considered.
There is also a wider point about how credit union lending is regulated. Most of the loans that credit unions provide are specifically exempt from the Financial Conduct Authority's Consumer Credit sourcebook, known as CONC23. The FCA's CONC rules do not apply to most of the loans credit unions provide21, and the assessment standards, for example the level of checks a lender may have needed to do before lending, will typically be lower than those imposed on lenders and loans covered by CONC21. Credit unions are exempt from certain rules and regulations that apply to other financial services providers21.
That does not mean there is no protection. Credit unions are not-for-profit community lenders providing affordable loans and savings24, and they always consider affordability when assessing loan applications24. If something goes wrong with a credit union loan, the Financial Ombudsman Service can look at complaints about unaffordable lending21. The ombudsman's own guidance notes that credit unions are exempt from certain rules, which is a factor in how a complaint is assessed.
Protection for family savings
Credit unions are covered by the Financial Services Compensation Scheme. Enterprise Credit Union states that savings are protected by the FSCS9. The scheme's own guidance sets out what it does and does not cover, and credit insurance is not eligible for FSCS protection25. The Bank of England has published a depositor protection policy statement covering how the scheme operates26.
The practical point for a household is that protection attaches to the credit union, not to each person. If several family members hold accounts with the same credit union, the limit applies across those accounts rather than separately to each saver. Anyone relying on the scheme should check the current limit and how joint accounts are treated before assuming a particular sum is covered.
Beyond the scheme, the Financial Ombudsman Service is the free route for complaints a credit union has not resolved. The ombudsman can look at complaints about unaffordable lending21. For debt problems more broadly, StepChange offers free debt advice and information about credit unions23, and MoneyHelper provides independent guidance on credit union current accounts and joining5. The Association of British Credit Unions can help you find the right credit union, by visiting its website or calling 0800 015 306027.
Sources27 cited
- Credit unions Building Societies Association, 2026-09-15
- Employees FAQs SCVO Credit Union, 2026-09-26
- Membership Teachers' Credit Union, 2025-01-28
- Credit union family membership Serve and Protect Credit Union, 2026-09-15
- Credit union current accounts MoneyHelper, 2026-09-25
- What is a credit union Capital Credit Union, 2026
- About credit unions Find Your Credit Union, 2026-09-26
- Savings Gleniffer Credit Union, 2026-09-26
- Family loan Enterprise Credit Union, 2026-09-26
- Eligibility Capital Credit Union, 2026
- Help Partners Credit Union, 2026-09-26
- Terms of membership Drumchapel Credit Union, 2026-09-26
- Membership YourB Credit Union, 2026-09-26
- High-cost credit House of Commons Library, 2026-07-08
- Membership Capital Credit Union, 2026
- Terms and conditions Keep Credit Union, 2026-09-03
- Who can join Willowfield Credit Union, 2026-09-26
- Membership Moyola & Toome Credit Union, 2025-01-27
- Join us Muckamore Credit Union, 2025-06-09
- Loans Lisburn Credit Union, 2026-09-26
- Junior savings account Just Credit Union, 2026-06-24
- Become a member Pennyburn Credit Union, 2026-05-01
- Credit unions StepChange, 2026-09-25
- Save, bank or borrow: credit union Welsh Government, 2026
- Flood insurance Financial Services Compensation Scheme, 2026-09-25
- Depositor protection policy statement Bank of England, 2025-11
- Considering a payday loan StepChange, 2026-09-25




 MoneyHelperFree, impartial money and pensions guidance, set up by government
 FSCSProtects your money if a bank, insurer or investment firm fails
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 StepChangeFree debt advice and solutions from a charity
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales