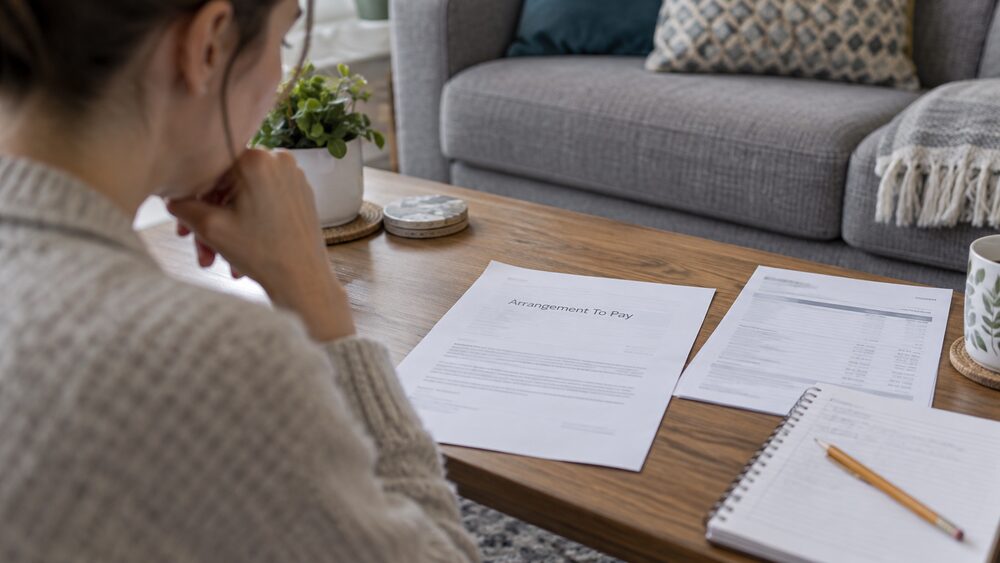
An arrangement to pay is what a lender records when you are struggling to repay a credit account and it agrees to accept reduced payments for a period of time. The marker appears in your credit report, so anyone checking it later can see that you paid less than the amount originally agreed1. It is not the same as a missed payment, and it is not the same as a default, but it does stay on your file and it does affect how lenders see you.
An arrangement to pay is what a lender records when you are struggling to repay a credit account and it agrees to accept reduced payments for a period of time. The marker appears in your credit report, so anyone checking it later can see that you paid less than the amount originally agreed1. It is not the same as a missed payment, and it is not the same as a default, but it does stay on your file and it does affect how lenders see you.
The practical version of this for most people is the token payment: small regular payments, such as £1 per month to your creditors, typically where a credit account has already run into difficulty2. Debt charities use £1 a month as the standard figure, paid to each debt, until your situation improves enough to pay more3. One charity's token payment plan runs at £1 each month to everyone you owe for up to one year4.
What follows sets out what the marker shows, how it affects your score, how token payments work in practice, and how long each kind of entry lasts.
What an arrangement to pay marker shows
The marker is a factual note on your credit report that the account is being repaid on terms other than the original ones. Experian, one of the three UK credit reference agencies, describes it plainly: if you are struggling to repay a credit account, a lender may allow you to make reduced payments for a period of time, and this is shown in your credit report1. It is not a judgment about you, and it is not a separate debt. It is a status flag on that account.
The same flag appears under several names depending on who is reporting it and why. Some creditors add DMP or arrangement to pay markers for payments made through a debt management plan8. The people you owe may add a marker to show your payments are made through a DMP9. Debts included in a DMP can have a payment arrangement note added, also called a DMP flag, but only if creditors accept what you pay them9. So the marker is conditional: it records an arrangement that the creditor has actually agreed to.
It helps to separate this from the other flags that can sit on a file. A full and final settlement leaves your file marked to show you have made a partial settlement10, and credit reference agencies may mark the account with a P flag for partial settlement, meaning you have made a part payment rather than paying in full11. A Cifas marker is different again: it may be added to your credit file to warn lenders that your identity has been compromised12. None of these is an arrangement to pay, and none of them means the same thing to a lender reading your file.
How an arrangement to pay affects your credit score
The short answer is that it affects it, and the mechanism is the same one that runs through every reduced-payment arrangement. Your credit file will be affected any time you pay less than what you agreed to when you took out the debt7. That is the underlying rule, and it applies whether the arrangement was agreed formally, informally, or through a debt charity.
What the file actually shows matters as much as the marker itself. Where an account defaults, your credit file will show that you did not make your agreed payments, which impacts your credit score13. A payment holiday leaves a gap in payments that may be marked on your credit file and can make it harder to get credit in future14. Any payment you miss during forbearance is recorded on your credit file and could make it harder to get credit in the future15. Even a bill paid late can affect your credit rating and will appear on your credit file16.
The distinction that matters most is timing. Your creditors will sometimes mark lower payments on your credit file as an arrangement to pay if you get debt help before your accounts have defaulted17. Getting advice early, while the account is still live and before a default is registered, is what produces the arrangement marker rather than a default. Once an account has defaulted, the arrangement is no longer the headline entry.
There is a second consequence beyond the score itself. Reduced payments can make it harder to get credit in future, and your account may default18. Making reduced payments towards a debt can impact your credit file, and this could make it hard for you to take out more credit19. The marker is not a punishment layered on top of the reduced payment; it is the record of it, and lenders weigh it as part of the whole picture.
Token payments: from £1 a month to each creditor
A token payment is a small regular payment made to a creditor where a credit account has run into difficulty and there is little or nothing left over each month. The standard figure used across debt advice is £1. You could offer a token payment of £1 a month to each creditor instead of no payment at all5. You may prefer to make token offers of payment of £1 each month to each creditor20. The same figure appears in the Scottish guidance21.
Where a debt charity runs the arrangement, the mechanics are set out for you. Under a token payment plan you pay £1 a month to each of your debts until your situation improves enough so you can pay them more3. The Scottish version of the same plan is £1 each month to everyone you owe, for up to one year4. Token payments are when you make small regular payments such as £1 per month to your creditors, typically where a credit account has run into difficulty2.
If a debt has already reached court, the figure does not change. Where a creditor applies for a county court judgment and proceeds to the Enforcement of Judgements Office, they are likely to report back that you can only afford to pay a token amount, which could be as low as £1 per month22. Where the court itself sets the rate, it is likely to accept that you can only pay a token amount, for example, £1 a month23.
A token payment can stop things escalating while you get help
The reason debt advisers suggest token payments is that they keep an account in an agreed state while a longer-term solution is worked out. An offer of token payments may be a way of preventing court action for the debt2. That is the immediate practical value: the creditor has something in hand, the account is not simply ignored, and the file records an arrangement rather than an unagreed gap.
The alternative is worse on the file. If you stop paying without agreeing anything, the provider and credit reference agencies count this as a missed payment, recorded on your credit file, and several missed payments put your account at risk of defaulting24. An arrangement is a short-term agreement with the people you owe that helps you catch up on payments you have missed at a rate you can afford7. The difference between the two is the agreement, not the amount.
There is a letter for this. National Debtline publishes a token payment or no offer of payment letter, to ask your creditors to accept a token payment or no payment on your debts25. Using a standard letter keeps the request clear and gives the creditor the information it needs to decide.
Where a debt adviser is involved, the range of things a creditor can be asked for widens. You can ask your other creditors to stop interest and charges, stop collection agencies recovering debt, accept token payments, or write off the debts26. Lenders can reduce or stop charging interest on your arrears27. On a mortgage, lenders can reduce your payments for a set period, charge interest only for a while on a repayment mortgage, give a payment holiday, or extend the mortgage term to reduce payments, depending on your payment history and whether the difficulties are long or short term28. Mortgage lenders are expected to help if you are struggling to pay your mortgage, which could include reducing your monthly payments or taking a break from your payments for a few months29.
How long the marker stays depends on your arrangement
There is no single retention period for an arrangement to pay, because the answer depends on what kind of entry ends up on the file. The figures that are fixed are the ones attached to specific markers.
Payment history is the baseline. Your payment history stays on your credit file for six years6. A debt management plan marker or default stays on your credit file for six years31. A missed mortgage repayment leaves a mark on your credit report that remains for six years32. A county court judgment stays on your credit reference file and the Register of Judgments, Orders and Fines for six years from the date the CCJ was made, unless you pay the CCJ in full within one calendar month33. Even after a CCJ is paid, it will still stay on your credit report until the six years is up, though your record will show that you have paid the debt34.
The arrangement itself is shorter. A token payment plan runs at £1 each month to everyone you owe for up to one year4. That is the plan's own duration, not the life of the marker: the payments made under it are part of your payment history and follow the six-year rule.
| Entry on your file | How long it stays | Source |
|---|---|---|
| Payment history | Six years | 6 |
| DMP marker or default | Six years | 31 |
| Missed mortgage repayment mark | Six years | 32 |
| County court judgment | Six years from the date it was made, unless paid in full within one calendar month | 33 |
| Token payment plan (the plan itself) | Up to one year | 4 |
Asking a lender for reduced payments
Creditors can say no, and they can attach conditions. What they offer depends on your payment history and whether the difficulty is short or long term28. On priority debts, the options are to make lower payments for a short period, ask to pay less for a while longer based on what you can afford, or ask for a payment holiday if you cannot afford anything at all30.
Some arrangements carry a cost that is easy to miss. A payment holiday lets you stop making payments for a short time, but you are charged extra interest once you start making them again35. On a credit card, the first thing to do is stop using the card you want to pay off, so the amount you owe stops growing and it becomes quicker to repay36. Stopping the growth is often worth more than the arrangement itself.
If you are in Scotland, the Debt Arrangement Scheme works differently: you make one monthly or weekly payment to your creditors4. A debtor who is an individual may request a short term financial crisis payment break in the circumstances set out in the regulations37. In Northern Ireland, mortgage lenders can reduce your payments for a set period, charge interest only for a while, give a payment holiday, or extend the term28.
Where a debt has already gone to court, a token payment offer is still available. You can make an offer of a token payment if you do not have any money left over, and it does not matter how small the offer is38. If a fine has been added to a public register so it appears on your credit file, that is a separate route with its own rules39.
Where to get free help
Debt advice is free from several national services, and using it does not by itself change what is on your file. StepChange, National Debtline, Citizens Advice and Shelter all publish guidance on arrangements, token payments and what creditors can be asked to do. MoneyHelper covers credit and borrowing questions, including guarantor loans, where being a guarantor will not affect your credit rating as long as the borrower pays back the debt on time, but payments made on their behalf are added to your credit history and could reduce your credit score40.
If a financial firm has not followed the rules, Citizens Advice sets out how to check and what to do next41. If you are self-employed, the advice routes differ slightly42, and where a debt may be written off, that is a separate question from whether an arrangement marker is recorded43.
Sources43 cited
- Understanding credit information Experian
- Debt solutions Shelter Cymru
- Glossary StepChange
- Debt advice in Scotland StepChange
- Your non-priority debts (Scotland) Business Debtline
- Token payment plan StepChange
- Arranging payment with creditors StepChange
- Debt management plans and your credit score StepChange
- Debt management plan questions StepChange
- Ways to clear your debt (Scotland) National Debtline
- Full and final settlement offers (Scotland) National Debtline
- Types of scam MoneyHelper
- Default notices and missed payments StepChange
- Payment holiday for debt repayments StepChange
- Debt moratorium and forbearance StepChange
- Direct debits and standing orders explained Which?
- Debt Arrangement Scheme or DMP StepChange
- Negotiating with my creditors StepChange
- Temporary repayment plan StepChange
- Ways to clear your debt (Scotland) Business Debtline
- Ways to clear your debt (England and Wales) Business Debtline
- Debt write-offs Advice NI
- Write off debt (England and Wales) National Debtline
- Credit card payment holidays StepChange
- Token payment or no offer of payment letter National Debtline
- Managing your mortgage and income Housing Rights
- Personal loans Citizens Advice
- How to deal with missed mortgage payments Shelter England
- Check if a financial service has followed the rules Citizens Advice
- Work out your priority debts StepChange
- Debt management companies StepChange
- How do mortgage payments work Which?
- Replying to a county court claim (England and Wales) Business Debtline
- County court judgments and your credit rating Citizens Advice
- Top tips for borrowing Citizens Advice
- Paying off credit card debt StepChange
- The Debt Arrangement Scheme (Scotland) Regulations 2019 legislation.gov.uk
- Can't pay a CCJ StepChange
- Criminal fines StepChange
- Guarantor loans explained MoneyHelper
- Mortgage arrears or payment difficulties nidirect
- Self-employed debt advice StepChange
- Can I write off debt StepChange










 MoneyHelperFree, impartial money and pensions guidance, set up by government
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales
 StepChangeFree debt advice and solutions from a charity
 GOV.UKOfficial information on tax, benefits and government services