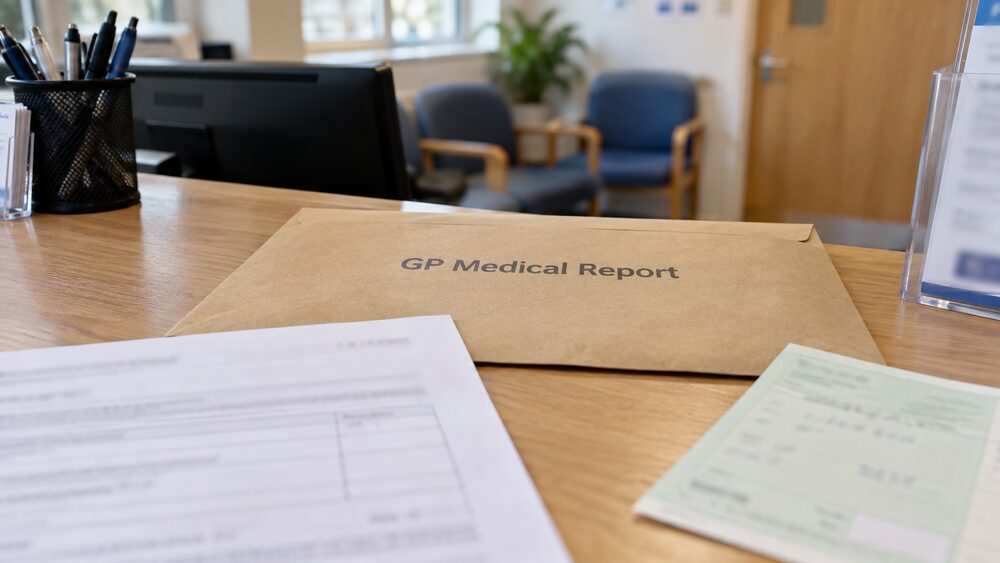
Applying for life insurance usually means answering a set of about ten questions covering your medical history and lifestyle, and the insurer may then check those answers with your GP1. A GP report is not automatic. It is requested where the answers need confirming or explaining, and where a case is complex the insurer will often send a specialist nurse to your home for a medical examination2.
Applying for life insurance usually means answering a set of about ten questions covering your medical history and lifestyle, and the insurer may then check those answers with your GP1. A GP report is not automatic. It is requested where the answers need confirming or explaining, and where a case is complex the insurer will often send a specialist nurse to your home for a medical examination2.
The report itself is a General Practitioners Report, usually sent to your GP or hospital doctor with your fully informed consent, and the doctor is required to complete it3. It covers current health, sickness record, past health and predictive genetic test results3. You are entitled to talk with the doctor before any report is sent to the insurer, and there may be a chance to see a copy first3.
What follows is how the checks work, when they are more likely, what the health questions cover, what happens if an answer is wrong, and the guaranteed acceptance route for people who would rather avoid medical underwriting.
Insurers check your application answers with your GP
The application form is the starting point, but it is not the only evidence an insurer uses. Insurers will also check your answers with your GP4. The wider set of sources an insurer draws on includes your application form, questions about your lifestyle, your medical history, a doctor's report, and historical data and research5.
Where a condition needs to be understood, insurance companies may request medical information from your GP or hospital doctor to better understand the condition and accurately price the additional risk3. They may also consult their own Chief Medical Officer or other qualified experts3. The insurance company will always ask for your permission to contact your GP or hospital doctor3.
That permission is not a formality. If a GP or hospital doctor report is requested, you will be asked for your fully informed consent, and there may be a chance to see a copy of the report before it is sent3. You are entitled to talk with your GP or hospital doctor before medical reports are sent to the insurance company3. The report is usually sent to the GP or hospital doctor with the applicant's fully informed consent, and the doctor is required to complete it3.
For most people, the process stops at the form. A GP report is the exception, triggered by something in the answers rather than applied to everyone. The same principle runs through protection applications generally: you make an honest declaration and your GP may be asked to confirm your medical conditions6.
When a GP report or medical exam is more likely
Complex cases are where medical evidence earns its place. Insurers may require a medical examination, often sending a specialist nurse to your home2. The trigger is usually a condition that is hard to price from the form alone, or a level of cover that makes the insurer want more certainty.
Cancer is the clearest example. People who have recovered from cancer may be asked to provide detailed medical information and attend a medical examination, with higher premiums and restrictions on the maximum sum insured2. Where the medical prognosis is that you will die during the policy term, insurers cannot cover certainties, so they are legally entitled to refuse you cover2.
Diabetes is another condition that generates detailed questions rather than an automatic report. Applicants are asked whether they have type 1 or type 2 diabetes, or a rarer form, along with HbA1c average blood glucose test results, any hospitalisations or significant developments, changes to treatment, and any complications experienced7. When applying for a new policy, you will need to provide full details of when you were first diagnosed, your medical history plus the specifics of your treatment and medication8. People with diabetes can buy most forms of life insurance, with level term and decreasing term the two main types7.
Group schemes have their own triggers. Medical information may be needed when an employee has a particularly high level of cover, there has been an increase in cover for a small number of employees, or an employer asks to cover an individual employee for a higher benefit9.
What the health questions cover: the five-year lookback and smoking
A standard life insurance quote asks a set of about ten questions1. They cover whether other illnesses have been diagnosed within the past five years, and whether you have received any medical treatment in the past 12 months4. Some questions ask "have you ever", which reaches back further than five years1.
Smoking and nicotine use sit in the same set of questions. You must tell your life insurer if you smoke or vape using nicotine products, even if you do so only occasionally2. That covers vaping and nicotine replacement, not just cigarettes.
The non-smoker definition is not standard across the market. Some insurers only require you to have quit for a year, others for two, five or even 10 years2. Because the gap differs, the same person can be treated as a smoker by one insurer and a non-smoker by another, and the insurer's own definition applies to the application in front of it.
The answers feed directly into pricing. The cost of life insurance is based on factors such as your age, your health, your job, whether you smoke, the policy length and the amount of cover10. One insurer lists the information it wants as age, occupation, smoker status, height and weight, medical history, alcohol consumption, travel and residency, and hobbies such as hazardous activities11. Another sets out the main factors as age, occupation, smoker status, health, the level of cover and the type of cover, with height, weight, medical history and lifestyle assessed alongside12.
Getting your answers wrong can void the policy
The consequence of an inaccurate answer is not a small adjustment. Giving incorrect or inaccurate information may reduce your payout in the event of a claim or, worst case, your policy may be cancelled and any claim refused13. If any information was inaccurate or incomplete at the time of application, the claim will be rejected and the policy cancelled14.
The law draws a line at reasonable care. Under the Consumer Insurance (Disclosure and Representations) Act, if customers do not take reasonable care, insurers may be allowed to void policies and refuse false claims or alter the terms of a policy15. The same warning appears across other insurance lines: if you fail to provide accurate information a subsequent claim may be refused16.
Smoking is the classic example of an answer that comes back at claim stage. If your family later needs to claim, your policy may be declared void, and any payout refused8.
The reverse position is worth stating just as firmly. Once a policy is in place, the premiums cannot be increased, and as long as you make full and honest disclosures on your application and continue paying the premiums, the policy cannot be cancelled7. If you already have life insurance and are subsequently diagnosed with diabetes, you do not have to tell your insurer or pay higher premiums8. There is often no need to tell your life insurer if you develop cancer after the policy starts8.
If you would rather avoid medical checks: guaranteed acceptance cover
It is possible to buy non-medically underwritten guaranteed acceptance life insurance if you cannot get standard cover, but it is more expensive1. Specialist, non-medically screened policies offer guaranteed cover for anyone, and are often more expensive, with limited term length or total sum insured2. Guaranteed life insurance is a type of life insurance that you will be accepted for, regardless of your health17.
Providers describe the same feature in plain terms. TSB over 50s life insurance offers guaranteed acceptance with no medical questions18, and its Over 50s Fixed Life Insurance has guaranteed acceptance, with no medical questions19. These plans sit in the over 50s life insurance market, where acceptance is the trade-off for a smaller sum insured or a fixed term.
There is a middle route for people who are accepted on standard terms. If an application is accepted on standard terms with no medical rating, guaranteed insurability options let you increase your level of cover without further medical evidence20. That matters after events such as marriage or a new child, when cover needs to rise but health may have changed.
For anyone weighing the two, the comparison between over 50s plans and term cover sets out how the payout structures differ, and life insurance with no medical questions covers the acceptance-based options in more detail.
Where the protection stops
The rules protect you at the point of application as well as at claim. A GP report cannot be requested without your fully informed consent, you are entitled to talk with the doctor before reports are sent, and there may be a chance to see a copy first3. If a dispute arises later about what was disclosed or how a claim was handled, the Financial Ombudsman Service can look at it.
The limits are equally clear. Insurers cannot cover certainties, so where the prognosis is that you will die during the policy term they are legally entitled to refuse cover2. Guaranteed acceptance plans accept everyone but pay less or cost more2. And the protection built into an existing policy depends on the application having been complete: the policy cannot be cancelled only as long as you made full and honest disclosures and continue paying the premiums7.
If you are applying with a health condition, the pages on pre-existing conditions and applying and underwriting set out how insurers assess risk, and answering an insurer's questions honestly explains the disclosure duty in full. Free, impartial help on protection and money questions is available from MoneyHelper.
Sources20 cited
- Over 50s life insurance Which?, 2025-12-03
- Life insurance with cancer explained Which?, 2026-06-25
- Insurance and genetic conditions: FAQs Genetic Alliance UK, 2026
- Types of life insurance policy Which?, 2025-05-16
- Mental health and insurance cover Mental Health and Money Advice, 2023-09-05
- What is mortgage protection life insurance Which?, 2026-09-25
- Life insurance for people with diabetes Which?, 2026-06-25
- Life insurance for pre-existing conditions Which?, 2026-06-25
- Group life insurance Canada Life, 2026-09-26
- Life insurance explained Scottish Widows, 2026-09-25
- Pre-existing conditions Legal & General, 2026-03-16
- Information you need to know Legal & General, 2026-09-26
- Life cover help and support Post Office, 2026
- Life insurance and cancer Post Office, 2026-08-17
- Consumer Insurance (Disclosure and Representations) Act 2012 House of Commons Library, 2026-07-08
- How much will it cost? British Insurance Brokers' Association, 2026-09-26
- Life insurance glossary Aviva, 2026-09-26
- Insurance TSB, 2026
- Over 50s life insurance TSB, 2026
- Flexible life plan Canada Life, 2026-09-26







 MoneyHelperFree, impartial money and pensions guidance, set up by government
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 FSCSProtects your money if a bank, insurer or investment firm fails
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales
 Turn2usFree benefits calculator and grants search from a charity