Yes. Equity release cannot be completed without your own independent solicitor. All Equity Release Council-approved providers require you to seek independent legal advice, and the Council requires your provider to make sure you receive it on the implications and potential consequences of the plan1. You sign the offer documents in the presence of a solicitor, and the solicitor signs a certificate confirming you were seen and understand the contract3.
Yes. Equity release cannot be completed without your own independent solicitor. All Equity Release Council-approved providers require you to seek independent legal advice, and the Council requires your provider to make sure you receive it on the implications and potential consequences of the plan1. You sign the offer documents in the presence of a solicitor, and the solicitor signs a certificate confirming you were seen and understand the contract3.
The solicitor is not there to sell you anything or to tell you whether the plan is a good idea. Their job is independent legal advice on the risks, rewards and obligations, plus the conveyancing that lets your new lender take a first legal charge over your home and repay any existing secured borrowing2. A separate financial adviser handles the suitability question and must give you a written suitability report3.
The legal fee is one of several costs. Solicitors' fees are typically around £860, though they vary, and advice fees commonly run from £500 to £2,0005. The whole process usually takes eight to ten weeks from application6.
Yes: equity release needs your own independent solicitor
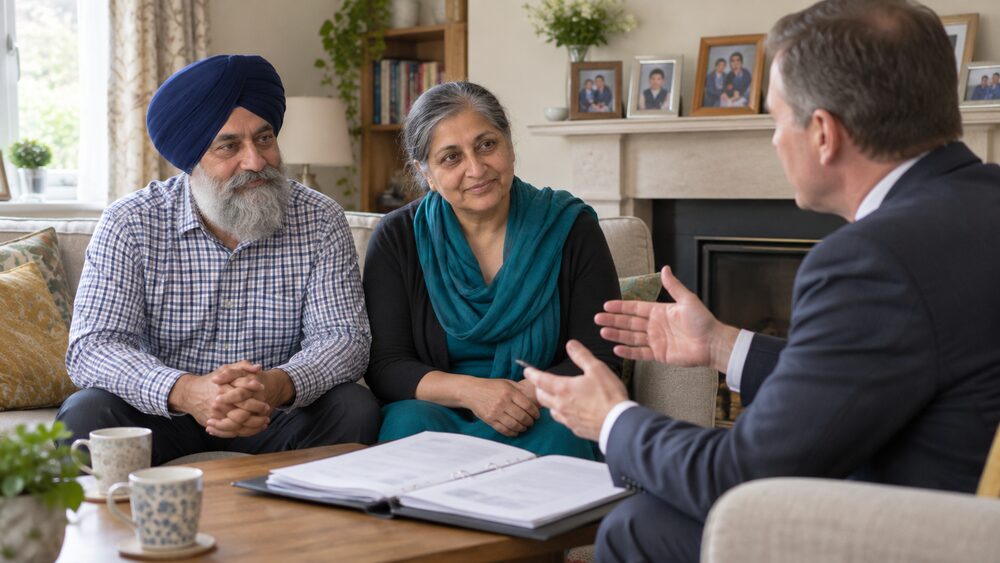
The requirement is not a formality a lender can waive. Once a financial adviser has recommended a suitable equity release plan, you need to appoint your own solicitor to represent your interests2. The Council's rules require that you have at least one face-to-face meeting, either with a solicitor or with an agent or notary the solicitor appoints to see you on their behalf, and the solicitor acting has to sign a certificate confirming this was done and that you understand the contract3.
The solicitor's work has two halves. The first is the legal advice itself: ensuring you receive completely independent legal advice about the risks, rewards and obligations attaching to the plan2. The second is conveyancing, so that your new equity release lender can secure a first legal charge against your property and any existing secured borrowing is repaid2.
Your solicitor will want to see you on your own, at least in the first instance, to ensure you understand the plan and are not under pressure3. The Council describes this as primarily to protect your interests and to avoid fraudulent applications10. The same protection applies where someone holds a power of attorney: the Council's rules exist so that the person granting it is protected, not bypassed10.
"We also require all customers to be given independent legal advice when they are about to enter into their equity release contract."
Choosing a solicitor who specialises in equity release
The guidance is to choose a solicitor who specialises in equity release and who is a member of the Equity Release Council9. Membership matters because the Council's standards, including the face-to-face meeting and the certificate, are what the solicitor is signing up to3.
Your existing solicitor may be able to do the work, but equity release is a specialist area and not every firm handles it. It is possible that your solicitor may ask you to appoint a third party solicitor to deal with an aspect they are not expert in, and this applies in Scotland as well as England9. If your usual firm does not do equity release, that is a reason to look for one that does rather than a reason to skip the step.
You can get further information from individual Equity Release Council members or from other qualified advisory firms11. The financial advice side is separate: a fully qualified financial adviser should help you understand the steps involved and talk you through your options, and the recommendation is to use an independent financial adviser who specialises in equity release12. Before purchasing an equity release product you are required to get professional financial advice, so it is worth checking that the adviser is qualified in this area12.
Legal fees and the other costs of equity release
The legal fee is what you pay your solicitor for the work they do on the legal side of the scheme13. It sits alongside several other costs, and different fees are likely to be charged when you enter into an equity release agreement14. Independent guidance puts typical solicitors' fees at around £860, noting that average solicitor fees can vary and that it is worth comparing a few prices5.
| Cost | What it covers | Typical figure |
|---|---|---|
| Legal fee | Your solicitor's work on the legal side of the scheme13 | Around £860, varies5 |
| Advice fee | The financial adviser's work | £500 to £2,0002 |
| Application fee | Provider's set-up charge, not charged by all providers | Up to around £7007 |
| Valuation fee | Property valuation | Most lenders offer a free valuation on new applications; often a fee for further advances9 |
Independent Age's summary is blunt: you will have to pay application, legal and other fees, and these can be high13. Some providers allow fees to be added to the amount borrowed rather than paid upfront, which increases what you owe and the interest that builds on it7.
There is a further cost that arrives at the end, not the start. You or your estate will be responsible for paying all the costs of the sale, including solicitors' fees, when the plan is eventually repaid15. Repayment is triggered when you pass away, move into permanent care or choose to sell your home9. If you end an equity release agreement early, you might have to pay an early repayment charge, which can often be a significant amount, and some providers charge for paying back the plan in full16.
From recommendation to completion: eight to ten weeks
The average is eight to ten weeks from the application being submitted9. The entire process can take anywhere from a few weeks to a few months, depending on the complexity of the application15.
The solicitor's part in the sequence is specific. You and your solicitor sign the acceptance form and an Equity Release Council Solicitor's Certificate, which confirms that all key points have been discussed9. Your solicitor then prepares a bundle, including your signed equity release paperwork, for the lender's solicitor, who reviews it and sets a completion date if everything is in order17. If everything is straightforward, that stage should be within a week or two, provided your solicitor has sent the bundle of signed documents promptly3.
One practical warning sits inside this timeline. The Council's own guidance is that you are strongly advised not to commit to spending the proceeds until your solicitor confirms when completion will take place15.
What your solicitor should check before you sign
The legal advice is meant to cover the implications and potential consequences of the plan, and those consequences are concrete. Equity release reduces the value of your estate and the amount that will go to the people named as beneficiaries in your will18. It may affect your tax position, may impact the benefits you already get or that you can apply for, and carries implications for securing other debts against your home9.
Your solicitor cannot answer the suitability question. Your solicitor will not be able to tell you whether or not a particular product is suitable for you, as this is the role of your financial adviser2. What the adviser should do is consider your personal circumstances, including an assessment of your income and expenses, and explore alternatives to equity release19. You need to be comfortable with the effect on your estate, and may wish to discuss it with your family before committing, including in discussions with your financial adviser or solicitor11.
It is also worth asking your adviser about inheritance protection, which protects some of the property's future value9. And if you later need to move into long-term care, the time allowed to sell the property is typically between 6 months and 1 year20.
Where the protection stops
The safeguards around equity release are real but bounded. With some lenders, you will never owe more than the value of your home, if they offer a no negative equity guarantee9. That is a guarantee from the lender, not a universal feature, so it is one of the things to check rather than assume.
If something goes wrong with the advice or the sale, the Financial Ombudsman Service can look at complaints about equity release21. Free and impartial help is available too: StepChange offers guidance on equity release and on the alternatives, and Independent Age publishes advice on the subject5. The Council's consumer charter sets out what member firms commit to, including advice that considers your personal circumstances and explores alternatives22.
The limits are worth stating plainly. Equity release may impact the size of your estate after your death, future property prices might be higher or lower than they are today, and consolidating debts over a longer period may mean you pay more overall9. The legal advice requirement exists so that you hear those points from someone whose only job is to represent you, before you sign.
Is the process different if I live in Scotland?
Yes. The guidance is that you will need different advice if you live in Scotland13. The legal system differs, so the solicitor acting for you needs to be able to work within it, and the same fallback applies: your solicitor may ask you to appoint a third party solicitor to deal with an aspect they are not expert in9.
Scotland also has its own shared equity schemes, which work differently from equity release. If you are buying through the Open Market Shared Equity scheme, you need a solicitor to act on your behalf to assist you with buying the home, and the Scottish Government has its own solicitor who handles work involving its equity share23. That is a purchase scheme, not a lifetime mortgage, but the legal representation requirement is the same in principle.
For anyone in England, Wales or Northern Ireland considering equity release, the starting point is the same: independent legal advice, your own solicitor, and a certificate signed before completion1.
Sources23 cited
- Legal and regulatory matters Equity Release Council, 2026-09-26
- Why do I need a solicitor to help me through the equity release process? Equity Release Council, 2026-01-16
- The application process Equity Release Council, 2026-09-26
- Any risks? Equity Release Council, 2026-09-26
- Equity release tips StepChange, 2026-09-25
- Equity release StepChange, 2026-09-25
- Equity release costs Legal & General, 2026-09-26
- Do I need to take legal advice? Equity Release Council, 2022-12-13
- What is the standard process for taking out an equity release plan? Equity Release Council, 2022-09-02
- I have a power of attorney in place, can my attorney deal with the equity release for me? Equity Release Council, 2022-09-02
- Find an adviser Equity Release Council, 2026-09-26
- What is equity release? Which?, 2026-04-13
- Equity release Independent Age, 2026-09-26
- Equity release (England and Wales) Business Debtline, 2026-09-26
- What is the usual time frame between signing my paperwork and receiving my money? Equity Release Council, 2026-01-16
- If I take out an equity release scheme do I risk losing my house? Equity Release Council, 2026-01-16
- What happens when I have signed the mortgage paperwork? Equity Release Council, 2022-09-02
- What impact will it have on my family? Equity Release Council, 2022-09-02
- What is equity release? Equity Release Council, 2026-04-13
- What happens if I have an equity release plan and need to move into long term care? Equity Release Council, 2026-01-16
- Equity release Financial Ombudsman Service, 2026-09-26
- Standards 2.0 Consumer Charter Equity Release Council, 2026
- Open Market Shared Equity scheme: how to apply mygov.scot, 2026-03-17











 MoneyHelperFree, impartial money and pensions guidance, set up by government
 StepChangeFree debt advice and solutions from a charity
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales
 ShelterFree housing advice from a charity