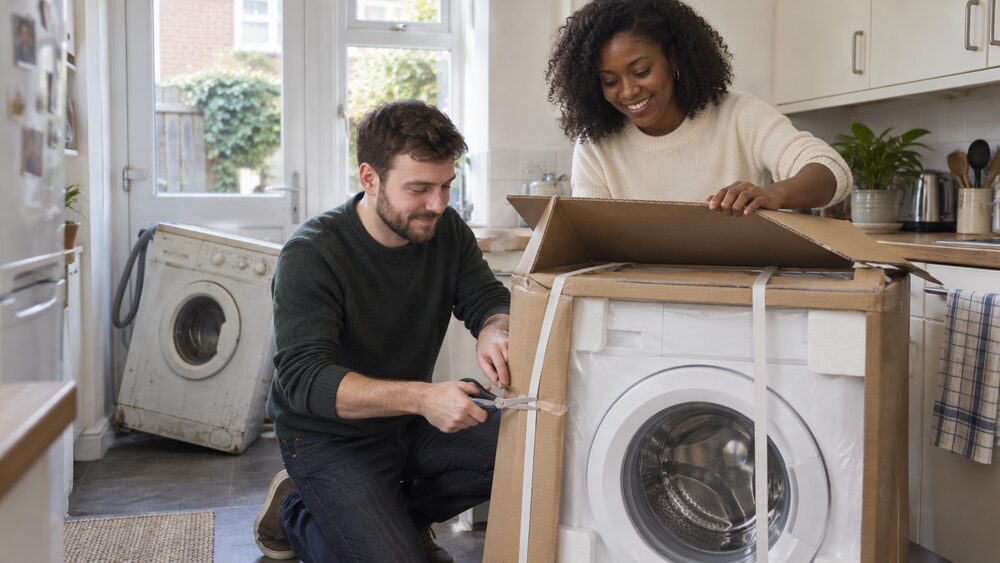
If you need a fridge, a cooker or a bed and cannot pay for it in one go, there are two very different routes. A credit union household goods loan is a cash loan from a not for profit lender owned by its members, and one credit union lends up to £500 for furniture and electrical items1. Rent-to-own is a hire purchase agreement where you pay weekly or monthly for the item and do not own it until the final payment2.
The cost gap is the reason this choice matters. Borrowing £500 from one credit union costs £547.18 over 52 weeks, or £545.85 over 12 months3. Rent-to-own has been found to leave consumers paying almost three times as much for an appliance as buying it outright from a mainstream retailer4. A price cap now limits the interest on each rent-to-own agreement to 100% of the cost of the goods, so the most you can be charged in credit is the price of the item itself5.
This page sets out what each option is, what it costs, how repayments work, how to apply, and what happens if you fall behind. It also covers the smaller loans credit unions run for school uniforms, and where to get free help if rent-to-own payments have already become a problem.
What a credit union household goods loan offers
Credit unions are not for profit community lenders providing affordable loans and savings7. They are owned and controlled by their members, and members' savings are used to fund loans to other credit-worthy members8. That structure is why the pricing tends to be lower than the alternatives aimed at the same borrowers.
Most credit unions lend small amounts, roughly £50 to £3,000, and some lend larger sums over longer periods for things like a car or home improvements9. Loans start from £50 at some credit unions7. For personal loans of up to around £2,000, credit unions are described as offering the most competitive rates in the UK10.
The household goods loan is a specific product within that range. One credit union lends up to £500 for furniture and electrical items, or up to half of any existing loan with it1. The same credit union lends up to £100 for each child for school uniforms where you cannot add to a loan you already have1.
Some credit unions go further and stock the goods themselves. They offer electrical and household goods that you pay for in weekly instalments and that are much cheaper than the ones you may find on the high street11. That model removes the shopping trip as well as the interest.
Rent-to-own exists because the same need is not always met by mainstream credit. Around two-thirds of rent-to-own purchases are for essential household items such as white goods and furniture5. If you are weighing up the two, the types of credit union loan page sets out the wider range, and what a credit union loan costs explains how interest and early repayment work.
What it costs: £500 borrowed means £616 repaid
The clearest way to compare is to look at what a fixed sum costs to repay. One credit union publishes a loan table showing that £500 borrowed over 52 weeks is repaid as £547.18 in total, and the same £500 over 12 months is repaid as £545.853. The difference between the two is small because the term is similar.
Smaller loans scale down in the same way. On the same published table, £100 borrowed over 52 weeks is repaid as £109.42, with weekly payments of £2.113. The household goods product at another credit union shows £100 borrowed costing £23 in total credit and £123 repayable, and £200 borrowed costing £47 in credit and £247 repayable1.
Rent-to-own is priced differently, and the difference is large. Research for the government found that consumers were paying almost three times as much for an appliance compared with buying it outright from a mainstream retailer4. The Financial Conduct Authority introduced a price cap limiting the interest charged on a product to 100% of the cost of the goods4. In practice that means a customer will not pay credit costs, meaning total interest payable, that are higher than the price of the product including delivery and installation12.
The cap is a ceiling, not a target. It stops the worst outcomes rather than making rent-to-own cheap. The FCA's own evaluation of the rent-to-own price cap, published in December 2020, showed that it had reduced prices13. Independent analysis has recommended extending the cap to second-hand goods sold by rent-to-own firms so that it covers all potentially high cost items5.
Weekly or monthly repayments over 62 weeks
Credit unions set repayment schedules to fit a member's income, and the frequency varies by provider. Moray Firth, Just Credit Union and T.P.M. Credit Union all offer weekly, fortnightly, four-weekly or monthly repayments14. Darlington Credit Union offers weekly, fortnightly or monthly "depending on which one suits you best"17, Cloughfern Credit Union offers weekly, fortnightly or monthly18, and Oldham Credit Union members choose weekly or four-weekly19. Levern Credit Union lets members pay weekly13.
Terms vary too. Home Owner Loan runs 12 to 84 months20, London Mutual Credit Union personal loans run 6 to 60 months21, and credit union loans generally run up to 36 months22, with most offering a two to five year repayment plan23. A £100 Household Goods Loan repaid weekly costs £2 a week, £23 in total credit and £123 repayable; a £200 loan costs £4 a week, £47 in credit and £247 repayable11.
Repayment schedules are built around how you are paid. One credit union lets borrowers pay weekly, fortnightly, every four weeks or monthly depending on their circumstances3. That flexibility matters if your income arrives weekly rather than monthly, or if it varies.
The term you choose changes the weekly figure. On the same published table, £100 borrowed over 52 weeks is repaid at £9.42 a week, and £500 borrowed over 52 weeks is repaid at £10.53 a week3. Stretching the same £500 over 12 months gives a monthly repayment of £45.723. The total repaid is slightly lower on the monthly schedule, £545.85 against £547.18, because the term is marginally shorter3.
Rent-to-own works on a similar rhythm but with a different legal shape. To count as rent-to-own, an agreement cannot be for a car or for business purposes, and payments must be due more than once a month24. That is what separates it from a standard hire purchase agreement on a vehicle.
The ownership rule is the part that catches people out. With rent-to-own you will not own the goods until you finish paying, which means you cannot give or sell the goods to someone else in the meantime25. The same applies to hire purchase and conditional sale more generally: you do not own the item until you make the final payment and complete the agreement, so you need your lender's permission to sell before then26.
Credit union loan or rent-to-own: how each one works
The two products solve the same problem in opposite ways. A credit union loan gives you money, and you buy the goods. Rent-to-own gives you the goods, and you pay for them over time while the lender keeps ownership until the end.
| Credit union household goods loan | Rent-to-own | |
|---|---|---|
| What you get | Cash, or goods paid for on your behalf | The goods themselves |
| Who owns the item | You, from purchase | The lender, until the final payment25 |
| Typical amount | Up to £500 for furniture and electricals1 | Set by the price of the item |
| Repayment rhythm | Weekly, fortnightly, four-weekly or monthly3 | More than once a month24 |
| Interest limit | Rates capped27 | Credit charges capped at 100% of the goods' price5 |
| If you stop paying | Arrears on a loan | The lender can sometimes take the goods back25 |
Credit unions are not for profit community lenders, so the surplus goes back to members rather than to shareholders7. Some pay a loan interest rebate, a refund of loan interest paid to all members who borrowed during the preceding financial year8. That is a feature rent-to-own does not have.
Rent-to-own sits inside the wider high-cost credit market, which covers bank overdrafts, loans, buy-now-pay-later and rent-to-own schemes28. It is regulated, and complaints about it reach the Financial Ombudsman Service. In 2024/25 the ombudsman upheld 50% of the hire purchase complaints it decided, across 83 cases20. A 50% uphold rate means half the complaints brought about this kind of agreement were found in the consumer's favour.
If you are comparing more broadly, credit union loans or doorstep lending and credit union loans versus payday loans cover the other high-cost options, and credit union or bank looks at the mainstream alternative.
Where rent-to-own fits in the wider high-cost credit market
Rent-to-own is not a niche product. In 2022, 1.8% of UK adults, about 1.0 million people, held a rent-to-own agreement, a fall of 0.5 percentage points since 20206. That is a large number of households, and the fall suggests the price cap and wider scrutiny have had an effect.
The cost of using this kind of credit is measurable. Research on the poverty premium found that rent-to-own and catalogue credit were both relatively common and costly, at £199 and £186 a year respectively for users in Britain14. Those are annual figures for people using the products, not one-off charges.
The regulatory history explains why the market looks as it does. The FCA introduced a price cap that limited the cost of interest charged on a product to 100% of the cost of the goods4. The cap was set as a total credit cap of 100%12, and the FCA's evaluation in December 2020 found it had reduced prices13. Independent analysis has since recommended extending the cap to second-hand goods sold by rent-to-own firms so that it includes all potentially high cost items5.
For a consumer, the practical point is that the cap protects you against the most extreme costs but does not make the product competitive with buying outright. If you can borrow at credit union rates instead, the arithmetic above shows the difference: £500 costs £547.18 to repay at one credit union3, against a rent-to-own price that has historically run to almost three times the outright retail price4.
How to apply for a household goods loan
The first step is membership. Credit unions have a common bond, which may be based on where you live or work, the type of occupation you have or your employer21. You have to be within that bond to join, and the common bond page explains how to check. If you are not sure which credit union covers you, the directory lists them.
Once you are a member, lending practice varies. Some credit unions will lend to you as soon as you become a member, while others will only lend after you have saved for a set period9. Affordability is checked against the money you have left after paying your bills9. If you are new to borrowing, borrowing as a new member covers what to expect.
Applications can usually be made in person at a branch or by post, phone or online22. Some credit unions now let you join and apply entirely online, so it is worth checking before you travel. The applying to borrow from a credit union page walks through the process in more detail.
A household goods loan is often paid out against the item rather than as cash, because the loan is for a specific purchase. Ask your credit union how it handles this. If you are buying from a retailer, some credit unions will pay the supplier directly.
Topping up after 24 months of on-time payments? Where the limit applies
If you have an existing loan and need something else, a top-up is often possible. One credit union will lend up to £500 for furniture and electricals, or up to half of any existing loan, and a top-up must be taken within 24 months of the original loan1. That 24-month window is the limit to watch: after it, the top-up route closes and you would need a new loan instead.
The same credit union applies a further condition to top-ups. You must not have entered, or be planning to enter within the next 12 months, a bankruptcy order, a debt relief order, an individual voluntary arrangement, debt collection or a debt management plan1. The two conditions sit alongside each other, and the documents do not resolve how they interact, so ask your credit union which applies to your situation.
More generally, credit unions usually let members borrow at least two or three times the amount they hold in savings, depending on the individual loan policy15. That is a rule of thumb rather than a guarantee, and it is set by each credit union. If you are repaying a loan and want to understand how your savings interact with it, borrowing against your savings and withdrawing shares while repaying a loan cover the detail.
School uniform loans: up to £100 per child
School costs arrive in a lump at the end of the summer, which is exactly the shape of expense a small credit union loan suits. One credit union lends up to £100 for each child for school uniforms, where you cannot add to a loan you already have with it1. The wording matters: the uniform loan is designed for members who already have borrowing and cannot extend it.
That makes it a useful companion to a household goods loan rather than a replacement. If you are already repaying a household goods loan and the uniform bill lands, the uniform loan is a separate facility rather than a top-up on the existing one. Other credit unions handle back-to-school costs differently, so ask what yours offers. The loans for school uniforms and back-to-school costs page covers the wider picture.
Credit unions also run savings accounts aimed at the same seasonal pressure. Christmas savers and Christmas loans work on the same principle of spreading a known annual cost across the year, and the Christmas savers and Christmas loans page explains how they work.
If you fall behind on rent-to-own or a credit union loan
Rent-to-own arrears are a priority in a way that a credit union loan is not. Rent arrears are a priority debt and should be repaid before credit debts such as loans and credit card repayments17. If you are behind on both, the rent comes first.
If you are on Universal Credit and behind on rent, you can ask for a managed payment to your landlord through your online journal, in person at the jobcentre, or by calling the Universal Credit helpline on 0800 328 564418. That route exists to stop rent arrears growing while other debts are dealt with.
For the credit union loan itself, talk to the credit union early. Credit unions are member-owned, and the falling behind on a credit union loan page sets out what happens next. If a lender has treated you unfairly, the Financial Ombudsman Service can look at complaints about unaffordable lending19.
Free and impartial help is available. MoneyHelper provides guidance on rent arrears and what to do if you cannot pay16, and the debt guide covers the full range of solutions. If you are worried about losing your home, there is dedicated advice for England and Wales23 and for Scotland29.
Sources31 cited
- Household Goods Loan Plus Credit Union, 2026
- Budgeting, saving and borrowing Business Debtline, 2026
- Loan table Levern Credit Union, 2026
- Rent-to-own price cap House of Commons Library, 2026
- FCA rent-to-own price cap StepChange, 2026
- Financial Lives 2022: credit and loans Financial Conduct Authority, 2022
- Save, bank or borrow with a credit union Welsh Government, 2026
- About credit unions Find Your Credit Union, 2026
- Credit unions Building Societies Association, 2026
- Fair and affordable finance Responsible Finance, 2026
- Weekly payment store debt StepChange, 2026
- FCA introduces price cap in the rent-to-own sector Finance & Leasing Association, 2019
- Woolard Review report Financial Conduct Authority, 2020
- Poverty Premium 2026 University of Bristol Personal Finance Research Centre, 2026
- Debt consolidation (England and Wales) National Debtline, 2026
- Rent arrears: problems paying your rent MoneyHelper, 2026
- Housing related debts Advice NI, 2026
- Help while waiting for a Universal Credit payment nidirect, 2026
- Unaffordable lending Financial Ombudsman Service, 2026
- Annual complaints data and insight 2024/25 Financial Ombudsman Service, 2025
- Credit unions House of Commons Library, 2026
- Personal loans Citizens Advice, 2026
- Advice if you are worried about losing your home (England and Wales) National Debtline, 2026
- Hire purchase debt (Scotland) National Debtline, 2026
- Debt consolidation (Scotland) National Debtline, 2026
- Hire purchase debt (England and Wales) Business Debtline, 2026
- Credit union current accounts MoneyHelper, 2026
- High-cost credit House of Commons Library, 2021
- Advice if you are worried about losing your home (Scotland) Business Debtline, 2026
- Selling assets to clear debt (Scotland) National Debtline, 2026
- Selling assets to clear debt (England and Wales) Business Debtline, 2026

 MoneyHelperFree, impartial money and pensions guidance, set up by government
 FSCSProtects your money if a bank, insurer or investment firm fails
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 StepChangeFree debt advice and solutions from a charity
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales