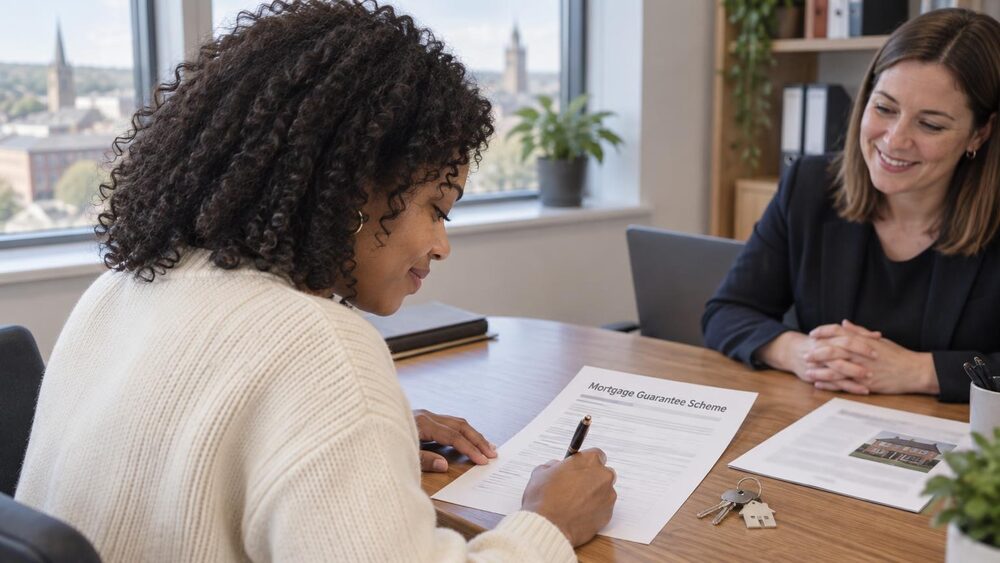
The 95% mortgage guarantee scheme, introduced by the government after the pandemic to encourage lenders to offer 95% mortgages, was due to run until 30 June 2025 but has been made permanently available1. The scheme operates UK-wide3.
Under the scheme, the government partially compensates lenders who offer 95% loans if the borrower misses a mortgage payment1. To qualify, lenders must offer repayment mortgages at between 91% and 95% loan to value, and loans can only be offered on properties priced up to £600,0001. Borrowers must have a deposit of at least 5% of the price of the property, pass the usual affordability checks, and buy a home costing no more than £600,0003. The scheme is open to first-time buyers as well as people looking to move home3.
Deals available under the scheme are no different to standard mortgages, so borrowers can apply directly with lenders or via a mortgage broker1.
"The scheme was due to run until 30 June 2025, but it has been made permanently available."
Experian's guide, published before the change, states that the scheme "will run until 30 June 2025 and is available throughout the UK"3. Which? reports that it has since been made permanent1.
Why it matters for households
The scheme's permanent status means the option of a 95% loan to value mortgage, backed by a government guarantee to the lender, remains available beyond the original 30 June 2025 end date1. It applies to buyers across the UK, including first-time buyers and those moving home, on properties priced up to £600,0003. A borrower using the scheme needs a deposit of at least 5% of the purchase price and must pass affordability checks3.
The scheme sits alongside other government-backed routes to buying a home, including shared ownership, where buyers in England purchase a minimum initial stake of 10%, though many schemes require at least 25%, with a deposit of at least 5% of the share and a mortgage covering the remaining 95%1. Household income limits for shared ownership in England are £80,000 or less, or £90,000 or less in London1.
Other schemes have different end dates. Help to Buy equity loans remain available only in Wales, where first-time buyers can get a 20% equity loan on a new-build property priced up to £300,000, with loans repaid within 25 years; that scheme runs until September 20261. The Help to Buy equity loan scheme is no longer available in England or Scotland2.
What happens next
No further end date for the 95% mortgage guarantee scheme has been reported following its move to permanent status1. The Welsh Help to Buy equity loan scheme continues until September 20261.

 MoneyHelperFree, impartial money and pensions guidance, set up by government
 StepChangeFree debt advice and solutions from a charity
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales
 ShelterFree housing advice from a charity