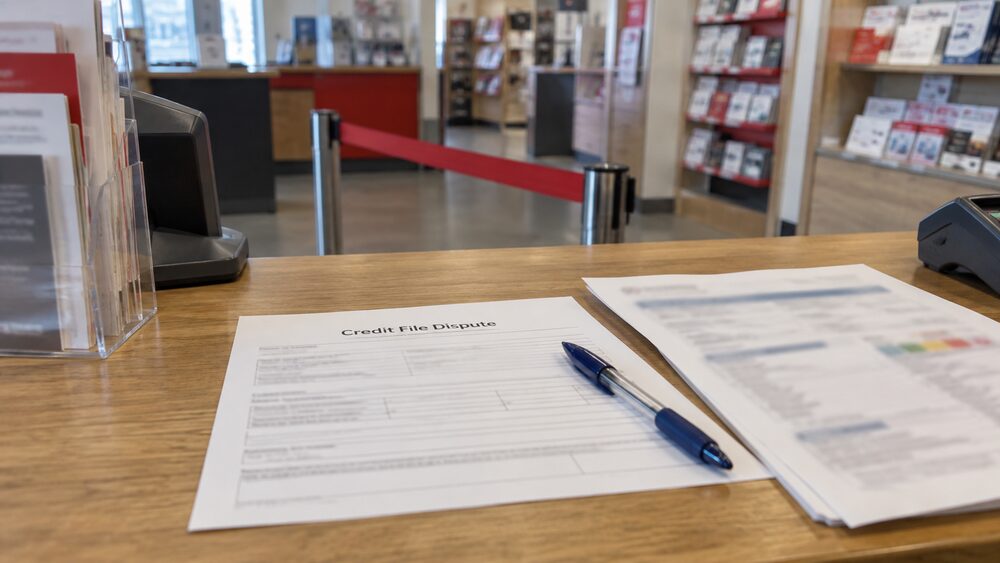
If something on your credit file is wrong, or true but needs context, there are two routes. A dispute asks the credit reference agency to go back to the lender and check the entry. A notice of correction is a short statement, up to 200 words, that you write yourself and that sits alongside the entry, visible to any organisation that searches your report1.
They do different jobs. A dispute is for facts that are wrong: an account that is not yours, a payment marked late that you made on time, a default recorded twice. A notice of correction is for facts that are accurate but misleading on their own, such as a run of missed payments caused by redundancy or illness. A dispute can end with the entry changed or removed. A notice of correction does not change the entry at all; it explains it.
Both are free, and neither lowers your credit score. Lenders and credit reference agencies have up to 28 days to respond to a dispute, and Experian says it usually resolves issues in less than two weeks4. A notice of correction stays on your file for as long as the information it relates to remains on file, or until you ask for it to be removed1.
Correcting your credit file: dispute or notice of correction
The two routes are often confused because both start with you spotting something on your report. The difference is what you are asking for.
A dispute says: this entry is inaccurate, please check it. The agency cannot simply delete it. Credit reference agencies cannot amend data on credit files provided by other companies without that company's permission, so the agency has to go back to the lender that supplied the entry and ask it to verify or correct it8. If the lender confirms the entry is right, it stays.
A notice of correction says: this entry is accurate, but here is the context. The Information Commissioner's Office describes it as a statement explaining your situation which will be seen by anyone who looks at the entry on your credit reference file and should be taken into consideration if you apply for credit2. It is free to add and can be up to 200 words5. You can add or remove one at any time, and only organisations that check your credit reference file will see it9.
The practical effect is different too. If there is a notice of correction on your report, your application must be referred for a manual decision rather than being scored automatically10. That matters: a person reads your explanation rather than a system reading only the marker.
Start by checking your report with Experian, Equifax and TransUnion
You cannot dispute or explain something you have not seen. There are three credit reference agencies in the UK that store information about your credit history: Equifax, Experian and TransUnion11. They are the three biggest organisations for checking your credit report12.
You can get a free copy of your credit report from a credit reference agency, and a credit reference agency must give it to you for free if you ask for it13. You can make a request verbally or in writing, and the agencies usually provide an online form you can use to apply2. Under the Consumer Credit Act 1974 and data protection law, you have the right to access your credit file1.
Check all three. Not all lenders report to credit reference agencies, and some lenders may only report to one or two of them, so an entry can appear at one agency and not another14. If you suspect a county court judgment has been made against you, check your credit report with Experian, Equifax or TransUnion15.
Raising a dispute: the agency asks the lender to check
A dispute is a request for the agency to investigate an entry with the lender that supplied it. The agency is the middle party, not the decision maker.
The limits of what an agency can do are set out in the rules it works under. Credit reference agencies cannot amend data on credit files provided by other companies without that company's permission8. There is also no requirement under data protection law for lenders to report such data to all the credit reference agencies, so it is up to the lender to decide which agency it wishes to use, if any2. That is why the same account can be missing from one of your three reports entirely.
If the entry is a county court judgment you never received, the route is different again. The court where the judgment was made is the body to contact, not just the agency12. Where a judgment has been recorded against you in error, this can be raised as a dispute with the credit reference agency you obtained your credit file from7.
Where a lender has made a mistake, the Financial Ombudsman Service can ask the bank to correct a credit file, refund extra costs, and pay compensation for distress or inconvenience16. It can also tell a lender to pay compensation for any distress or inconvenience where the lender has not done enough to help17.
How long a dispute takes and when your file updates
Timings are set by the rules the agencies and lenders work to, not by how quickly you send your request.
Lenders and credit reference agencies have up to 28 days to respond to a dispute, and Experian says it usually resolves issues in less than two weeks4. One independent source puts the response time at within one month18. If you are waiting, those are the windows to hold in mind rather than a same-day fix.
Separately, the underlying data on your file refreshes on the lender's own reporting cycle. TransUnion says this typically happens every four to six weeks, and each provider has its own update schedule and reporting timelines1. So even after a correction is agreed, the change appears when the lender next sends its data through.
A notice of correction is different: it is added by the agency on your instruction, so it does not wait for a lender's reporting cycle. It stays on your credit report for as long as the information it relates to remains on file, or until you ask for it to be removed1.
Entries you did not make: fraud on your credit file
An account you do not recognise is the clearest case for a dispute, and it needs handling quickly.
The warning signs are specific. Items that you do not recognise appear on your bank or credit card statement19. Transactions that you did not make are a signal of digital wallet fraud20. If you think your credit or debit card, online bank account or cheque book have been stolen or hacked, speak to your bank or building society straight away21.
Then check your file. A copy of your credit file can be requested to check for any suspicious credit applications19. Credit card and bank statements are worth checking regularly for suspicious activity, alongside monitoring your credit report19. Each of the three credit reference agencies can also be contacted to have a notice of correction added to your credit report12.
One limit is worth knowing before you start. When you take out any type of credit for another person, if that credit agreement is in your name, unfortunately the default will appear on your file7. A dispute cannot remove an entry that is correctly recorded against an agreement you hold, even if someone else benefited from the money.
Where a dispute will not change your file
Some things people try to dispute are not credit file entries at all, and some are accurate entries that no dispute can remove.
A parking charge notice will not appear on your credit file; your credit file will only be affected if a county court judgment is registered22. Asking a lender for information about your credit agreement will not affect your credit file23. Getting debt advice does not affect your credit file24, and debt advice does not affect your credit score, though some debt solutions will25.
Contacting your lender about difficulty while you are up to date with payments will not have any impact on your credit file26. Discussing your options with your lender will not have any impact on your credit file27. If a time order is made and you keep up to date with the payments, your creditor cannot apply for a county court judgment to be made, so a judgment will not appear on the Register of Judgments, Orders and Fines or on credit reference agency files28.
What a dispute cannot do is remove accurate adverse information. Credit reference agencies will not remove adverse information if it is correct, although consumers may ask to submit a notice of correction note to explain the circumstances8. That is the dividing line: accurate but explained, or inaccurate and corrected.
Lenders decide, not credit reference agencies
The single most useful thing to understand about this whole process is who decides what.
Credit reference agencies provide information to help lenders make a decision. They do not say who can and cannot have credit29. They do not have a blacklist of people who should not get credit10. Lenders use information from credit reference agencies, rather than The Gazette, to decide if they will lend to you30.
The law backs this up in a specific way. Where a creditor decides not to proceed with a prospective regulated agreement on the basis of information from a credit reference agency, the creditor must, when informing the debtor of the decision, inform the debtor that this decision has been reached on the basis of information from a credit reference agency, and provide the debtor with the particulars of the agency including its name, address and telephone number31. The Consumer Credit (Disclosure of Information) Regulations 2010 set the same requirement: the creditor must inform the debtor that the decision was reached on the basis of information from a credit reference agency and of the particulars of that agency32.
So if you are refused and want to know why, you are entitled to be told which agency was used. If the agency does not keep a file relating to you, it must give you notice of that fact, but need not return any money paid33.
Where a complaint about a lender's conduct cannot be resolved, the Financial Ombudsman Service can tell the lender to put things right and pay compensation for distress or inconvenience34. It can also ask the lender to change the amount you owe, refund you money, or make arrangements so you can pay things back35. Where a lender says you owe the wrong amount, remedies can include waiving or refunding interest, extra time to make missed payments, restructuring loans, or compensation for distress and inconvenience36.
If the agency or the lender says no
A refusal is not the end of the route. There are two directions to go in.
If the agency will not act, the underlying rule is that it cannot amend lender data without the lender's permission, so the pressure has to be applied to the lender8. If the lender will not correct an entry, that becomes a complaint about the lender, and the Financial Ombudsman Service can look at it. Where evidence relied on by the lender is of equal relevance to evidence provided by the consumer and there is a conflict, the lender must resolve the conflict in favour of the consumer unless it can demonstrate a clear basis for not doing so14.
If the problem is a judgment rather than an account, the court is the route, not the agency12. In Scotland, the Registry Trust notifies credit reference agencies of all decrees, recalls and dismissals on a regular basis, so a recall at the sheriff court feeds through to the agencies37.
Free, impartial help is available if the money behind the entry is the real problem. StepChange provides debt advice24, and the Money Advice Service and National Debtline both publish free guidance on credit reference agencies and your rights3. Getting that advice does not affect your credit file24.
Sources38 cited
- What is a Notice of Correction and how can I add one to my credit report TransUnion, 2026-09-28
- Credit Information Commissioner's Office, 2026-09-25
- Credit reference agencies (England and Wales) National Debtline, 2026-09-25
- How to improve your credit score Which?, 2025-10-24
- Completing a DPP StepChange, 2026-09-25
- Payday lending report Financial Ombudsman Service, 2026-09-27
- Credit Information Commissioner's Office (Welsh), 2026-09-25
- Credit reference agencies and your credit file House of Commons Library, 2026-09-26
- Debt and mental health Advice NI, 2026
- Credit reference agencies (Scotland) Business Debtline, 2026-09-26
- Will I be blacklisted? Mental Health and Money Advice, 2025-09-08
- How to get a mortgage with CCJs Which?, 2025-08-20
- County court judgments and your credit rating Citizens Advice, 2026-09-25
- CONRED 5 Financial Conduct Authority, 2026
- County court judgments (England and Wales) National Debtline, 2026-09-25
- IT problems at banks Financial Ombudsman Service, 2026-09-25
- Interest rates applied to mortgages Financial Ombudsman Service, 2026-09-26
- How to rent with a poor credit history Shelter England, 2026-05-01
- Identity theft Information Commissioner's Office, 2026-09-25
- Digital wallet fraud Take Five, 2026-09-26
- Protect your identity nidirect, 2025-10-28
- Parking charge notices (England and Wales) National Debtline, 2026-09-25
- Credit agreements: getting information (England and Wales) National Debtline, 2026-09-25
- How we help StepChange, 2026-09-25
- Debt myths true or false StepChange, 2026-09-25
- Financial difficulties with mortgages Financial Ombudsman Service, 2026-09-26
- Interest on mortgages Financial Ombudsman Service, 2026-09-26
- Time orders for unsecured debt (England and Wales) Business Debtline, 2026-09-26
- Debt advice services Credit Services Association, 2026
- Bankruptcy register StepChange, 2026-09-25
- Consumer Credit Act 1974, section 157 legislation.gov.uk, 2026
- The Consumer Credit (Disclosure of Information) Regulations 2010 legislation.gov.uk, 2010-03-28
- Consumer Credit Act 1974, section 158 legislation.gov.uk, 2026
- Buy now pay later Financial Ombudsman Service, 2026-09-26
- Logbook loans Financial Ombudsman Service, 2026-09-26
- Home credit Financial Ombudsman Service, 2026-09-26
- Money judgments and certificates of satisfaction FAQs Scottish Courts and Tribunals Service, 2026-09-26
- Bereavement Support Payment nidirect, 2026-06-24



 MoneyHelperFree, impartial money and pensions guidance, set up by government
 Financial Ombudsman ServiceFree, independent help when a complaint about a firm is not put right
 Citizens AdviceFree advice on money, consumer and legal problems in England and Wales
 StepChangeFree debt advice and solutions from a charity
 GOV.UKOfficial information on tax, benefits and government services